

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glass Fibers Market to hit USD 293.6M by 2032 at 5.5% CAGR

Glass Fibers Market 2026: Strategic Signals for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an evidence-led strategic preview of our Glass Fibers Market study—designed to inform boardroom discussions and capital allocation choices in 2026. This introduction highlights the market’s macro trajectory, near-term dynamics that should shape strategic options this year, and how leading suppliers are positioning themselves. It intentionally sketches insight and direction while reserving the granular segmentation tables and proprietary scenario outputs for the full report—your next step to secure the competitive edge.
Glass Fibers Market
Executive snapshot: why glass fibers matter in 2026
Glass fibers remain a foundational industrial material across construction, transport, wind energy, aerospace and advanced composites. After a resilient recovery over the 2020–2025 period, the global market reached approximately USD 202.5 Million in our base year (2025). Looking forward, PW Consulting’s demand model projects a steady compound annual growth rate (CAGR) of 5.5% through the 2026–2032 forecast window, culminating in a market size approaching USD 294 Million by 2032 under our central scenario.
Glass Fibers Market
For executive teams, three high-level takeaways flow directly from these numbers:
Glass Fibers Market
- Scale and growth are meaningful but not explosive—strategic positioning, premiumization and process innovation will drive differentiation more than volume alone.
- Incremental growth will be uneven by end-market and technology: renewable energy and lightweight transportation applications are growth conduits, while mature construction uses will favor cost and supply resiliency.
- Capital investments in capacity, product innovation and supply-chain control made in 2026 will materially influence competitiveness across the forecast horizon.
Market trajectory: a numbers-based portrait
The market’s historical performance demonstrates two contemporaneous forces: demand diversification toward higher-performance fibers and an expanded global production footprint. Between 2020 and 2025 the sector expanded significantly from the pandemic trough, reflecting restocking, infrastructure activity and early electrification-led demand. Our scenario framework projects steady expansion at a mid-single-digit CAGR (5.5%) from 2026 to 2032, with upside tied to accelerated electrification, carbon-fiber substitution economics, and policy incentives for renewables.
Importantly, growth does not erase structural challenge: raw material cost volatility, evolving trade measures and uneven capital intensity across product tiers will create winners and losers. In this environment, timely strategic choices in 2026—about capacity deployment, product mix and vertical integration—are decisive.
Near-term dynamics that should guide 2026 strategy
- Raw-material pressure and pass-through risk. Silica sand pricing trends continue to exert input-cost pressure on producers. Observed reference points for silica sand in major producing regions underscore sustained cost sensitivity across the value chain—an input trend that companies must model into pricing, hedging and supplier strategies.
- Trade and regulatory signals. New policy moves in major markets, including tariff actions and targeted regulatory measures introduced in early 2026, increase compliance and market-access complexity. For sales and sourcing teams, a nuanced understanding of tariff codes and their application is essential when designing cross-border supply chains.
- Premiumization and functional differentiation. Suppliers who shift mix toward electronic-grade, high-modulus and specialty glass fibers can unlock margin expansion—but that requires higher capex, focused R&D and closer customer collaboration to qualify materials for demanding end-uses.
- Electrification and mobility playbook. The transportation sector is adopting more composite solutions for light-weighting and EV architectures; firms that can pair glass fiber innovations with thermoplastic and thermoset system partners will capture more value.
Competitive landscape: who matters and why
The industry structure features a mix of large integrated producers and nimble specialists. Leading players continue to invest in capacity, technology and downstream integration—moves that will set the competitive map for the 2026–2032 period. The full report contains a detailed competitive matrix and capability heat-map; below are high-level strategic profiles of the core incumbents we track.
- China Jushi Co., Ltd. (Tongxiang) – A volume and scale leader with aggressive capacity expansion and investments in electronic-grade and high-modulus lines. Recent commissioning of major electronic-grade capacity signals a push into value-dense segments and downstream cloth production.
- Taishan Fiberglass Inc. (Taian) – A global continuous fiberglass manufacturer with strong placement in industrial and wind applications; strategic focus remains operational efficiency and breadth of product formats.
- AGY Holding Corp. (Aiken) – A differentiated specialty producer emphasizing S2-class fibers and integrated thermoplastic offerings. Recent product commercialization and footprint expansion reinforce its role in premium aerospace and advanced composites markets.
- 3B-the fibreglass company (Battice) – Focused on design-in with thermoplastic/thermoset systems for automotive and wind OEMs; technology partnerships and specialty reinforcements define its approach.
- Chongqing Polycomp International Corp. (CPIC) – Large-scale producer advancing alkali-free glass and fabric solutions targeted at wind power and aerospace suppliers; capacity scale is its competitive lever.
- Saint-Gobain Vetrotex – E-glass yarn and technical textile specialist with strong industrial and construction market channels; differentiation comes via textile know-how and fabric systems.
- Nitto Boseki, Taiwan Glass, Xingtai Jinniu, Shandong Huafa – Regional champions and niche specialists that together shape competitive intensity across local markets and specific end-use verticals.
Recent corporate events—large-scale electronic-grade plant commissioning, specialty product launches and regional capacity expansions—underscore two converging trends: a race for higher-value product tiers and an emphasis on localized manufacturing to shorten lead times. For buyers, this creates both opportunity for supplier consolidation and counterparty risk as capacity cycles turn.
Supply-chain and cost structure—practical considerations for 2026
- Input sourcing strategy. The cost and availability of silica sand and related inputs should be modeled at multiple price points. Successful manufacturers are adopting blended sourcing, longer-term offtake contracts and, in some cases, backward integration to stabilize cost volatility.
- Trade exposure management. Given the recent regulatory actions in major markets, procurement teams should map tariff exposure at the product-code level and evaluate alternative routing, bonded warehousing and tariff engineering where legal and economical.
- Operational excellence and digitalization. Intelligent manufacturing deployments—ranging from process automation to digital quality tracking—are becoming table-stakes for margin protection, especially in high-throughput fiber lines.
Strategic playbook for 2026
Leaders and challengers in the glass fibers sector should consider a balanced portfolio of near-term actions and longer-term bets:
- De-risk and differentiate. Prioritize product mixes that balance volume with margin, and pursue product certification paths early if pursuing aerospace, electronic or high-performance mobility applications.
- Right-size capacity investments. Avoid headline-grabbing capacity races that ignore regional demand elasticities; instead, align incremental capacity with signed offtake, modular production lines and flexibility to pivot among product grades.
- Pursue selective vertical moves. Target downstream integration where it meaningfully increases customer switching costs—examples include engineered cloths for electronics or integrated tapes for thermoplastic composite layups.
- Monitor M&A and partnership windows. M&A will be a lever for capability acquisition (e.g., specialized roving or textile expertise) and for regional market access. In 2026, expect acquisitive interest from both financial and strategic buyers for assets that de-risk entry to premium segments.
What PW Consulting’s full report delivers
Our comprehensive study—anchored to base year 2025 with historical analysis across 2020–2025 and detailed forecasting through 2032—contains the operational and commercial intelligence executives need to act in 2026. Core deliverables include:
- Proprietary market-sizing and demand forecast models (by product tier and end-market) with scenario variants for accelerated electrification and renewable deployment;
- Price and cost decks, including input-cost sensitivity analyses and break-even maps for different product grades;
- Supply-side mapping with asset-level capacity, utilization benchmarks and risk scoring (including lead-times and flex capacity);
- Competitive benchmarking and capability heat-maps for the leading suppliers, with acquisition target lists and integration playbooks;
- Commercial go-to-market guidance and a tactical supplier-selection matrix to support procurement and product development teams;
- M&A playbook and valuation frameworks tuned to glass-fiber specific multipliers and synergies;
- Regulatory and trade impact assessment—operational compliance checklists and alternate sourcing scenarios.
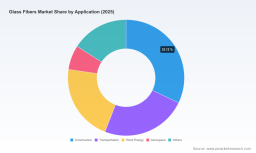
To preserve commercial value for subscribers, the public preview intentionally omits the granular regional and application breakdowns, the full numeric segmentation tables and certain proprietary sensitivity outputs. These are available in the full report and the interactive model accompanying it.
Final note: the window to influence long-term position is now
Decisions made in 2026—on where to invest, which partnerships to form, and how to hedge supply-chain risk—will determine whether a company captures premium growth pockets or is confined to margin compression in commoditized product tiers. PW Consulting’s Glass Fibers Market study equips executives with the data, scenarios and actionable recommendations necessary to make those decisions with confidence. For clients evaluating capital deployments, supplier strategies or M&A, the full report and the embedded financial models provide the actionable intelligence required to move from insight to execution.
Contact PW Consulting to access the full study, proprietary scenario models and bespoke advisory support for implementing a 2026 action plan tailored to your organization’s strategic objectives.
For detailed analysis of this topic, please visit the official page: Glass Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com