

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CVD Silicon Carbide Market to Hit USD 432.0M by 2032, Growing at 8.45% CAGR

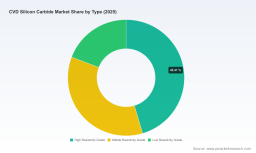
CVD Silicon Carbide Market — Strategic Briefing for 2026 Decision-Makers
As the world’s semiconductor and advanced materials supply chains reconfigure for a new wave of device scaling and power-electronics adoption, Chemical Vapor Deposition (CVD) Silicon Carbide (SiC) has moved from a niche engineering material to a strategic production input. This briefing distills the PW Consulting CVD Silicon Carbide Market study (base year 2025, historical 2020–2025, forecast 2026–2032) into the actionable intelligence senior executives and corporate strategists need for 2026 planning cycles. It highlights macro trajectories, competitive dynamics, supply-side pressure points, and a pragmatic playbook for capturing value — while reserving the report’s granular segment and regional tables for the full study.
CVD Silicon Carbide Market
Why this matters in 2026
-
CVD SiC is now a lever for both performance and process resilience in semiconductor fabrication, advanced optics, LED handling, and select industrial high-temperature systems. Decisions taken in 2026 — on capacity, sourcing, product roadmaps, and M&A — will determine who secures advantaged access to customers through 2032.
CVD Silicon Carbide Market -
Market-scale dynamics are clear and quantifiable: the PW Consulting model shows the global CVD SiC market expanding from a mid‑hundreds million-dollar base in 2025 and progressing at a compound annual growth rate of 8.45% through 2032. By the end of the forecast window, the market reaches a materially larger addressable base than it was at the start of the decade, reflecting faster adoption across high-end semiconductor process tools and power device handling.
CVD Silicon Carbide Market -
Concentration metrics indicate a market with meaningful incumbent strength — a CR3 of roughly 62.5% and a CR5 north of 70% — which creates both barriers and opportunities for market entrants and technology adopters.
Market trajectory: what the numbers imply
The headline data is straightforward: after steady growth through the early 2020s, the CVD SiC market recorded notable expansion by 2025 and is forecast to grow solidly through 2032 under a base-case 8.45% CAGR. That trajectory is driven by three structural forces: (1) broader semiconductor tool counts and process complexity that favor ultra-pure, plasma-resistant materials; (2) rising penetration in LED, optics and select industrial applications; and (3) an industry willingness to pay a premium for product reliability where downtime and particle contamination carry high economic cost.
For decision-makers, the numerical implication is twofold. First, capacity and supplier relationships are now determinative: scale and reliability deliver disproportionate commercial returns in a market with elevated concentration. Second, revenue pools will grow but remain constrained relative to other semiconductor supply segments — making margin protection and product differentiation (particle control, mechanical tolerances, lifetime in high-plasma environments) more valuable than volume alone.
Competitive landscape and what differentiates winners
The sector’s leading vendors combine deep materials expertise with tight integration into semiconductor OEM and fab supply chains. A short synthesis of core players illustrates strategic positioning (company URLs included for sourcing):
-
CoorsTek (Golden, Colorado) — specializes in ultra‑pure CVD SiC (PureSiC®) targeted at semiconductor processing and wafer carriers; their value proposition is engineered purity and application-specific coatings.
-
Morgan Advanced Materials (Woking, UK) — positions Performance SiC toward chemical/erosion resistance and thermal-mechanical stability for precision, long-life components in harsh process environments.
-
Ferrotec (Tokyo, with US operations) — offers ADMAP SiC solutions emphasizing high purity and wear/corrosion resistance for both semiconductor and industrial customers.
-
Tokai Carbon (Tokyo) — the established global supplier for solid CVD SiC products, recently accelerating partnerships and low-particle innovations tuned to sub‑5nm toolsets.
-
PremaTech Advanced Ceramics (Worcester, MA) — a US-focused manufacturer that emphasizes machinable and ultra‑pure CVD SiC for semiconductor, LED and defense applications.
Recent corporate moves signal the strategic priorities: Tokai Carbon’s 2024 partnership to develop polycrystalline SiC substrates for SmartSiC wafers, and its earlier product innovations for low-particle focus rings and exceptionally plasma‑resistant shields, are explicit bets on future process nodes and particle sensitivity. PremaTech’s expansion in the U.S. in 2024 underlines the near-term importance of onshore supply to North American fabs. These tactical developments are not isolated product announcements — they are capacity and capability plays that influence customer sourcing strategies and long-term contractual relationships.
Supply dynamics and risk vectors
Raw-material tightness and evolving regulation are the immediate risk multipliers for 2026 planning:
-
Silicon tetrachloride (SiCl4), the primary precursor for CVD SiC, has shown price and availability volatility. A price-index uptick of about 8.1% quarter-on-quarter in early 2026 — driven by constrained production and elevated energy costs in producing regions — has direct margin and sourcing implications for CVD SiC manufacturers.
-
Geographic supply differentials persist: published benchmarks from 2025 show Asian-Pacific feedstock offers priced materially lower than North American equivalents due to manufacturing concentration and differing regulatory frameworks, which creates arbitrage opportunities and shipping-based logistics tradeoffs.
-
Stricter environmental compliance for chemical processing is increasing compliance costs and creating intermittent supply uncertainty for feedstocks — a structural trend that will amplify the importance of diversified, compliant supply chains and long-term offtake agreements.
For procurement and operations teams, these dynamics translate into a set of risk mitigants that should be prioritized in 2026: multi‑sourcing for critical feedstocks, secured long-term contracts with inflation‑linked clauses, and regional production options to reduce tariff and transport exposure.
Strategic playbook for 2026 (practical moves)
-
Secure backward-linked feedstock arrangements: Pursue long-term contracts or equity links with SiCl4 producers in stable jurisdictions, including contractual clauses to cap pass-through price volatility where possible.
-
Invest selectively in particle and lifetime differentiation: R&D spend that reduces particle generation and extends plasma‑cycle endurance will earn pricing and loyalty premiums from advanced-node OEMs and foundries.
-
Evaluate regional capacity expansions: Near-shore or on-shore capacity can command a quality premium and shorten lead times for strategic customers — but capex should be staged, with ramp triggers tied to firm orders or long-term supply agreements.
-
Targeted M&A and partnerships: Acquisition of precision machining or coating capabilities (rather than broad market roll-ups) accelerates time-to-value. Partnerships with substrate or wafer innovators — as exemplified by Tokai Carbon’s arrangements — create integrated product stacks that are attractive to device makers.
-
Embed regulatory foresight into sourcing: Anticipate tightening chemical processing rules by auditing supplier compliance roadmaps, and prioritize suppliers with proven emissions control and waste handling capabilities.
What the full PW Consulting report delivers (practical, executable content)
Our full study is structured to move teams from insight to execution. Highlights include:
-
Comprehensive historical reconstruction (2020–2025) and a detailed 2026–2032 forecast model built on bottom-up use cases and validated OEM volumes — including sensitivity scenarios for feedstock price shocks and regional demand shifts.
-
Actionable supplier scorecards: capability matrices for incumbent vendors that map purity, particle performance, throughput, geographic footprint, and customer references to support vendor selection and negotiation playbooks.
-
Trade-off analyses for on‑shore vs. off‑shore manufacturing, with TCO breakouts that incorporate freight, regulatory, and inventory cost implications for multi‑year sourcing decisions.
-
Commercial templates and clauses for long‑term offtake and pricing escalation that reflect current feedstock volatility and compliance-driven cost inflation.
-
Strategic scenarios and M&A target shortlists calibrated to different corporate objectives: scale, capability, or geographic coverage.
Note: in keeping with our “trailer” principle, the headline study teases full segment-level demand curves, application and regional splits, and company-level shipment estimates. Those detailed tables and primary-source appendices are available in the full report and supporting datasets.
How to use these insights in boardroom decisions
-
Procurement: Use the supply-risk framework to re-price contracts and secure feedstock continuity before mid‑2026 price resets.
-
R&D/Product: Reallocate incremental spend to particle-reduction and plasma endurance enhancements — these features deliver outsized commercial returns in advanced fabs.
-
Corporate Development: Prioritize bolt-on targets that close capability gaps (machining, low-particle processes) rather than broad capacity plays unless paired with firm customer commitments.
-
Operations: Implement dual-sourcing and modular capacity expansion triggers that align capex with validated demand inflections in 2027–2029.
Final observations
By 2032 the CVD SiC market is clearly larger and strategically more relevant than it was a decade earlier, but it is not a commoditized volume play. The confluence of elevated concentration, feedstock vulnerability, and the premium placed on particle‑ and plasma‑performance means strategic moves in 2026 will disproportionately determine competitive positions through the next cycle. Firms that secure supply continuity, invest in differentiated material performance, and execute narrowly focused capability buys will unlock the highest margin pools.
PW Consulting’s full CVD Silicon Carbide Market report (base year 2025) delivers the detailed dataset, vendor scorecards, and executable templates required to translate these high‑level conclusions into boardroom-ready decisions. For segment-level demand curves, regional breakdowns, and the complete vendor benchmarking dataset, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: CVD Silicon Carbide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com