

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Autonomous Mobile Robotic Machine Market Hits USD 720M in 2025 — PW Consulting

Autonomous Mobile Robotic Machine Market: Strategic Playbook for 2026 Decision‑Makers
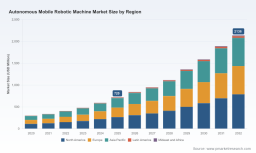
As companies recalibrate supply chains, expand fulfillment footprints, and digitize production lines, Autonomous Mobile Robots (AMRs) have moved from experimental pilots to strategic infrastructure. PW Consulting’s latest Autonomous Mobile Robotic Machine Market study — with a 2025 base year and a forecasting horizon through 2032 — frames that transition in hard numbers and operational realities. The market expanded from a modest base in 2020 to approximately USD 720 million in 2025 and is projected to grow at a compound annual growth rate of about 16.7% through 2026–2032, reaching well over USD 2 billion by the end of the forecast period. For executives deciding on capital allocation, partner selection, and capability investments in 2026, the implications are immediate: AMRs are no longer optional; they are a lever for competitive resilience and margin capture.
Autonomous Mobile Robotic Machine Market
Why this report matters to 2026 strategy
-
Timing of scale-up decisions: 2026 is a window where early adopters convert pilots into enterprise-wide deployments. The report quantifies adoption trajectories and provides decision frameworks to prioritize deployments that maximize throughput gains while controlling implementation risk.
Autonomous Mobile Robotic Machine Market -
Market sizing as a planning anchor: Corporate planning cycles require defensible assumptions. The study’s historical series (2020–2025) and multi‑year forecast (2026–2032) give CFOs and COOs a probabilistic anchor to test investment scenarios and build rolling CAPEX models aligned to revenue growth and productivity uplift.
Autonomous Mobile Robotic Machine Market -
Operational playbooks, not just slides: The research is designed for practitioners — procurement, automation engineering, and operations leadership — delivering templates for pilot-to-scale conversion, vendor evaluation matrices, and TCO calculators that map to 2026 budgets and ROI gates.
Market dynamics shaping 2026 decisions
The structural drivers that have produced double‑digit growth are now converging with near-term accelerants. Chronic labor tightness across manufacturing and logistics, continued e-commerce penetration, and the maturation of perception and fleet orchestration software are primary demand drivers. Meanwhile, component market normalization following the supply shocks of 2021–2023 has reduced episodic cost volatility for batteries and sensors, making total cost of ownership models more predictable for multi‑year procurement decisions.
On the supply side, three dynamics matter for 2026 planning:
-
Modularization of solutions: AMR platforms increasingly arrive with modular payloads and standardized APIs. This reduces integration lead times and enables “fleet-as-a-service” commercial models that change the procurement calculus from CAPEX to an OPEX subscription mindset.
-
Software as the differentiator: Fleet management, cloud scheduling, and edge AI for navigation are where vendors compete most fiercely. Companies that combine hardware scale with cloud orchestration are the most attractive partners for multi‑site rollouts.
-
Regulatory and certification pressure: Stricter regional AI and safety standards — especially in Europe — are increasing development costs and lengthening certification cycles. Compliant vendors gain market access advantages that factor into go/no‑go decisions for cross‑border rollouts.
Competitive landscape — how to read it for procurement and partnerships
The market shows a mix of global-scale operators, specialized innovators, and systems integrators. Several archetypes guide sourcing strategy:
-
Scale incumbents with proprietary ecosystems: These players operate at high unit volumes and bring end‑to‑end solutions (robot hardware, fleet software, cloud scheduling). Their strengths are throughput optimization, proven reliability at scale, and a deep bench of deployment experience — ideal for enterprises seeking low‑risk, high‑throughput implementations.
-
Specialist AMR innovators: Focused vendors deliver rapid‑deployment, collaborative AMRs tuned for intralogistics and manufacturing. They often win where flexible, mixed‑fleet operation and fast time‑to‑value are prioritized.
-
OEM and integrator plays: Traditional material handling OEMs and industrial automation suppliers bring domain expertise (heavy payloads, cleanroom environments, manipulator integration). They are preferred partners when AMRs must integrate tightly with legacy equipment and process constraints.
-
Software-first entrants: A smaller cohort concentrates on orchestration, AI scheduling, and analytics, enabling heterogeneous fleets to be managed under a unified control plane. These vendors are strategic if you plan to run mixed brands or move to a software‑defined logistics model.
In practice, procurement decisions in 2026 hinge less on brand labels and more on the match between a vendor’s archetype and the customer’s deployment profile: single‑site throughput optimization, multi‑site network orchestration, cleanroom or heavy payload specialization, or last‑mile autonomous delivery. Recent industry activity — product launches, live demos, and trade‑show integrations — confirms that differentiation has shifted toward software capabilities and end‑to‑end service offerings.
Regulation, raw materials and operational risk
Regulatory changes represent both a headwind and a moat. New AI transparency and safety requirements increase time‑to‑market and R&D expense for navigation and decisioning modules, but they also raise the bar for late movers. From a risk perspective, companies should budget for longer certification timelines and build compliance milestones into procurement contracts.
Supply chain risk has moderated relative to the pandemic years, but component sourcing — batteries, sensors, and compute modules — remains a strategic procurement category. Firms that lock in multi‑year component agreements or engage in co‑developed battery and lifecycle programs gain more predictable TCOs and improved service guarantees.
Practical contents of the PW Consulting report
-
Executive summary with investment timelines and management briefing notes for board‑level discussion.
-
Market sizing and demand scenarios (2020–2025 historical series; 2026–2032 base, upside, and downside cases) to stress‑test CAPEX plans.
-
Vendor landscaping and comparative capability matrices, highlighting deployment maturity, software capability, and integration risk — with practical negotiation levers and contract templates.
-
Implementation playbooks: pilot design, KPI selection, change‑management checklists, and scale‑out decision gates to translate pilot wins into multi‑site deployments.
-
TCO and ROI models that incorporate depreciation pathways, service contracts, energy and maintenance assumptions, and labor substitution effects; built to be plugged into corporate capital planning tools.
-
Regulation and compliance annex covering certification pathways, expected timelines, and recommended audit checkpoints for 2026–2027 rollouts.
-
Scenario planning templates covering disruption, component shocks, and accelerated automation adoption to help risk managers and strategic planners stress‑test their roadmaps.
Actionable recommendations for executives in 2026
-
Shift from one-off pilots to portfolio planning: Establish an AMR portfolio with clear business outcomes (throughput, labor substitution, safety), and prioritize projects using a value‑at‑stake framework rather than supplier novelty.
-
Insist on interoperability and open APIs: Favor vendors that commit to standardized integration points or provide middleware support — this reduces vendor lock‑in and preserves optionality in a fast‑evolving market.
-
Build compliance into procurement: Embed certification milestones and patch/update SLAs in vendor contracts to mitigate regulatory and cybersecurity risk.
-
Model TCO under multiple scenarios: Use the report’s TCO templates to compare leasing versus purchasing, and to quantify the tradeoffs of cloud orchestration versus edge autonomy.
-
Invest in change management: Successful scale‑outs fail because of people, not technology. Allocate a portion of automation budgets to training, local process redesign, and cross‑functional governance.
-
Use strategic partnerships to hedge risk: Consider co‑development agreements with suppliers or engage system integrators on a risk‑sharing basis for first‑of‑type deployments.
What we intentionally withhold here (and why)
In this introductory analysis we surface market scale, trajectory, strategic implications and executable recommendations to inform 2026 decision‑making. To preserve the integrity of ongoing commercial negotiations and to encourage direct engagement with our analysts, detailed sub‑segment revenue splits, regional percentages and line‑by‑line vendor market shares are available only in the full report. Those granular tables and the interactive models are the tactical artifacts teams need to convert strategy into procurement decisions; our report portal contains downloadable spreadsheets and vendor negotiation playbooks designed for board packages and sourcing events.
Final note: converting insight into prioritized action
For leaders who must deliver measurable outcomes in 2026, the choice is binary: treat AMRs as tactical cost‑savers or as strategic enablers of future operating models. PW Consulting’s Autonomous Mobile Robotic Machine Market study is structured to move you from the former to the latter — providing the market context, vendor intelligence, and implementation blueprints that help you de‑risk deployments and accelerate the path to meaningful productivity gains. For the complete dataset, interactive models, and the vendor negotiation kit, request the full report through our portal and schedule a briefing with our industry team.
For detailed analysis of this topic, please visit the official page: Autonomous Mobile Robotic Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com