

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hot Runner Market to Reach USD 6.5B by 2032 at 7.2% CAGR

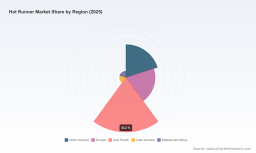
Hot Runner Market — 2026 Strategic Preview
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our Hot Runner Market research to inform strategic choices in 2026. This article pulls forward the report’s most actionable, directional insights while preserving proprietary segment-level granularity for subscribers. Consider this a strategic trailer: enough rigor to build confidence in the numbers and recommended plays, but intentionally withholding the fine-grained regional and application splits that are central to transaction- and sourcing-level decisions.
Hot Runner Market
Market trajectory at a glance
The hot runner market has moved from a mid-single‑billion base in 2020 to approximately 4.0 billion USD (revenue unit: Million) in our base year, 2025. Momentum continues into the forecast window: the market is projected to grow at a compound annual growth rate (CAGR) of 7.2% through the 2026–2032 forecast period, reaching roughly 6.5 billion USD by 2032 under our central case. That pace reflects a mix of steady demand in existing applications and incremental adoption driven by energy and process efficiency improvements.
Hot Runner Market
Historic performance (2020–2025) demonstrates resilient expansion across macroeconomic cycles, driven by: incremental automation of molding operations, growing demand for precision components in medical and electronics sectors, and supplier investments in energy‑efficient system architecture. Expect the next phase (2026–2032) to be defined less by raw market growth than by compositional change — technology-led substitution, supplier consolidation, and differentiated service models.
Hot Runner Market
Why this research matters for 2026 decisions
-
Supply‑chain resilience and total cost of ownership (TCO): With raw material volatility, tariffs on steel and aluminum, and local labor pressures, buyers cannot rely on unit price alone. The report provides TCO frameworks that capture up‑front hardware costs, energy consumption, maintenance cadence, and spare parts logistics to surface suppliers that win on life‑cycle economics — not just sticker price.
-
Energy and sustainability as differentiators: Advances such as energy‑saving heater architectures have become commercially material. Case evidence included in the study highlights field deployments delivering meaningful energy reductions versus legacy nozzles — a factor that should flow directly into CapEx prioritization and retrofit decisions.
-
Regulatory and quality risk management: Compliance with ISO and sector‑specific safety standards remains a gating factor in automotive and medical applications. The research maps regulatory pathways and certification timelines so sourcing and R&D roadmaps can be aligned to market entry requirements.
-
Concentration and competitive dynamics: The market exhibits a concentrated supplier layer at the top — our concentration metrics show a clear incumbent cluster that controls a substantial share of scale business. That structure creates opportunities for focused challengers to differentiate via specialization (e.g., silicone processing, integrated controls) and for buyers to extract value through staged competitive procurements.
-
Operational productivity and labor substitution: Widespread automation constraints in the molding workforce increase demand for systems that reduce manual adjustments and shorten changeover times. The study assesses which technical approaches and control systems are most effective in reducing operator dependency.
What the PW Consulting Hot Runner report contains — practical, executable content
-
Validated market sizing and scenarios: Transparent methodology, reconciled primary and secondary inputs, and three demand scenarios (conservative, central, upside) covering 2026–2032.
-
Supplier heatmaps and capability scorecards: Multi‑factor assessments (technology, service footprint, lead times, aftermarket support, energy performance) for the principal players. These are designed for use in RFx shortlists and supplier audits.
-
TCO and energy modeling tools: Interactive templates to compare nozzles and systems over expected life cycles, capturing energy, spare parts, downtime, and retrofit costs under varying runtime profiles.
-
Procurement playbook and negotiation frameworks: Staged sourcing approaches for different buying archetypes — OEMs, tier suppliers, and contract molders — including clause checklists for warranties, performance SLAs, and support agreements.
-
Technology adoption roadmaps: Decision matrices for when to retrofit versus invest in integrated systems, and guidance on controller standardization to reduce maintenance complexity across toolrooms.
-
Regulatory and tariffs impact matrix: Practical implications of standards and trade policy shifts on sourcing strategies and cost pass‑through.
-
Deal and M&A playbook: Target screening criteria and valuation sensitivities for potential acquisitions or strategic partnerships in the hot‑runner space.
Competitive landscape — focused intelligence on core suppliers
The market is led by a set of established suppliers and several regional specialists. Our assessment combines product capability, market reach, and recent strategic activity to profile strategic positions and likely plays in 2026.
-
Oerlikon HRSflow (San Polo di Piave, Italy; https://www.hrsflow.com/): Positioned as an innovation leader with proprietary STARgate and Glow HRS technologies. Strengths include application development for high‑precision medical and automotive components and visible investment in production capacity expansion.
-
Husky Injection Molding Systems Ltd. (Bolton, Ontario, Canada; https://www.husky.co/): A large integrated supplier whose recent trade show activities underscore a push into controller and energy‑efficient system showcases. Husky’s scale and system integration capabilities make it a logical partner for high‑volume manufacturers pursuing efficiency upgrades.
-
GÜNTHER Hot Runner Technology GmbH (Frankenberg, Germany; https://www.guenther-hotrunner.com/): Notable for energy‑savings innovations such as BlueFlow heaters and modular product families. Their technologies are attractive where energy cost and thermal stability directly affect part quality and operating cost.
-
Synventive Molding Solutions (Peabody, MA, USA; https://www.synventive.com/): Focused on high‑precision gate control solutions (e.g., IntelliGate), with strengths in lighting and automotive sectors where consistent gate performance is mission critical.
-
Mold‑Masters (Georgetown, Ontario, Canada; https://www.moldmasters.com/): Competes on standardized, cost‑effective solutions for commodity applications and maintains broad aftermarket reach.
-
Polyshot Corporation (New York, USA; https://polyshot.com/): A strong North American presence with customized system development and hands‑on support — often the supplier of choice where local service and rapid iteration matter.
-
INCOE Corporation (Rochester Hills, MI, USA; https://www.incoe.com/): Offers flexible customization for specific manufacturing needs and remains important for specialized or novel resin and tooling combinations.
-
DME Company (Farmington Hills, MI, USA; https://www.dme.com/): Broad product portfolio with global support capabilities, appealing to buyers seeking one‑stop sourcing for molds and hot runner systems.
Market concentration metrics indicate a dominant top tier, with the three largest suppliers capturing a meaningful share and the five largest comprising an even larger majority. This structure favors scale players on large, integrated contracts but opens room for specialists to win in niches where energy performance, control sophistication, or rapid service are differentiators.
Recent vendor activity and signals
-
Trade show and product showcases: Leading vendors continued proactive market engagement in 2025–2026 — exhibits at major trade shows (e.g., K 2025, ProPak Asia, Chinaplas) signal product refresh cycles and the launch of control and heater advancements that buyers should evaluate during RFIs.
-
Strategic distribution moves: Distributor partnerships announced in early 2026 reflect how suppliers are tightening service networks in North America to address aftermarket response times — a key selection criterion for time‑sensitive molders.
-
Technology diffusion: Energy‑saving heater architectures and gate control electronics are moving from premium to mainstream pockets of the market; buyers should plan for staged rollouts to de‑risk integration and capture early TCO gains.
Immediate, near‑term and strategic actions for executives (recommended)
-
Immediate (0–6 months): Run supplier TCOs for 3–5 shortlisted vendors using the report’s templates; pilot energy‑efficient nozzle retrofits on representative cavities; and update compliance checklists for medical and automotive tool acceptance tests.
-
Near term (6–18 months): Standardize controllers where possible to reduce spare parts inventory; consolidate supplier base where volume leverage yields measurable service and price improvements; and incorporate tariff sensitivity analysis into procurement budgets.
-
Strategic (18–36 months): Evaluate targeted M&A or JV opportunities to acquire specialized capability (e.g., advanced gate control or energy‑savings IP), and invest in digital remote‑monitoring to convert hot runner performance data into continuous improvement cycles.
Closing — how PW Consulting helps
Our Hot Runner Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) packages rigorous market sizing, supplier benchmarking, and practical playbooks purpose‑built for procurement, operations, and corporate strategy teams. It is intentionally structured to move decisions from opinion to evidence — with downloadable models you can run against your asset base and sourcing strategies.
To preserve the commercial integrity of our benchmarking work, detailed regional and application splits, cell‑level financials, and supplier scorecards are available only in the full report and accompanying data pack. If your 2026 roadmap requires validated TCOs, retrofit sequencing, or a bespoke supplier short‑list, PW Consulting can deliver a tailored advisory engagement that operationalizes these insights into contracts, CapEx plans, and implementation timelines.
Contact PW Consulting to access the full Hot Runner Market study and schedule a strategic briefing where we will walk through the models and implications for your business. The trailer ends here — the full direction and executional detail awaits in the complete research package.
For detailed analysis of this topic, please visit the official page: Hot Runner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com