

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Drinking Fountains Market Poised for 5.67% CAGR Through 2032

Drinking Fountains Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our forthcoming Drinking Fountains Market study. This briefing is designed as an executive “trailer”: it demonstrates the analytical depth and operational orientation that CISOs, procurement leaders, product heads, and M&A teams will need in 2026 — while deliberately withholding complete segment-level tables and granular regional breakdowns that are reserved for the full report.
Drinking Fountains Market
Why this study matters for 2026 decisions
The drinking fountains market is no longer a niche plumbing category; it sits at the crossroads of public-health policy, sustainability programs, and urban infrastructure renewal. Our analysis shows the market expanding from a 2025 base to materially larger levels by the end of our forecast horizon, at a steady compound annual growth rate (CAGR) of approximately 5.67%. For executives planning CAPEX cycles, product roadmaps, or channel investments in 2026, this trajectory signals predictable demand uplift but also heightened competition around product differentiation — especially in filtration, touchless interfaces, and compliance-led specifications.
Drinking Fountains Market
Market trajectory — what the headline numbers mean
-
Base-year context: the market in 2025 provides the starting point for near-term planning; growth thereafter is driven by infrastructure replacement cycles, institution-level procurement (schools, hospitals, municipalities), and a wave of sustainability programs prioritizing reusable-water solutions.
Drinking Fountains Market -
Forecast outlook: over the next several years the market is forecast to expand at roughly mid-single-digit CAGR, with the compounding effect producing a meaningful uplift in total market value by the end of the forecast horizon. This creates both volume opportunities for OEMs and margin pressure where commoditization occurs.
-
Strategic implication: the combination of stable growth and concentrated buying (institutional and municipal procurement remains a large and repeatable buyer) creates an environment where product differentiation — not low-cost alone — drives premium positioning and aftermarket revenue.
Demand drivers and segmentation dynamics
Demand now bifurcates along two durable vectors. First, functional performance: filtration efficacy (including emerging contaminants such as PFAS, lead and microplastics), refrigeration efficiency, and durability in high-traffic or vandal-prone settings. Second, compliance and accessibility: adherence to plumbing and safety standards, and to building and ADA codes, has become a non-negotiable tender requirement in many institutional procurements. Expect procurement specifications to increasingly reflect these two priorities in 2026.
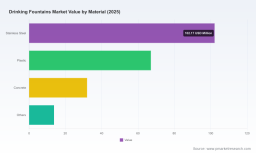
Our report maps the product landscape in operationally useful clusters — wall-mounted, floor-mounted, recessed and specialized units — and overlays material choices from stainless steel to composite systems. We stop short of publishing proprietary split tables in this preview, but the full study provides the granular product-by-material-by-application matrices purchasers and specifiers rely on.
Technology and product innovation — what’s winning
-
Touchless and sensor-enabled platforms. The last 18 months have accelerated adoption of touchless activations and usage telemetry (LED indicators, bottle counters), which are now standard in mid- and high-tier offerings.
-
Advanced filtration and compliance. Products that combine mechanical filtration with targeted media for PFAS and lead removal — and that include clear filter-status indicators and simplified front access for replacement — are increasingly demanded by health-conscious buyers.
-
Modularity and serviceability. Designs prioritizing front-access maintenance, modular refrigeration shut-off, and easy sensor replacement reduce maintenance total cost of ownership (TCO) and are strong selling points for facilities managers.
-
Antimicrobial surfaces and materials engineering. Bacteriostatic finishes and vandal-resistant constructions extend lifecycle in high-traffic public spaces and are central to spec documents in healthcare, stadium and transit projects.
Regulatory environment and standards — planning constraints and risk
Regulatory constraints are a structural driver of product requirements. Drinking fountains and refrigerated coolers must meet a layered set of standards — from ASME/CSA plumbing specifications to NSF safety and lead-free certifications — and electrically refrigerated units require relevant safety listings. At the building level, ADA and occupancy-code prescriptions can create firm minimums for deployment in certain institutional spaces. Our full study includes a compliance checklist and a procurement-ready regulatory pull-through that helps operations and specification teams translate standards into purchase orders.
Supply chain and materials — critical operational levers
Materials selection is not merely a cost decision. Stainless steel and lead-free components are frequently mandated by standards and by end-client specifications, and sourcing strategies must reflect both traceability requirements and volatility in raw-material pricing. Our analysis highlights supplier consolidation risks, lead-time sensitivities for filtration media, and practical mitigations for 2026 procurement cycles — from dual-sourcing templates to inventory-buffer scenarios tuned to municipal project timelines.
Competitive landscape — who sets the pace
The market is shaped by a set of long-established OEMs and specialist fabricators who compete on durability, compliance track record, and channel relationships. In the full report we provide vendor scorecards, commercial benchmarking and capability matrices. Below are directional observations on several market leaders represented in our study:
-
Elkay Manufacturing Company (Downers Grove, IL) — Known for commercial stainless-steel touchless units and bottle-filling stations tailored to hospitals and high-traffic facilities. Their emphasis on integrated bottle fillers and hygiene-focused designs makes them a frequent choice for specifications prioritizing durability and brand trust.
-
Haws Corporation (Sparks, NV) — A leader in heavy-duty indoor/outdoor filtration solutions and emergency hydration systems. Their product announcements emphasize touchless activation and integrated monitoring, appealing to municipalities and institutional customers.
-
OASIS International (Columbus, OH) — Offers both pressure-fed and mains-fed platforms with a strong footprint in healthcare and institutional filtration systems. Their channel strength in large centralized procurement remains noteworthy for bidders targeting national accounts.
-
Filtrine Manufacturing Company (Keene, NH) — Differentiates with custom stainless-steel and bronze solutions and finishes that target architect-driven public spaces and hospitals where aesthetic and material quality underpin specification decisions.
-
Murdock Manufacturing (City of Industry, CA) — Rapidly iterating product platforms; recent launches emphasize ADA compliance, integrated chillers, and simplified maintenance features. Their pace of product innovation makes them a competitor to watch for specification wins in the western U.S.
-
Halsey Taylor (Downers Grove, IL) — A durable-product specialist, often selected for schools, stadiums and healthcare facilities where robust service networks are a procurement requirement.
-
Acorn Engineering Company (City of Industry, CA) — Focuses on industrial, institutional and justice-sector solutions with an emphasis on heavy-duty stainless-steel construction and reliable field performance.
Recent product launches across multiple vendors underscore an industry pivot to sensor-enabled bottle fillers, filtration for emerging contaminants, and front-access maintenance features. Public funding programs and grant initiatives to install hydration stations in outdoor public spaces are further accelerating demand for turnkey solutions compatible with municipal procurement cycles.
Strategic imperatives for 2026
-
Design for specification: Ensure new models are engineered with the standards, accessibility, and filtration evidence that specifications now require. Investing in certifiable test data and third-party labeling removes a frequent barrier to municipal and institutional wins.
-
Serviceability as a differentiator: Reduce downstream O&M cost for buyers. Offer modular filter and refrigeration modules with a documented maintenance playbook and telemetry options for preventative service contracts.
-
Channel and partnerships: Build procurement-friendly offerings for national distributors and municipal contractors, and structure commercial terms for grant-funded programs and public-private partnerships.
-
Premiumization vs. cost: Target premium institutional segments (healthcare, transit hubs, higher education) with differentiated materials and filtration claims, while defending commoditized price tiers through manufacturing and supply-chain efficiency.
-
Regulatory foresight: Maintain an up-to-date certification roadmap (ASME/CSA, NSF, UL) linked to product roadmaps so that time-to-compliance does not delay bids.
What the PW Consulting report delivers
The full Drinking Fountains Market report is built for operators who need to act in 2026. It contains:
-
Market sizing and verified forecasts with scenario modelling and sensitivity to raw-material and regulation shocks.
-
Product and materials segmentation with tactical build-vs-buy recommendations and BOM-level cost drivers.
-
Channel and procurement playbooks, including RFP templates, compliance checklists and grant-capture guidance.
-
Competitive vendor scorecards, recent M&A and product-development tracking, and commercial benchmarking to inform pricing and go-to-market choices.
-
Supply-chain risk maps, dual-sourcing strategies, and recommended inventory policies aligned to municipal project seasonality.
-
Actionable strategic roadmaps for product teams and commercial leaders, with a prioritized list of near-term investments that maximize tender win probability.
Next steps — how to use this preview
If you are preparing CAPEX or procurement decisions for 2026, this market environment rewards disciplined specification work, supplier consolidation with service-level guarantees, and a product strategy that strings together filtration credibility with low TCO. For consulting-grade templates, event timelines, and the proprietary segmentation matrices that underpin vendor-targeted strategies, request access to the full PW Consulting study — it contains the data-validated recommendations you will need to convert the forecasted market growth into concrete commercial results.
PW Consulting’s Drinking Fountains Market study equips executives with the operational intelligence to make defensible decisions in 2026: whether you are an OEM refining product roadmaps, a distributor reshaping channel agreements, or a facilities leader aligning procurement to new regulatory demands, the full report provides the playbook and the spreadsheets you need to act with confidence.
For detailed analysis of this topic, please visit the official page: Drinking Fountains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com