

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cycling Helmet Market to reach USD 880.99M by 2032 at 3.26% CAGR

Bike Helmet (Cycling Helmet) Market — 2026 Strategic Preview
Executive trailer
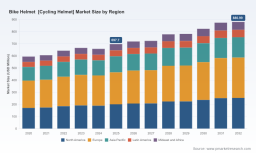
As global participation in cycling and micromobility continues to evolve, the bike helmet market is on an incremental growth path. Our analysis uses 2025 as the base year and projects the market forward through 2032, driven by a compound annual growth rate (CAGR) of about 3.26%. The market rose steadily through the early 2020s, with a small volatility episode in 2024, and is forecast to reach meaningful expansion by the end of the 2026–2032 forecast window. For executives planning resource allocation and portfolio pivots in 2026, this report distills what that steady, mid-single-digit growth means in terms of product strategy, channel investment and risk management.
Bike Helmet [Cycling Helmet] Market
Why this study matters for 2026 decision-making
-
Investment prioritization: A modest but resilient CAGR implies limited tolerance for speculative capital deployments. The report translates the headline growth rate into probabilistic investment buckets—where to allocate R&D, where to run pilots (e.g., additive manufacturing, sensor integration) and where to defer.
Bike Helmet [Cycling Helmet] Market -
Portfolio optimization: As consumer expectations shift toward safety, comfort and sustainability, firms must choose between premiumization, broad-market coverage, or targeted niche leadership. Our frameworks help balance ROIC against market access timing.
Bike Helmet [Cycling Helmet] Market -
Regulatory & compliance planning: 2026 saw multiple high-profile recalls from U.S. authorities. The implications for QA protocols, supplier contracts and liability provisioning are non-trivial; the report provides a prioritized compliance playbook for entering or expanding within regulated markets.
-
Supply-chain and manufacturing strategy: The business case for nearshoring, micro-factory pilots and additive manufacturing is now quantifiable. Our modelling shows where localized production maximizes speed-to-market and where scale economies favor centralized facilities.
Market dynamics shaping 2026 and beyond
The market’s macro trajectory is defined by three overlapping forces: technology-driven differentiation, regulatory tightening, and shifting end-user behaviors. On technology, rotational-impact systems (several proprietary implementations) and new materials continue to be the primary vectors for premium differentiation. Additive manufacturing and AI-enabled fit solutions are transitioning from proof-of-concept to early commercial deployments; one notable micro-factory operator began commercial production in the United States in 2025 and has expanded product lines in 2026.
Regulatory activity intensified in 2026 with a series of recalls in the U.S. market triggered by failures against mandatory impact attenuation, positional stability and labeling requirements. These events increased the reputational and financial stakes of non-compliance. For market entrants and incumbents alike, the combination of stricter enforcement and consumer litigation risk requires immediate action on testing, traceability and documentation.
Finally, end-user demand is fragmenting. Performance-oriented segments remain focused on weight, aerodynamics and ventilation; urban and micromobility users prioritize comfort, visibility and sustainability; and family/kids segments emphasize certification and ease-of-use. These divergent priorities mean a single-product strategy rarely captures maximum value; segmentation-aligned product and channel strategies are required.
Competitive landscape — tactical read
-
Established performance-focused suppliers continue to command brand premium and distribution reach. Several European and U.S. incumbents are reinforcing their portfolios with rotational-impact and lightweight solutions while leveraging long-term sponsorships and pro-team partnerships to validate product claims.
-
Innovators in manufacturing and fit are emerging. Additive-manufacturing entrants that offer custom-fit models are commercializing at scale through localized production cells—an option that materially shortens lead times and enables premium pricing for personalization.
-
Sustainability and design awards are becoming credible differentiators in urban segments. Brands that can demonstrate lifecycle improvements and credible certifications are gaining visibility with municipal and corporate fleet programs.
-
Market structure is best described as moderately concentrated: leading firms capture a sizeable portion of global supply, but mid-market brands and regional specialists create a dynamic competitive field where innovation and channel execution can rapidly change standing.
Profiles & strategic implications of core players
-
European performance manufacturers: These firms maintain credibility through a broad helmet range across road, MTB, gravel and urban categories and continue to invest in rotational-impact systems and premium materials. Their playbook favors R&D-led differentiation and pro-team affiliations to drive aspirational demand.
-
North American specialists: Several U.S.-based suppliers combine aero and performance engineering with strong retail and e-commerce channels. Their strategy emphasizes rapid product refresh cycles and proprietary safety systems that are positioned for premium margins.
-
Innovative entrants: Companies commercializing 3D-printed, custom-fit helmets and operating micro-factories are proving the business case for localized, on-demand manufacturing for high-margin segments. These players are important acquisition targets for incumbents seeking to add personalization and speed-to-market capabilities.
-
Value and OEM suppliers: Regional manufacturers with green-design credentials and competitive pricing continue to serve urban and fleet segments. Their success will hinge on meeting evolving certification requirements and demonstrating traceability within complex supply chains.
Practical contents you will find in the full report
-
Comprehensive market model: historical (2020–2025) and forecast (2026–2032) revenue build with sensitivity scenarios and breakpoints tied to participation, pricing and channel shifts.
-
Demand-driver decomposition: actionable analytics linking participation rates, bicycle sales, micromobility programs and helmet replacement cycles to short- and medium-term market outcomes.
-
Regulatory-impact matrices: prioritized checklist for U.S., EU and major APAC jurisdictions covering certification, recall exposure and labeling best practices.
-
Technology adoption scenarios: timelines and economic models for rotational-impact systems, additive manufacturing, integrated electronics (sensors, comms) and sustainable-material substitution.
-
Channel & pricing playbooks: margin and channel-mix optimization templates for D2C, specialty retail, OEM partnerships and fleet procurement.
-
Manufacturing and supply-chain toolkit: micro-factory business-case models, supplier qualification scorecards and inventory-risk hedging strategies.
-
Competitive benchmarking and M&A screen: qualitative and quantitative filters to identify attractive acquisition targets and partnership candidates.
-
Operational checklists and launch templates: ready-to-use documents for product validation, pilot programs and market entry sequences.
Actionable 2026 playbook — five immediate priorities
-
Harden compliance and QA: Post-2026 recall activity makes enhanced testing, third-party verification and traceability the first-line defense. Allocate 2026 CAPEX/OPEX to close gaps in certification and labeling workflows.
-
Pilot localized manufacturing for personalization: Run a controlled micro-factory or partnership pilot focused on high-margin, customizable helmets to validate price elasticity and lead-time benefits.
-
Prioritize safety-tech investments that scale: Invest selectively in rotational-impact and fit technology that can be integrated across models; prioritize systems with independent test validation and clear user benefit stories.
-
Segment-tailored channel strategies: Rebalance channel investments—double down on specialty and D2C for premium models while optimizing low-cost channels for volume urban lines. Use targeted pilots to validate performance before scaling.
-
Scenario-based inventory and supplier planning: Given recall and regulatory risk, maintain flexible inventory buffers and qualify secondary suppliers for critical components to avoid single-point failures.
How to use this research to accelerate outcomes
This study is constructed as a decision-support toolkit—not an academic exercise. It includes live models (editable), trade-off analyses, and playbooks ready for immediate executive review. If you are sizing investments, negotiating supplier contracts, preparing an M&A pitch, or drafting a compliance remediation plan for 2026, the full dataset and annexes will provide the granular inputs you need to translate strategy into executable 90–180 day plans.
Methodology & scope
Base year: 2025. Forecast horizon: 2026–2032. Currency and unit: USD, Million. The report synthesizes primary interviews, proprietary sales and channel data, public company disclosures, certification agency records and in-market pricing observations. Scenario modelling incorporates participation elasticity, price/mix shifts and technology adoption curves.
Next steps
The narrative above is designed as a strategic preview: it demonstrates the depth of our analysis and the practical value the full report delivers, while reserving detailed segment-level forecasts, regional splits and the granular company share tables for the full report and interactive dashboards. For teams making 2026 product, manufacturing or M&A decisions, the complete dataset and playbooks are available through the PW Consulting release portal—where you will also find downloadable models, annexes and a tailored briefing package for executive leadership.
For detailed analysis of this topic, please visit the official page: Bike Helmet [Cycling Helmet] Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com