

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Peptone Market to Reach USD 366.1M by 2032 at a 4.7% CAGR

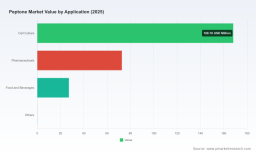
Peptone Market — 2026 Strategic Preview
As firms enter 2026 with stretched supply chains, heightened regulatory scrutiny and renewed investment in biologics and food safety, the peptone market is at an inflection point. This strategic preview, prepared by PW Consulting’s industry practice, distills the practical implications of our full Peptone Market research (base year 2025) for executive decision-making. It demonstrates why disciplined portfolio choices, supply-risk management and targeted commercialization moves will determine winners over the remainder of the decade — while intentionally withholding proprietary segment-level tables and regional splits to encourage direct engagement with the full report.
Peptone Market
Market snapshot — what the headline numbers tell you
-
The peptone market has expanded steadily over the past half-decade, rising from around USD 192.2 Million in 2020 to USD 268.0 Million in the 2025 base year.
Peptone Market -
Our forecast (2026–2032) assumes a mid-single-digit trajectory, with a compound annual growth rate (CAGR) of 4.7% through 2032, reaching an overall market size near USD 366.1 Million by 2032.
Peptone Market -
Market concentration is material: the top 3 suppliers represent roughly 62.5% of market value, and the top 5 capture about 78.3%, indicating meaningful scale advantages for incumbent manufacturers.
Why these metrics matter for 2026 strategic choices
-
Steady, predictable topline expansion (CAGR ~4.7%) reduces the macro growth risk for upstream suppliers, but does not eliminate margin pressure created by raw material volatility or regulatory-driven capacity shocks. Companies should plan for growth but optimize capital allocation for resilience rather than pure scale.
-
High concentration amplifies the impact of strategic moves by market leaders — new product introductions, validated assays, or prioritized supply agreements can rapidly reset commercial dynamics. Smaller players must choose either differentiation or partnership to avoid margin erosion.
-
The forecast cadence supports multi-year capacity and R&D investments, but firms must sequence investments to align with regulatory lead times, especially for GMP-grade peptones used in biopharma and for validated matrices used in food safety testing.
Market dynamics — forces shaping supply and demand
-
Raw material and supply-side volatility: Cost swings in feedstock and animal-derived inputs continue to be a gating factor in price-sensitive segments. In emerging markets, adoption of higher-cost specialty peptones is constrained by input-price pressure; producers need hedging strategies and alternative input qualification paths to protect margins.
-
Biosecurity and disease impact: Recent livestock disease activity has had tangible supply implications. Between January 2024 and May 2025, WOAH reported approximately 16.24 million poultry cases and around 148.68 million poultry losses linked to avian influenza — an event that has constrained animal-sourced raw material availability and tightened lead times for select producers.
-
Regulatory tightening and validation demands: Increasing biosecurity rules and elevated validation expectations for molecular detection and culture media are shortening the commercial runway for inferior product lines; validated offerings (e.g., peptone-based matrices that pass recognized validation programs) gain accelerated adoption in regulated end-markets.
-
Demand-side trends: Growth in cell culture, bioprocessing and food-safety testing are the primary growth engines. Specialty yeast- and plant-derived peptones are being positioned as substitutes where animal-sourced inputs are constrained or restricted by regulation, creating pockets of premium pricing and R&D focus.
Competitive landscape — how incumbents and challengers are positioning
-
Merck KGaA (MilliporeSigma) — leveraging a broad life-science channel, Merck focuses on high-spec peptones for microbiological media and biopharma, using certification and integration with downstream reagents to defend premium positions.
-
Thermo Fisher Scientific — through the Gibco portfolio, Thermo Fisher competes on brand trust and comprehensive media systems, emphasizing reproducibility for cell culture and fermentation customers.
-
HiMedia Laboratories — an agile regional player that uses trade-show presence and diagnostics-focused portfolios to defend share in clinical and food microbiology segments.
-
Solabia Group and Organotechnie — both European producers are investing in plant- and animal-derived alternatives and are active in scientific forums to accelerate adoption of non-animal peptones in fermentation and diagnostics.
-
Kerry Group, Angel Yeast, Procelys (Lesaffre) and Tatua — these firms pursue differentiated ingredient strategies (plant/yeast/dairy) for food, beverage and biotech customers, combining taste/nutrition knowledge with fermentation expertise.
-
Neogen, CONDALAB, Hardy Diagnostics, MP Biomedical, Titan Biotech and selected Chinese producers — these participants compete on cost, localized distribution and test-validated media for food safety and clinical labs.
-
Strategic implication: incumbents guard premium channels through validation and regulatory alignment; challengers win by targeting niche specification gaps or by cost leadership in local markets.
Recent industry moves that matter for strategy
-
Organotechnie’s 2026 product catalog (Oct 2025) signals an expanded push toward biotech-grade peptones and new formulations targeted at fermentation specialists.
-
Solabia’s visibility at RAFT®16 (Nov 2025) reinforces a go-to-market emphasis on plant-derived peptones and partnership-building with fermentation users.
-
Neogen’s MicroVal validation (Dec 2025) for molecular assays used with peptone-based media materially shortens buyer qualification timelines in food-safety laboratories.
-
HiMedia’s MEDICA 2025 participation (May 2025) underscores continued emphasis on diagnostics-focused channels and clinical lab procurement.
What’s in the full PW Consulting report — practical, executable deliverables
-
Top-down and bottoms-up market sizing with scenario-based forecasts (2026–2032) and sensitivity analysis tied to raw-material and regulatory shocks.
-
Competitive scorecards and validated supplier profiles that map capabilities (GMP, validation history, channel strength, geographic footprints) to end-market demand characteristics.
-
Supply-chain risk matrix including input concentration, disease-risk overlays and mitigation playbooks (alternative feed qualification, dual-sourcing, long-term offtake strategies).
-
Go-to-market playbooks for incumbents and challengers: pricing bands, validation pathways, distributor vs direct channels, and technical-service investments to accelerate adoption.
-
M&A and partnership screening framework identifying bolt-on targets, vertical integration scenarios, and JV structures — with quantifiable return thresholds and integration risk scoring.
-
Actionable KPIs, a commercialization roadmap for specialty peptones (biopharma-grade, validated matrices, plant-derived replacements), and a prioritized investment heatmap for 12-, 24- and 36-month horizons.
How to use this intelligence in 2026 — recommended executive moves
-
Procurement: implement a three-tier sourcing strategy (primary validated sources, regional backups, and qualified alternative raw-material suppliers). Prioritize validated suppliers in regulated end-markets to reduce qualification cycles.
-
Product strategy: accelerate development and commercialization of non-animal peptones for customers seeking biosecurity resiliency; simultaneously protect high-margin biopharma formulations through certifications and contract guarantees.
-
Commercial: align sales incentives to validated product adoption (shorter trials, bundled validation support), and invest in targeted technical support for high-value customers (cell therapy, vaccine manufacturing, and national food labs).
-
Corporate development: screen acquisition targets that deliver immediate channel access, validation credentials or feedstock diversification; prioritize deals that materially improve CR3 defensibility or reduce supplier risk exposure.
-
Risk management: model downside scenarios tied to raw-material shocks and avian/swine disease outbreaks; preserve cash for opportunistic capacity build when prices normalize.
Final note — why you should access the full study
This preview provides the strategic contours you need to prioritize decisions in 2026: the market is growing, concentrated and subject to episodic supply shocks and evolving regulatory demands. The full PW Consulting Peptone Market report contains the granular segmentation, regional breakdowns, pricing curves, supplier scorecards and Excel-ready forecast models that operational teams require to execute these recommendations. If your plan for 2026 includes capacity investments, M&A targets, or a revised GTM for specialty peptones, the full dataset and playbooks are indispensable.
Contact PW Consulting or visit our report page to access the underlying tables, validated supplier matrices and scenario models that support the executive actions summarized here.
For detailed analysis of this topic, please visit the official page: Peptone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com