

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Forklift Trucks Market to Hit USD 125.8B by 2032, 6.8% CAGR — Asia Pacific Leads

Forklift Trucks Market — 2026 Strategic Outlook (PW Consulting)
Why this research matters for 2026 decisions
The forklift trucks market is entering a phase of structural expansion and strategic re‑positioning. After steady recovery through the early 2020s, the market reached an important inflection point in our base year (2025) and is projected to continue expanding through our forecast horizon (2026–2032) at a compound annual growth rate (CAGR) of 6.8%. In absolute terms, the global market has grown significantly since 2020 and — under our central scenario — is on a path to materially larger scale by the end of the forecast period.
Forklift Trucks Market
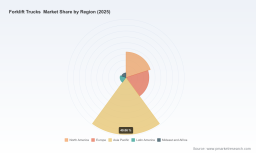
For leadership teams planning capital allocation, product roadmaps, M&A activity, or dealer-network investments in 2026, these directional metrics matter for two reasons. First, sustained mid‑single‑digit CAGR signals that investments in electrification, automation and aftermarket services are not one‑off plays but foundation stones for medium‑term competitiveness. Second, market concentration is meaningful: the leading firms account for the majority of market share, creating both barrier effects and targeted opportunities for differentiating plays in niches, services and regional partner strategies.
Forklift Trucks Market
Market forces shaping strategy in 2026
- Electrification is no longer experimental. Declining battery costs are changing procurement math. Recent industry data shows continued downward pressure on lithium‑ion battery pack prices, improving total cost of ownership for electric fleets and accelerating fleet replacement cycles in high‑utilization environments.
- Automation and intralogistics integration are scaling up. System‑level projects, from semi‑automated pallet flows to fully autonomous reach truck deployments, are moving out of pilot labs into production — particularly where labor cost dynamics and throughput demands justify higher upfront investment.
- Sustainability and regulatory signaling matter. Environmental performance is becoming a procurement filter for large corporate buyers, and leading OEMs are using certified sustainability credentials as commercial differentiators.
- Aftermarket and service offerings are strategic profit pools. As fleets electrify and equipment becomes software‑defined, recurring revenue from service, telematics and parts is a primary lever for margin expansion and customer lock‑in.
- Supply‑chain dynamics remain a major risk/advantage source. Raw material price moves, localized automation projects and regional manufacturing footprints influence cost curves and delivery lead times — which in turn shape contracting and inventory strategies.
What the PW Consulting Forklift Trucks report delivers (practical modules)
- Market sizing and robust scenario models (historical baseline 2020–2025 with forward scenarios through 2032), including interactive sensitivity tools to stress test price, demand and policy variables.
- Technology and cost‑curve analysis that links battery pack price trajectories to total cost of ownership across powertrain options, with supply‑chain levers that materially shift economics.
- Competitive benchmarking and capability matrices for incumbent OEMs and challengers — covering product portfolios, service networks, digital capabilities and go‑to‑market strengths.
- Deal guidance: screening criteria for tuck‑ins vs platform deals, high‑conviction acquisition targets and valuation themes for 2026 M&A activity.
- Commercial playbooks for fleet electrification, automation adoption, dealer optimization and aftermarket monetization — with implementation roadmaps and 100+ prioritized tactical initiatives.
- Risk & contingency playbooks: practical mitigations for supply disruptions, raw material volatility and shifting regulatory regimes.
- Executive dashboards and downloadable Excel models suitable for CFO, Head of Operations and Corporate Development teams.
Competitive landscape — who matters and why
The market is led by a cluster of global OEMs and regionally strong manufacturers. The competitive dynamics combine scale advantages, deep dealer networks, and accelerating capability builds in software and automation. Key participants to monitor include:
Forklift Trucks Market
- Toyota Material Handling — A global incumbent with a broad product portfolio and an extensive dealer and service footprint. Its strength lies in end‑to‑end offerings that combine reliability with comprehensive aftermarket capabilities.
- KION Group AG — A European heavyweight that has been intensifying its automation and system integration efforts. KION’s positive order intake at the start of 2026 and major automation projects in Central Europe underscore its focus on high‑value, integrated intralogistics solutions.
- Jungheinrich AG — A brand leveraging design and sustainability credentials to differentiate. Recent industry awards and recognized sustainability performance are being used to strengthen commercial positioning, particularly with large, sustainability‑focused buyers.
- Crown Equipment Corporation — Known for engineering innovation and strong warehouse solutions; continues to invest in operational efficiency and customer‑centric product enhancements.
- Hyster‑Yale Materials Handling, Inc. — A diversified portfolio player with depth in heavy‑duty applications and a strategic emphasis on aftermarket and rental channels.
- Raymond Corporation — Focused on high‑throughput warehouse systems and integrated telematics; strong relevance for operations targeting improved slotting and flow efficiency.
- CLARK Material Handling Company — Recent organizational investments, including the opening of a new global headquarters and leadership promotions, signal a renewed focus on global coverage and dealer strength.
- Komatsu Forklift U.S.A. — Leverages heavy‑equipment heritage to serve construction and mining adjacent fleets, with cross‑selling opportunities into larger equipment ecosystems.
Recent strategic signals — what to read into them
- KION’s strong order intake in early 2026 indicates resilient demand pockets and validates automation investment strategies in Europe.
- Jungheinrich’s design awards and sustainability recognitions are more than branding wins: they materially support premium positioning in large corporate procurement processes where ESG (environmental, social and governance) credentials influence supplier selection.
- CLARK’s corporate investments and sales leadership moves suggest increased emphasis on global dealer performance and channel execution — a reminder that distribution and local support remain decisive in customer selection.
- Wider industry context: lithium‑ion battery pack costs have continued to decline, materially improving the economics of electric forklifts relative to legacy powertrains — a cost inflection that accelerates buyer conversion when paired with supportive service ecosystems.
Strategic implications and recommended 2026 actions
- Shorten the electrification decision cycle. With battery costs trending down, prioritize pilot-to-scale pathways that move the highest‑utilization assets to electric first. Capture learnings and standardize retrofit and recycling protocols now.
- Invest in software and telematics as a commercial differentiator. Data‑driven service plans, predictive maintenance and uptime SLAs unlock higher recurring revenues and improve customer retention.
- Treat automation as a systems business. Partner selectively with systems integrators and focus on packaged value propositions (hardware + software + financing) for high‑throughput warehouse customers.
- Re‑assess channel economics. In concentrated markets, dealer productivity and aftermarket reach are primary competitive moats — rewire incentives and KPIs to prioritize lifecycle value over new‑unit volume alone.
- Use concentration metrics to guide M&A. Market concentration at the top creates targeted opportunities for bolt‑on acquisitions that expand service footprints or add software capabilities without requiring scale to compete.
How to use this brief and where to find the full intelligence
This brief is designed as a strategic “teaser” — it summarizes the forces and decisions most relevant to executive teams planning for 2026. For procurement directors, corporate development teams, product leaders and operations executives, the full PW Consulting Forklift Trucks Market report provides the operational granularity you need: detailed segmentation by region, type and application, full-year-by-year forecast tables, downloadable models, competitor scorecards and scenario simulations. We intentionally withhold the granular segmentation tables and proprietary Excel models here to preserve the value of the full research package.
If your 2026 roadmap includes fleet transition, automation investments, dealer network restructuring or M&A, this research is designed to be immediately actionable — providing both the strategic narrative and the tactical toolsets to accelerate decision cycles.
Next step
Contact PW Consulting to request an executive summary with sample model outputs and to discuss a bespoke briefing that translates these insights into a prioritized 12–18 month action plan for your organization.
For detailed analysis of this topic, please visit the official page: Forklift Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com