

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Household Air Purifiers Market hits USD 6.3B in 2025; 8.15% CAGR

Household Air Purifiers Market: Strategic Imperatives for 2026
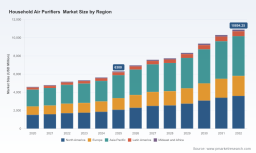
Executive teams planning 2026 product roadmaps, go-to-market pivots, or M&A playbooks face a market that is both expanding and structurally changing. Our new PW Consulting Household Air Purifiers Market study (base year 2025; forecast 2026–2032) quantifies that trajectory and translates it into actionable options. In short: the global household air purifier market has moved from a solid recovery phase into a sustained growth cycle—driven by regulation, episodic pollution events, evolving consumer expectations around safety and connectivity, and material- and supply-chain pressures. The market expanded meaningfully from a 2020 baseline and, using our core model, reaches a markedly higher level by 2032 under a central-case compound annual growth rate (CAGR) of 8.15%.
Household Air Purifiers Market
Market snapshot: magnitude, momentum, and concentration
-
Scale and momentum. Using 2025 as the analytical base year, the sector shows robust expansion versus 2020. Our central forecast through 2032 reflects compound growth consistent with the 8.15% CAGR noted above—creating an extended runway for incumbents and new entrants who can articulate clear value beyond simple filtration.
Household Air Purifiers Market -
Competitive concentration. The market is meaningfully consolidated at the top: the three largest global suppliers account for nearly half of industry revenue, while the top five approach three-fifths. That concentration creates both defensive pressures for category leaders and opportunity windows for focused challengers to win on niche specification, service, or channel strategy.
Household Air Purifiers Market -
Structural tailwinds. Policy interventions and episodic air quality crises—wildfires, urban pollution episodes, and increased attention to indoor air quality standards—are shifting the product mix and demand cadence toward smart, single-room, and clinically rated devices in residential settings.
Why 2026 is a strategic inflection point
-
Regulatory push. Recent policy moves—most notably the European Air Quality Directive passed in September 2025—explicitly broaden the expectation that residential-level interventions will be part of urban air quality responses. For suppliers, this changes the buyer from purely consumer to municipal-influenced household procurement in some markets, elevating compliance and evidence of effectiveness.
-
Safety and trust are now commercial differentiators. Research published by national laboratories in late 2025 on chemical by-products from certain air-cleaning technologies has accelerated demand for low-emissions, single-room designs and for transparent testing protocols. Product safety incidents, such as the recall of a consumer model in early 2026, have also heightened retailer and regulator scrutiny—raising the cost of quality failures and the market value of demonstrable safety systems.
-
Event-driven demand volatility. Wildfire seasons and episodic pollution spikes continue to create short windows of intense demand in retail channels. Limited availability of high-quality units during such events underscores the importance of flexible manufacturing footprints and prioritized distribution strategies.
Competitive landscape: who matters and why
The marketplace is a mix of legacy home-electronics brands, specialist filtration manufacturers, and agile direct-to-consumer challengers. Key players we profile in the report include:
-
Coway (Seoul): a brand known for whole-home consumer trust and its Mega series with True HEPA filtration.
-
Levoit (Anaheim): active in rapid product introductions and regional launches—recently expanded product footprints with smart Core and Sprout series.
-
Medify Air (Boca Raton): positioned on high-MERV/H13 HEPA capability for larger rooms, aiming at health-focused buyers.
-
Winix (Seoul): combines HEPA filtration with proprietary plasma-wave technologies in its consumer lineup.
-
Blueair (Stockholm): a design-forward brand with True HEPA and signature models targeting premium segments.
-
Dyson (Singapore HQ): integrates advanced air-quality sensing, multi-functionality, and formaldehyde removal into premium units.
-
Austin Air Systems and Alen Corporation (U.S.-based): target clinical-grade filtration and higher-end channel placements.
-
Honeywell (Charlotte): leverages strong channel relationships and recognizable brand trust in tabletop categories.
-
Airova, Inc. (Newark): a DTC player whose 2026 product recall underscores how manufacturing and safety lapses can rapidly erode market placements.
For each company we analyze market positioning, product architecture, route-to-market, and implied vulnerabilities—insights designed to shape competitor response plans, pricing strategies, and acquisition screens.
Product and innovation imperatives for 2026
-
Safety-by-design and verifiable testing. Post-2025 laboratory findings and high-profile recalls mean brands must prioritize third-party emissions testing, thermal safety certifications, and transparent performance reporting to remain competitive with institutional purchasers and risk-averse consumers.
-
Focus on single-room solutions as a product category. Research and market response trends are pushing demand toward portable, efficient single-room units—especially in regions affected by intermittent smoke or regulatory-driven residential programs.
-
Integration of sensing and services. Products that combine validated air-quality sensing, firmware update pathways, and subscription-based filter replacement ecosystems will capture greater lifetime value.
-
Material optimization and decarbonization. Life-cycle analysis work has flagged ABS plastics as a prominent contributor to product GWP—responding with alternative materials or recycling strategies can be a differentiator for ESG-conscious buyers.
Channels, pricing, and distribution dynamics
-
Retailers and e-commerce coexist—but fulfillment resilience matters. During pollution episodes, inventory allocation rules and logistics speed determine share gains. Premium brands that lock in prioritized supply vanish the most risk.
-
Institutional demand is emerging. With regulatory frameworks nudging residential upgrades, procurement opportunities now exist beyond traditional consumer spend—municipal programs, public-health initiatives, and healthcare-adjacent buyers should be on commercial radars.
-
Service monetization is underleveraged. Many brands offer filter subscriptions, but few have a fully integrated service-led pricing model. There is room to convert product buyers into recurring revenue streams through warranty extensions, certified installation, and air-quality monitoring subscriptions.
Supply chain, materials, and ESG risk
-
Materials and manufacturing footprint. Sourcing constraints for high-efficiency filter media and plastics can create bottlenecks. Manufacturers should model scenarios that account for raw-material price volatility and prioritize dual-sourcing for critical components.
-
Environmental impact and circularity. The sector’s life-cycle studies show plastics and disposables drive most of the GWP footprint. Executives should evaluate design-for-repair, takeback programs, and higher-recyclability materials as both regulatory risk mitigants and market differentiators.
-
Recall and liability preparedness. The marketplace has demonstrated low tolerance for product safety failures. Strengthening post-market surveillance, component traceability, and crisis communications will materially de-risk brand value.
What PW Consulting’s full report delivers (actionable components)
-
A validated market-sizing model (base year 2025) and scenario forecasts through 2032 that connect macro drivers to addressable demand by product architecture and buyer type.
-
Competitive deep dives on the category’s leading firms, including product-spec comparisons, channel footprints, pricing archetypes, and threat/opportunity maps for each competitor.
-
Regulatory and standards matrix highlighting recent policy changes, laboratory testing expectations, and certification pathways required by major trading blocs.
-
Operational playbooks for capacity planning and differential inventory allocation to capture event-driven surges without overexposing balance sheets.
-
ESG and lifecycle impact analysis, including targeted interventions to reduce the product footprint and capture value from circular-economy initiatives.
-
M&A and partnership screens calibrated to identify targets that accelerate entry into high-opportunity niches (e.g., clinically rated units, air-quality services, or regional distribution hubs).
How senior leaders should use the report in 2026
-
CEOs: use the scenario forecasts and concentration analysis to determine whether to pursue defensive scale, bolt-on acquisitions, or laser-focused category plays.
-
Product chiefs: prioritize safety certifications, sensor validation, and modularity that support both single-room and integrated home solutions.
-
Commercial heads: re-weight channel investments toward faster-fulfillment partners and design programs for municipal or institution-led residential procurement.
-
Operations and procurement: implement dual-sourcing for critical components, and quantify the cost/benefit of relocating partial production to reduce time-to-shelf during episodic demand spikes.
Final perspective: opportunity mapped to execution
The household air purifier market’s growth trajectory over the next decade is clear: structural demand, regulatory tailwinds, and evolving safety expectations create significant upside for companies that execute on product integrity, supply resilience, and smart monetization of post-sale services. However, the rising cost of failure—whether through safety incidents, non-compliance with new directives, or unsustainable product footprints—raises the bar for market participation. Our study gives leadership teams the market sizing, competitor intelligence, regulatory roadmap, and operational playbooks needed to make high-confidence strategic choices in 2026.
To access the full dataset, detailed segmentation tables, granular regional and application breakdowns, and proprietary scenario models—information we intentionally summarize here to preserve the strategic advantage—please visit the PW Consulting report page for the Household Air Purifiers Market.
For detailed analysis of this topic, please visit the official page: Household Air Purifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com