

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PTFE CCL Market to Reach USD 3,230M by 2032 at 7.8% CAGR

PTFE CCL Market Strategic Briefing — A 2026 Decision Playbook
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused briefing on the PTFE copper-clad laminate (PTFE CCL) market that sharpens 2026 commercial decisions. The market we track has grown steadily from its 2020 base and—on the basis of our proprietary model—reached approximately USD 1,920 Million in the 2025 base year and is projected to approach USD 3,230 Million by 2032, reflecting a compound annual growth rate (CAGR) of roughly 7.8% across the 2026–2032 forecast period. This briefing is designed as a “trailer”: it exposes the analytical spine and strategic implications while intentionally withholding the granular segmented datapoints that drive transaction-level choices, thereby directing executives to the full study for implementation-grade figures.
PTFE CCL Market
Why this study matters for 2026 corporate strategy
- Timing capital commitments: the market’s mid-single-digit-to-high-single-digit CAGR implies material demand acceleration in high-frequency and mmWave applications—decisions on capex and capacity must be synchronized to avoid either stranded assets or missed growth.
- Product roadmaps under pressure: 5G densification, automotive radar evolution and aerospace RF performance are compressing product lifecycles. Product investments that reduce dielectric loss and improve manufacturing yield will determine commercial winners.
- Supply-chain and regulatory exposure: recent export-control shifts and raw-material trade actions have introduced non-linear risk to electronic-materials supply. Companies must translate that risk into procurement, inventory and compliance playbooks in 2026.
- M&A and partnership windows: pockets of concentration exist among incumbent suppliers. Strategic alliances, distribution partnerships, and targeted acquisitions are effective levers to secure market access without the lead time of greenfield expansions.
Data-driven thematic drivers
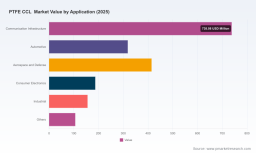
Our quantitative work synthesizes demand drivers across communications infrastructure, automotive, aerospace & defense and industrial electronics. Two structural forces dominate:
PTFE CCL Market
- Electromagnetic performance requirements. As frequency bands migrate into mmWave and as automotive radar architects push to 77 GHz and beyond, substrate materials must exhibit consistently low dielectric constant (Dk) and dissipation factor (Df) while maintaining manufacturability at scale. Suppliers that can demonstrably reduce loss at target frequencies command technical premium.
- Scale and cost dynamics. The market’s trajectory—reflected in the ~7.8% CAGR—creates a bifurcated imperative: sustain advanced-performance product lines for high-margin, low-volume platforms (aerospace, defense) while optimizing cost-to-serve for higher-volume telecom and automotive programs. Operational excellence in lamination, copper bonding and dimensional control is the differentiator.
Between these forces sit cross-cutting enablers: material innovations (ceramic-fill and engineered PTFE composites), substrate architectures (glass-reinforced vs. glass-free), and manufacturing investment in capacity and yield improvement. Our model captures their interplay and the sensitivity of revenue to adoption rates in key end-markets.
PTFE CCL Market
Competitive landscape — who matters and why
The PTFE CCL ecosystem is shaped by a mix of global incumbents and specialized regional players. Market concentration metrics indicate a moderately consolidated market structure, with the largest three suppliers accounting for a meaningful share of reported supply and the top five increasing that footprint—this creates both predictable supply channels and competitive friction for market entrants.
- Rogers Corporation (Chandler, AZ): A technology leader in ceramic-filled PTFE composites and high-frequency laminates, with products tailored for RF/microwave and 5G. Its recent capacity expansion in Europe signals deliberate positioning to serve advanced laminate demand and to shorten lead times for key customers.
- AGC Inc. (Tokyo): A diversified materials player delivering PTFE composites and CCL through established brands. Recent distribution-network extensions in North America position AGC to increase customer intimacy and accelerate response to design-win opportunities.
- Chukoh Chemical Industries (Osaka): Focused on precision-controlled PTFE CCLs with the tight dimensional tolerances needed for high-frequency comms. Their portfolio is relevant where substrate homogeneity drives RF consistency.
- Shengyi Technology (Dongguan): A high-volume, technically capable supplier advancing partnerships and R&D collaborations to broaden product reach into antenna and mmWave segments.
- Doosan Electro-Materials (Seoul), Taiflex (Kaohsiung), and Nanya Plastics (Taipei): Regional specialists with targeted offerings for automotive radar, mmWave antenna substrates and telecom base-station laminates; each brings distinct manufacturing competencies and local-market channels.
Recent strategic moves matter: distribution partnerships, strategic R&D collaborations and capacity buildouts (documented across 2025 and 2026) reflect both commercial assertiveness and hedging against cyclical swings. For incumbents, the imperative is to convert technology leadership into reliable supply and to protect design wins through supply assurance and services; for challengers, the path is niche specialization, distribution alliances and selective capacity commitments.
Regulatory and supply-chain dynamics — a 2026 risk map
Regulation and raw-material policy are no longer background noise; they are primary drivers of strategic risk in PTFE CCL value chains. Since late 2024, multiple policy actions have altered the operating landscape:
- Export control tightening in the U.S., including updates to EAR and redefinitions under ITAR/USML, which affect how advanced electronic materials are categorized and traded.
- Sporadic policy shifts from other major jurisdictions—including temporary suspensions or revisions of dual-use control measures—introduce uncertainty for cross-border flows.
- Targeted export controls on key minerals by producing countries have amplified the materials-cost and sourcing-risk profile for many advanced substrates.
For executives, the tactical implications are immediate: establish compliant trade frameworks, implement pre-vetting of critical suppliers, develop multi-geography sourcing, and model inventory hedges under different policy scenarios. Failure to embed regulatory scenarios into S&OP can lead to costly program delays and contract penalties in 2026.
What the full PW Consulting report delivers (operational highlights)
Our full study is structured to move teams from insight to execution. Key deliverables include:
- Transparent market model with baseline and three scenario forecasts (central, upside, downside) across 2026–2032, alongside sensitivity analyses for demand shocks and regulatory interventions.
- Supplier intelligence dossiers and capability scorecards that evaluate technology, capacity, geographic exposure, and compliance readiness—enabling commercial teams to prioritize partners.
- Product-application mapping and technology adoption curves that link substrate choices to RF performance and cost outcomes at target frequencies (including mmWave use cases).
- Manufacturing and CAPEX playbooks, with build-vs-buy decision frameworks, ramp schedules, and unit-cost trajectories tied to throughput and yield assumptions.
- Commercial plays and pricing models for negotiation teams, including customer segmentation, warranty-risk allocation, and long-term offtake structuring.
- M&A and partnership decision trees: diligence checklists, valuation sensitivities, and integration risk matrices tailored to PTFE CCL propositions.
- Practical checklists for compliance, logistics, and inventory risk mitigation—grounded in the latest export-control developments and materials-trade dynamics.
How to use this intelligence in 2026 — recommended actions
- Model multiple demand scenarios into your 2026 capacity plan. Avoid binary “scale or wait” choices; instead, create modular capacity commitments with trigger-based escalation clauses.
- Prioritize supplier scorecards in RFPs. Favor partners that combine technical fit with demonstrable compliance processes and multi-region production footprints.
- Lock down strategic raw-material agreements or financial hedges for critical minerals that feed PTFE and copper supply chains to reduce price and availability volatility.
- Invest in product differentiation where electromagnetic performance confers a clear customer ROI—this preserves margin even as volumes scale.
- Use targeted M&A as a fast-track to capability—focus on players that offer either proprietary material science or localized capacity in strategically important production corridors.
A final note — why download the full study
This briefing demonstrates the strategic contours and the levers that will determine competitive outcomes in PTFE CCL through 2026 and beyond. To translate strategic intent into executable plans you will need the granular segmentation, vendor-level benchmarking, contract-ready scenario models and unit-cost schedules contained only in the full PW Consulting report. Those datasets—paired with our bespoke implementation templates—are what enable board-level decisions that are defensible under stress tests and compliant with evolving trade regimes.
For teams preparing budgets, supplier negotiations, or M&A diligence in 2026, this report is not academic—it is a decision support system. Access the full study to obtain the detailed regional, type and application splits, the supplier scorecards and the model files that will convert this strategic briefing into operational outcomes.
For detailed analysis of this topic, please visit the official page: PTFE CCL Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com