

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Motorcycle & Scooter Market to Reach USD 362 Million by 2032

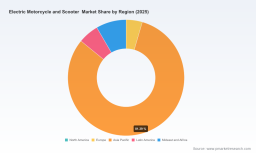
Electric Motorcycle and Scooter Market 2026 — Strategic Preview
As the Electric Motorcycle and Scooter market accelerates into a phase where scale, technology and regulation intersect, executives must reconcile near-term commercial choices with a multi-year structural transition. This preview, prepared by PW Consulting’s senior strategy team, synthesizes the macro trajectory, competitive dynamics and operational levers that will matter most to boardrooms and corporate development teams in 2026. It is designed as a high-signal “trailer”: we expose the strategic contours and show our analytical depth while intentionally reserving core granular splits and proprietary scenario outputs for the full report.
Electric Motorcycle and Scooter Market
Market snapshot: scale, rhythm and concentration
Between 2020 and 2025 the global E-motorcycle and scooter market expanded steadily, reflecting a shift in urban mobility preferences and accelerating electrification of two-wheeled transport. Measured in the report’s base year (2025), the market reached a clear inflection point, with aggregate industry revenues of USD 215.0 Million. Under our central forecast (2026–2032), the market proceeds on a compound annual growth rate (CAGR) of 12.5%, reaching USD 362.0 Million by 2032. That trajectory implies both sustained demand growth and a continued compression of unit economics as technologies and supply chains mature.
Electric Motorcycle and Scooter Market
Market concentration remains low-to-moderate. The combined sales share of the three largest firms is under 20%, and the top five account for less than a third of the market. For incumbents and new entrants alike, the implication is straightforward: national and segment-level scale advantages are possible, but global dominance is not yet locked in—opening window for focused regional plays, niche premium moves, and differentiated service models.
Electric Motorcycle and Scooter Market
Why 2026 is a strategic pivot year
-
Commercial models bifurcate faster than many boards expect. As battery cost declines and charging infrastructure densifies incrementally, total cost of ownership (TCO) converges between advanced electric two-wheelers and legacy ICE alternatives for urban use-cases. This convergence accelerates fleet adoption and urban substitution—but timing and local policy matter. 2026 is the year organizations should finalize which product-market plays receive scale investments vs. pilot budgets.
-
Safety and regulation reset product requirements. New testing protocols introduced for powered two-wheelers increase the engineering bar for active safety, junction scenarios and vulnerable road user (VRU) protection. Manufacturers who align product roadmaps to anticipated certification changes will avoid costly rework cycles and market access delays.
-
Supply-side inflection in battery economics. Lithium-ion pack costs for two-wheeled platforms have reached a materially lower threshold, improving vehicle economics and enabling higher margin product tiers (longer range, faster charging, integrated telematics). Firms that lock favorable cell supply and optimize pack BOM will secure asymmetric returns as volumes scale.
Competitive landscape — what the major players signal
-
Yadea (China) — With a strong urban commuting product set and a focus on integrated smart features, Yadea exemplifies the mass-market scale play. Its strategy centers on production efficiency, dealer density and incremental digital services to raise lifetime customer value.
-
NIU Technologies (China) — NIU’s emphasis on IoT-connected models and modular platforms positions it to capitalize on telematics-driven services (insurance, fleet monitoring, subscription). Their product cadence demonstrates that connectivity is shifting from a differentiator to a baseline requirement.
-
BMW Motorrad (Germany) and Vespa (Italy) — These legacy premium brands are driving a premiumization pathway for electric two-wheelers, emphasizing design, brand equity and urban lifestyle fit. Their presence illustrates the durability of brand-driven pricing power, particularly in affluent urban segments.
-
Zero Motorcycles and LiveWire (USA) — High-performance and lifestyle-focused electric motorcycles signal a separate demand pole: consumers willing to pay for performance, range and persona. LiveWire’s recent S4 Honcho launch and Zero’s continued investment in performance platforms stress the importance of differentiated engineering competence.
-
Major OEMs (Honda, Can-Am, others) — Incumbent OEMs are using scale, distribution and multi-category R&D budgets to introduce full-size and crossover electric models. Their strategic options include platform-sharing across vehicle categories, captive financing, and selective partnerships to accelerate charging/payment services.
Recent product activities—such as LiveWire’s Spring 2026 S4 Honcho rollout and NIU’s 2026 lineup showcase—confirm two concurrent market dynamics: aggressive product refresh cycles and segmentation into premium-performance vs mass-commuter propositions. Firms must choose between resource-intensive platform roadmaps or fast-follower specialization supported by superior go-to-market execution.
Technology and cost dynamics: the levers that decide winners
-
Battery and pack strategy. With pack costs meaningfully lower than in prior years, two tactical choices dominate: (a) offer higher-capability packs to capture premium margin; or (b) optimize to the lowest-cost, high-volume pack and compete on TCO. Both are viable—what matters is alignment to distribution channel and aftersales strategy.
-
Software and services. IoT and OTA capabilities are migrating from optional extras to table-stakes for fleet operators and rental schemes. Data-driven service offers (fleet telemetry, predictive maintenance, usage-based insurance) are the fastest route to recurring revenues and deeper customer lock-in.
-
Modularity and platform economics. Shared platforms across scooter/motorcycle variants compress time-to-market and reduce per-unit R&D. However, modularity requires upfront investment and supply-chain coordination; companies must evaluate the payback horizon under the market’s 12.5% CAGR backdrop.
Regulatory & safety dynamics: compliance as strategic advantage
Regulatory changes, particularly in safety testing protocols for powered two-wheelers, are not merely compliance tasks but strategic inflection points. The 2026 testing updates emphasize junction scenarios, higher-speed events, emergency steering support and VRU safety measures. These shifts increase the engineering scope for active safety systems and force earlier integration of sensor suites and control algorithms.
Companies that proactively design for these enhanced protocols will gain multiple advantages: faster market access in jurisdictions adopting the tests, reduced recall risk, and improved product appeal to safety-conscious consumers and fleet operators. Associations such as ACEM are backing these roadmaps, suggesting a convergence of regulator, industry and insurer incentives toward higher safety standards.
Operational risks and supply-chain priorities
-
Cell supply and BOM volatility. Securing differentiated battery chemistry or preferential cell allocations is a near-term performance lever; firms should negotiate multi-year offtakes and consider co-investment in local pack assembly to manage logistic risks.
-
Localization vs. globalization. Low market concentration and regional regulatory divergence mean distribution-centric plays can outperform a thin global footprint. Consider how manufacturing footprints and aftermarket capabilities align with prioritized markets.
-
Service and parts ecosystems. After-sales capabilities (fast replacement batteries, certified repair channels, software updates) materially influence residual values and brand loyalty. Investment in these networks is a lever to expand margins without relying solely on new-unit growth.
What the full PW Consulting report delivers (operational and strategic tools)
The complete report is structured to support decision-making across corporate strategy, product management and M&A teams. Highlights include:
- Comprehensive market model with historicals (2020–2025), base year alignment and scenario-based forecasts (2026–2032) that integrate macro adoption curves and policy shocks.
- Company dossiers and competitor scorecards covering product architecture, go-to-market, margin structure, and strategic options for each major player identified in this preview.
- Technology cost curves —including pack BOM sensitivity, powertrain architecture trade-offs, and TCO comparisons for target buyer personas.
- Regulatory impact assessment mapping the effect of new safety protocols and regional requirements on time-to-market and certification cost.
- Go-to-market playbooks for OEMs, fleet operators and startups (distribution models, subscription pricing, service rollouts, partnerships).
- Supply-chain risk matrix and recommended mitigation actions (supplier diversification, localization thresholds, strategic inventory).
- Investment and M&A screening framework identifying value-creation levers for buyers and target attributes for sellers.
Note: to preserve analytic integrity and commercial value for subscribers, the report intentionally withholds certain granular segmentation outputs in this public preview—such as specific regional/application shares and proprietary micro-forecasts. These are accessible in full through our report portal.
Action agenda for executives in 2026
-
Prioritize product-to-channel fit. Decide quickly whether to allocate capital toward premium, performance, or high-volume commuter lines; tailor distribution and aftersales accordingly.
-
Lock supply and test compliance. Secure cell and component supply contracts with clauses that mitigate material price swings and align engineering roadmaps with evolving safety protocols.
-
Monetize data. Deploy telematics and OTA features that enable service subscriptions and B2B fleet products—these convert marginal hardware gains into recurring revenue.
-
Run focused M&A screens. Target high-value capabilities (charging/payment platforms, regional distribution assets, battery-packs specialists) that accelerate route-to-scale without diluting core R&D.
Conclusion — from preview to action
The market’s projected path—growing from USD 215.0 Million in 2025 toward USD 362.0 Million by 2032 at a 12.5% CAGR—creates a platform for sustained investment and strategic repositioning. Yet the winners in 2026 will be the organizations that pair capital with focused choices: the right product architecture, the right distribution and a defensible technology/supply position. For companies that appreciate nuance, this is not a market of binary winners and losers but of repeatable strategic plays that can scale with disciplined execution.
To access the full datasets, granular segmentation, interactive scenario models and a downloadable strategy toolkit, please visit our report page. PW Consulting’s team is available for briefings and bespoke strategy sessions to translate these insights into executable 12–36 month roadmaps.
For detailed analysis of this topic, please visit the official page: Electric Motorcycle and Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com