

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: RTA Kitchen Cabinet Market to Grow at 5.67% CAGR (2026–2032)

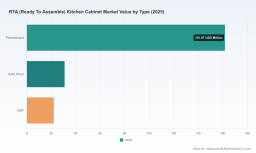
RTA Kitchen Cabinet Market — Strategic Outlook for 2026 Decision-Makers
As ready-to-assemble (RTA) kitchen cabinets continue to reshape the kitchen remodeling and new-build value chain, PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) provides a pragmatic, decision-grade view of what executives and investors must act on in 2026. The market shows steady expansion—growing from roughly USD 163 million in 2020 to about USD 215 million in 2025—and our forecasted trajectory pushes total revenues toward the mid-hundreds by 2032 under a baseline compound annual growth rate (CAGR) of 5.67% (USD, revenue in Million). That topline momentum, combined with a low three- and five-firm concentration (CR3 ≈ 24.6%, CR5 ≈ 26.2%), frames an industry that is expanding but highly fragmented—fertile ground for scale plays, channel innovation, and cross-border sourcing strategies.
RTA (Ready To Assemble) Kitchen Cabinet Market
Why this research matters for 2026 strategy
- Calibrating sourcing and tariff exposure: 2026 will be a turning point for procurement decisions as trade measures and tariff schedules continue to evolve. Buyers and manufacturers need clear, scenario-based cost models to lock in profitable SKU economics.
- Prioritizing product architectures: Consumer preference shifts (frameless lines, slim Shaker profiles, painted-oak and natural wood wash finishes) require rapid SKU rationalization and targeted capacity investments.
- Optimizing channel economics: The RTA value chain intersects e-commerce, wholesale distribution, builder programs, and big-box retail—each requires distinct margin engineering and inventory playbooks.
- Executing M&A and partnership diligence: Fragmentation creates roll-up opportunities, but success hinges on validated revenue models and supplier integration risk assessments that this study enables.
What’s inside the PW Consulting RTA Kitchen Cabinet Study (practical deliverables)
- Topline market sizing and a transparent forecasting model (2026–2032) built on a documented bottom-up approach and triangulated with primary interviews and trade flows; outputs are presented in USD (Million).
- Demand-driver analysis covering housing starts, renovation cycles, unit economics for repair vs. replace, and channel-by-channel dynamics that explain why particular formats and finishes win in certain segments.
- Product & materials playbook: coverage of core constructions, finish trends, and the cost levers (materials, labor, packaging) that determine margin banding by product family.
- Competitive benchmarking and supplier scorecards: operational footprints, product strengths, channel strategies, and near-term roadmap intelligence for the leading and fast-growing players in the RTA segment.
- Regulatory and trade-impact models: tariff sensitivity analyses, landed-cost calculators under multiple duty scenarios, and compliance checklists for certification regimes relevant to RTA units.
- Go-to-market playbooks and 90–180 day tactical roadmaps designed for manufacturers, wholesalers, and retail distributors seeking immediate improvements in fill-rates, lead times, and gross margin.
- Scenario-based valuation and M&A models: accretion/dilution templates and integration risk checklists tailored to roll-ups and strategic partnerships.
- An annex of primary research notes, interview transcripts (anonymized), and the dataset that powers the models—provided under license to subscribing clients.
Competitive landscape — practical takeaways on leading players
The market is populated by specialized manufacturers and wholesalers that combine product design, inventory positioning, and dealer/channel programs to win. Our report profiles core operators and recent moves—summarized here to illustrate competitive dynamics without disclosing proprietary scorecards.
RTA (Ready To Assemble) Kitchen Cabinet Market
- ProCraft Cabinetry (Hillside, IL): Known for trend-driven door styles and frameless lines. Recent activity includes a prominent KBIS 2026 presence where the firm introduced a refreshed frameless line and expanded finishes—an indication of strategic investment in product-led differentiation and brand positioning heading into 2026.
- Cabinet City (San Gabriel, CA): A stocked wholesaler/manufacturer focused on solid-wood and contemporary styles, with deep relationships in the builder/developer segment. The company’s 2026 catalog release underlines an emphasis on merchandising and specification-led selling to channel partners.
- Kavalan Cabinetry (Austin, TX): A contractor-oriented supplier that emphasizes ready availability and wholesale program support—a typical model for firms that capture repeat business from trade contractors through logistics and SKU standardization.
- American Made Cabinets (United States): Positioned on affordability and multi-space applications, this firm illustrates how domestic manufacturing can compete on lead times and certification credentials rather than price alone.
- 10% Cabinetry (Ohio): A regional wholesale play specializing in shaker styles and fast fulfillment with dealer programs across the Midwest—representative of the strong local/regional operators in a fragmented marketplace.
Collectively, these firms demonstrate three repeatable strategic moves: product-led differentiation (design/finish innovation), channel locking (dealer & builder programs), and operational tightness (stocking & turnaround). Our full report maps where each tactic produces the best ROI and which capabilities must be in place to sustain it.
RTA (Ready To Assemble) Kitchen Cabinet Market
Regulation, tariffs, and quality certification — implications for 2026
The regulatory environment is in flux and will materially affect sourcing economics and supplier selection. Imported RTA cabinet kits and components are explicitly covered under Section 232 HTSUS classifications, and recent policy adjustments have introduced phased ad valorem duties—creating a widened spread between domestic and imported landed costs. Compounding trade risk, the industry now tracks both near-term duty adjustments and planned tariff escalations that could take effect across 2026–2027 in certain scenarios. Separately, quality certification (e.g., KCMA A161.1) is rising as a non-price differentiator and a distribution pre-condition for many national channels—compliance requires upfront testing and documentation investments but reduces downstream warranty and returns exposure.
Actionable recommendations — 90 to 180 day playbook for 2026
- Run a tariff-sensitivity stress-test on all SKUs. Reprice and prioritize SKUs that remain margin-accretive under 25% and 50% ad valorem shocks.
- Accelerate certification for core SKU families. Prioritize KCMA A161.1 testing for lines sold to national channels to reduce friction and enable premium placement.
- Pursue selective nearshoring or capacity partnerships to de-risk long-lead imported components—use landed-cost modeling to identify candidates for localization.
- Rationalize SKU complexity around a 20/60/20 rule: 20% hero SKUs, 60% configurable core platform, 20% niche/custom finishes. Free up working capital by slimming low-turn SKUs.
- Double down on channel-aligned logistics: trade programs and builder stocking models materially shorten lead times; test hub-and-spoke distribution pilots in priority metros.
- Prepare a targeted M&A shortlist focused on capacity, channel access, and certification assets; use our valuation framework to screen targets against tariff and integration risk.
Scenario planning: KPIs to monitor through 2026–2032
Our forecast assumes a baseline CAGR of 5.67% but prudently models two additional scenarios: a tariff-shock scenario that depresses import volumes and speeds domestic reshoring, and an accelerated-adoption scenario driven by premiumization and e-commerce penetration. Key leading indicators to watch include:
- Unit orders by channel (builders, e-tailers, wholesale)
- Average lead time and fill-rate metrics across distribution hubs
- Material cost indices (particleboard, MDF, solid wood) and freight rate spreads
- Certification adoption rates among suppliers and percentage of SKUs with KCMA seals
- Gross margin delta under varying tariff scenarios
How to use the full PW Consulting report
The full study contains the segmented market maps, SKU-level margin matrices, supplier scorecards, and downloadable model supporting the high-level narrative above. We intentionally showcase our methodologies and sample insights in this introduction to demonstrate rigor while withholding proprietary segmentation tables and channel shares that are included with the report subscription—these granular datasets are the decisive inputs for procurement tendering, M&A underwriting, and channel negotiations in 2026.
If your organization is preparing for sourcing decisions, channel realignment, or M&A activity in the RTA kitchen cabinet space this year, PW Consulting can provide tailored briefings, model workshops, and integration playbooks that convert the report’s insights into executable plans. Contact our research desk for access to the full dataset and a custom executive summary aligned to your priorities.
For detailed analysis of this topic, please visit the official page: RTA (Ready To Assemble) Kitchen Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com