

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Waterborne Epoxy Resin Market — USD 4,230M in 2025, 7.8% CAGR to 2032

Waterborne Epoxy Resin Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
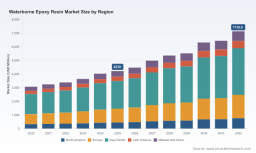
As companies finalize budgets and strategic roadmaps for 2026, the waterborne epoxy resin market presents a distinct combination of growth opportunity and technical/regulatory complexity. Our market model (base year 2025; historical window 2020–2025; forecast 2026–2032) shows an established growth trajectory: global revenues rose from USD 3,078.2 Million in 2020 to USD 4,230.0 Million in 2025, and are projected to reach USD 7,139.6 Million by 2032 at a compound annual growth rate (CAGR) of 7.8% over the forecast horizon. This briefing previews the strategic angles that matter for boardroom decisions in 2026 — highlighting where capital, R&D and commercial focus can create asymmetric value — while reserving the granular segmentation tables for the full PW Consulting report.
Waterborne Epoxy Resin Market
What the full study delivers (practical, transaction-ready content)
- Robust market sizing and forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) in USD Million with scenario and sensitivity layers suitable for valuation work.
- Segmentation by product type, application and region with demand drivers, pricing trends and served‑available markets — presented as downloadable data cubes for integration into financial models. (Note: detailed segment tables are not reproduced in this preview.)
- Competitive landscaping and capability mapping for incumbent producers and fast‑moving challengers, including technology strengths, plant footprints and go‑to‑market strategies.
- Supply‑chain and cost‑base analysis covering key precursors, feedstock concentration risk and spot vs contract price dynamics — with hedging and sourcing playbooks.
- Regulatory impact matrix (EPA, REACH, national programmes) outlining compliance timelines, reformulation risk and certification pathways.
- Commercial playbooks: pricing levers, premium productization (low‑VOC, CMR‑free, halogen‑free, bio‑based), channel strategies and partner ecosystems.
- Investment decision frameworks for CapEx, M&A screening criteria and a shortlist of tactical moves (capacity, licensing, JV, bolt‑on targets).
Market dynamics that will shape 2026 choices
The market balance is being re‑set by three interconnected forces: regulation, raw‑material volatility, and product innovation. Policy momentum toward lower VOC content and restrictions on legacy precursors is accelerating R&D and adoption cycles for waterborne systems.
Waterborne Epoxy Resin Market
- Regulatory drivers: Tighter VOC limits in major markets (e.g., industrial and architectural coatings thresholds) and REACH restrictions on certain precursors are not hypothetical — they materially affect allowable formulations and compliance timelines. Companies that treat regulatory change as a discrete risk event will be outpaced by those that treat it as a product and market opportunity.
- Raw material and supply risk: Key feedstocks used in epoxy synthesis face concentrated production and increasing scrutiny. Precursors subject to regulatory attention and episodic supply disruptions introduce price volatility and potential reformulation constraints, affecting cost of goods sold and margin profiles.
- Product and application innovation: Advances in aqueous dispersions, 2K hardener systems and curing agents are enabling waterborne epoxies to meet performance benchmarks previously achievable only by solventborne systems — opening demand in flooring, industrial maintenance and OEM coatings. Performance parity combined with sustainability credentials is the core battleground.
These dynamics translate into three practical market realities for 2026: accelerating premiumization of compliant chemistries; near‑term cost pressure from feedstock oscillation; and selective capacity expansion in Asia and other demand hubs. The market concentration is moderate — the top three players account for a meaningful share, with the top five controlling just under half of industry revenues — creating room for regional specialists and technology‑focused challengers.
Waterborne Epoxy Resin Market
Competitive landscape — who matters and why
Leading suppliers have diversified strategic postures that reflect different sources of advantage:
- Allnex (Frankfurt am Main) — specialist capabilities in waterborne dispersions and 2K hardeners. Recent capacity expansion in China signals a play for scale and proximity to rapid Asia demand growth.
- Huntsman Corporation (The Woodlands) — utilizes its Araldite brand strength to serve industrial and architectural coatings segments with integrated resin/hardener systems, emphasizing formulators that require performance assurance at scale.
- Evonik Industries (Essen) — positions its Ancarez® dispersions for floorings, corrosion protection and OEM coatings, focusing on high‑value verticals where differentiated performance and low lifecycle cost matter.
- Olin Corporation (Clayton) — broad epoxy portfolio with recent launches in curing agents to improve durability for harsh environments, indicating a strategic push into high‑spec industrial segments.
- Kukdo Chemical (Seoul), ADEKA (Tokyo), DIC (Tokyo) — regional champions focused on compliant, low‑VOC systems with strong ties to local formulators and OEMs; these players are often the fastest at translating regional regulatory shifts into market‑ready products.
Recent industry moves illustrate the landscape’s dynamism: in early 2025 Westlake Epoxy launched a CMR‑free portfolio marketed for high‑performance flooring and low‑VOC applications, while Allnex expanded production capacity in China and Olin rolled out a novel curing agent in early 2025. These product and capacity initiatives underscore two themes: incumbents are protecting share via performance differentiation, and investments are being led by companies that can marry formulation know‑how with regional manufacturing agility.
Strategic implications for 2026 decision cycles
For executive teams and boards planning near‑term actions, the research supports a structured, prioritized response across commercial, technical and corporate development levers.
- Near‑term (0–18 months):
- Secure raw‑material continuity: diversify procurement, negotiate multi‑year contracts for critical precursors, and establish secondary sourcing in different jurisdictions to mitigate disruption risk.
- Quick wins in product portfolio: accelerate scaled launches of reformulated low‑VOC and CMR‑free variants where certification hurdles are manageable. Prioritize saleable SKUs tied to existing customer relationships to preserve margin.
- Commercial segmentation: realign sales incentives around high‑value applications (e.g., industrial maintenance, flooring, OEM segments that accept premium pricing) and deploy targeted field‑technical support to capture formulators’ trust.
- Medium‑term (18–36 months):
- Capacity and footprint decisions: use the report’s regional demand curves to evaluate capacity expansion versus tolling/JV options. For many firms, localized manufacturing in Asia or near major OEM clusters will unlock service and logistics advantages.
- R&D and IP strategy: invest selectively in proprietary dispersant chemistry, cross‑linked networks that lower VOC needs, and hardened systems that minimize cure time without sacrificing durability.
- M&A and partnership playbook: prioritize bolt‑on assets that provide regulatory‑compliant chemistries or regional market access rather than large, transformational deals that dilute focus.
- Longer‑term (3–7 years):
- Transformational bets: evaluate bio‑based feedstock pathways and halogen‑free systems as strategic options to future‑proof portfolios against tightening restrictions.
- Value chain integration: consider backward integration into critical intermediates if volume economics and regulatory stability can be secured, but only after rigorous scenario testing using the full forecast dataset.
How PW Consulting’s frameworks convert insights to decisions
The full report equips leaders with usable decision tools rather than descriptive analytics. Examples include:
- Value‑at‑stake models that map product mixes to P&L outcomes under alternate raw‑material price and regulatory scenarios.
- Sourcing heatmaps that identify critical supply chokepoints and cost exposures by precursor and geography.
- Go‑to‑market scorecards for channel and segment prioritization, pairing technical investment needs with revenue potential and margin sensitivity analyses.
- M&A screening templates that rank targets by technology fit, regulatory compliance state and commercial synergy potential.
Closing: why 2026 is a pivotal year
Several converging trends make 2026 a pivotal inflection point: tightening regulation that changes the cost/benefit calculus of solvent vs waterborne systems, technology improvements that lower the performance gap, and durable end‑market demand growth reflected in our 7.8% CAGR projection to 2032. For incumbent producers and new entrants alike, the question is not whether to participate in waterborne epoxy, but how to position to capture the disproportionately larger share of value created by premium, compliant formulations and resilient supply chains.
PW Consulting’s full Waterborne Epoxy Resin Market report contains the granular regional and application splits, downloadable forecast tables in USD Million, and the tactical annexes that investment committees and strategy teams need to convert 2026 intentions into executable plans. This preview outlines the strategic architecture; the complete report supplies the telemetry to act with confidence.
For detailed analysis of this topic, please visit the official page: Waterborne Epoxy Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com