

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dry Etching Equipment Market to hit USD 41.99 Million by 2032 at 7.61% CAGR

Dry Etching Equipment Market: Strategic Intelligence Briefing for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present this focused industry briefing to frame the strategic choices semiconductor executives, equipment suppliers, investors, and policy teams will confront in 2026. This note synthesizes market trajectory, structural dynamics, regulatory stressors, and competitive playbooks—showing the contours of value creation while preserving the report’s detailed segment models and proprietary vendor scoring for subscribers.
Dry Etching Equipment Market
Why this research matters for 2026
Dry etching remains a linchpin of front-end semiconductor manufacturing, underpinning advanced logic, memory, MEMS, and power-device roadmaps. Following a measured recovery and investment cycle from 2020 through 2025, the market exhibits renewed, structurally driven growth. Our base-year analysis places 2025 as the analytical pivot; the market has expanded from an estimated USD 17.42 million (2020) to USD 25.13 million (2025) and—under the scenarios modelled—continues on a multi-year expansion path. The forecast period (2026–2032) reflects a compound annual growth rate of 7.61%, culminating in an estimated market size near USD 42.0 million by 2032.
Dry Etching Equipment Market
For executive teams, this profile creates a narrow window to convert demand visibility into durable competitive advantage: choices made in equipment roadmaps, supplier commitments, gas and abatement strategies, and factory CAPEX in 2026 will disproportionately influence cost-position and yield by 2028–2030.
Dry Etching Equipment Market
Market snapshot and structural characteristics
- Concentration and competition: The market is concentrated—our CR3 and CR5 metrics indicate meaningful incumbent strength (CR3 ≈ 75%; CR5 ≈ 85%). This structure rewards scale, process IP, and installed-base services, while opening tactical opportunities for focused challengers in niche process windows.
- Technology vector: Advanced atomic-layer and sub-angstrom etch controls, high-density plasma and inductively coupled plasma platforms, and deep-reactive ion etch systems continue to drive equipment spend. Incremental performance (profile control, selectivity, and damage reduction) remains the principal buy-criteria for logic and 3D memory nodes.
- Regulatory and emissions pressures: Regulatory frameworks and industry voluntary agreements—targeting fluorinated chemistries and high-global-warming-potential gases—are recalibrating process economics and supply chains. Notably, regulatory attention to PFAS-containing chemistries and formal partnerships to reduce certain PFCs are elevating compliance costs and prompting tool-level redesign and abatement investments.
- Geopolitical and infrastructure overlays: Export controls and enhanced due diligence for advanced computing ICs have introduced incremental friction into equipment flows and supplier selection practices; this elevates the value of diversified manufacturing footprints and documented compliance programs.
What this means for strategic decision-making
In 2026, senior leaders need to translate market momentum into durable returns. Our research highlights five near-term imperatives:
- Prioritize modularity and upgrade paths: Given tight timelines for technology node shifts and etch process complexity, platforms that decouple hardware base from control software and chemistries reduce total cost of ownership and accelerate ramp.
- Accelerate gas-substitution and abatement R&D: Regulatory trends and voluntary PFC/NF3/SF6 reduction initiatives are not transitory. Investing in alternative chemistries, chamber clean redesigns, and on-tool abatement demonstrators will be a competitive differentiator.
- Embed regulatory foresight into procurement: Equipment contracts must include compliance clauses, transfer-of-technology risk assessments, and contingency options for export-restricted nodes to prevent downstream disruption.
- Adopt a hybrid supplier strategy: Balance scale-supplier relationships (to capture service and integration benefits) with targeted partnerships for niche capabilities (e.g., MEMS DRIE, atomic-layer etch) where smaller vendors can deliver differentiated value.
- Use scenario-based CAPEX allocation: Apply a staged-capex playbook that aligns high-ticket investments with validated process yield improvements and regulatory roadmaps rather than fixed calendar pushes.
Competitive landscape: strategic profiles and positioning
Our proprietary competitive assessment synthesizes product architecture, installed base, service economics, and roadmap clarity across leading providers. Key strategic dispositions include:
- Lam Research Corporation (San Jose, CA) — Market-leading competence in high-volume dielectric and conductor etch systems. Strengths: robust high-throughput platforms, deep customer relationships in advanced nodes, and product lines engineered for atomic-layer etching and high-volume manufacturing.
- Applied Materials, Inc. (Santa Clara, CA) — Broad platform portfolio with integrated process control solutions optimized for logic and memory customers; competitive where turnkey process solutions are valued.
- Tokyo Electron Limited (Tokyo, JP) — Notable leadership in sub-angstrom atomic-layer etching techniques critical to 3D NAND and tightly scaled logic nodes; strong product fit for layered-stack memory architectures.
- Hitachi High-Technologies (Tokyo, JP) — Niche strength in EMCP and microwave ECR plasma etch systems; recognized for conductor etch and certain non-volatile materials.
- Plasma-Therm LLC (St. Petersburg, FL) — Agile provider of configurable plasma-based solutions. Recent corporate communications emphasize software, partnerships, and international expansion efforts to broaden market reach.
- Oxford Instruments plc (Abingdon, UK) — Research-to-production breadth with ICP RIE and deep-silicon etch systems; valued by academic labs and manufacturers scaling R&D processes.
- SPTS Technologies (KLA division, UK) — Focus on integrated wafer processing capital equipment, with strengths in etch and thermal flows for specialty fabs.
- ULVAC Technologies (Methuen, MA) and Chinese/Korean vendors (AMEC, NAURA, GigaLane, Semes, Jusung, SAMCO) — Regional champions and competitive disruptors offering targeted solutions for nodes down to 5nm, DRIE for MEMS, and localized service models.
Recent vendor activity underlines tactical positioning: Plasma-Therm’s 2026 review highlights software and partnership-led expansion, and SAMCO’s early-2026 DRIE equipment shipment to an academic nanolab underscores continued investment in high-precision MEMS tooling and ecosystem expansion.
Report deliverables that drive action (what’s inside)
Our full study is designed as an operational toolkit for 2026—structured to move teams from insight to execution. Core deliverables include:
- Market sizing and forecast model (base-year 2025; historical 2020–2025; forecast 2026–2032) with scenario toggles and sensitivity to gas restrictions and node adoption rates.
- Vendor benchmarking and scorecards covering technology, service economics, roadmap credibility, and exposure to regulatory and export risk.
- Technology readiness and use-case mapping for etch approaches (including atomic-layer etching, ICP/DRIE variants, and plasma dicing), with recommended investment timelines.
- Regulatory impact assessment and abatement playbook—detailing compliance cost vectors, alternative chemistries, and on-tool abatement approaches tied to process flows.
- Procurement and CAPEX decision frameworks—tradeoffs between platform acquisition, upgrades, and fab throughput optimization.
- Merger & acquisition heatmap and partnership scenarios prioritized by strategic fit and integration complexity.
- Primary interview excerpts and supplier reference checks that contextualize quantitative forecasts.
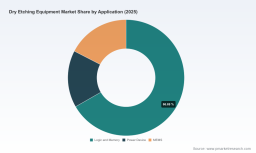
Note: To preserve strategic value for license holders, the report intentionally omits public disclosure of detailed segment splits and granular region/application percentages in this briefing; those analytics are provided in full to subscribers and decision-makers who access the source report.
How buyers, suppliers, and investors should use this research in 2026
- Buyers (fabs & IDM): Use the vendor scorecards and TCO framework to renegotiate service-level agreements with an emphasis on upgradeability, abatement options and compliance warranties.
- Suppliers: Prioritize R&D investments in gas-efficient processes, control-software differentiation, and modular hardware. Consider selective partnerships to accelerate market entry in MEMS and DRIE segments.
- Investors & M&A teams: Target assets offering differentiated process IP or abatement-enabled platforms that lower the purchaser’s regulatory and operational risk. Evaluate consolidation plays that create scale in service and aftermarket revenue.
Next steps and where to get the full intelligence
2026 will be a pivotal year: regulatory action, node transitions, and service economics will interact to reprice suppliers and reorder customer priorities. PW Consulting’s full Dry Etching Equipment Market report provides the granular segmentation, supplier matrices, and modeled scenarios needed to convert the strategic imperatives above into executable plans.
For procurement teams, strategy groups, and investors preparing 2026 plans, the report supplies the evidence base to prioritize CAPEX, structure supplier engagements, and mitigate regulatory exposure. Reach out to access the complete dataset, vendor scorecards, and scenario models—our subscription portal and advisory team are prepared to run bespoke briefings aligned to your decision calendar.
For detailed analysis of this topic, please visit the official page: Dry Etching Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com