

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Food Cans Market to Hit USD 240.5M by 2032 at 2.89% CAGR

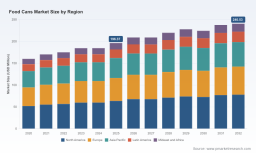
Food Cans Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
The global food cans market is transitioning from a recovery phase into a period of measured structural change. After expanding from an estimated USD 160 million in 2020 to roughly USD 196.4 million in 2025, the market is projected to reach the mid‑two‑hundreds by the end of the 2026–2032 forecast window, growing at a compound annual growth rate (CAGR) of about 2.89% through the forecast horizon. These headline figures mask important inflection points: raw material volatility, shifting regulatory regimes, and a competitive landscape increasingly shaped by consolidation and product innovation.
Food Cans Market
Why the 2026 inflection matters for corporate strategy
-
Near‑term budgeting and procurement: The market’s modest but persistent growth means firms cannot rely on volume levers alone to preserve margins. With tin and aluminum inputs experiencing greater price volatility, procurement strategies that were optimal in 2023 are now exposure‑prone in 2026. Buyers, contract negotiators and procurement leaders must calibrate multi‑year contracts and hedging strategies against a background of tariffs and raw material swings.
Food Cans Market -
Regulatory compliance and product architecture: Recent regulatory moves — from federal rule changes to state‑level labeling mandates — are shifting the cost of compliance and altering product specifications. Firms making packaging and formulation investments in 2026 need to build flexibility into filling lines and quality systems to avoid costly retrofits when traceability timelines and labeling rules come into force.
Food Cans Market -
M&A and competitive positioning: Concentration metrics indicate a market where a small set of global and regional players hold meaningful shares. For firms evaluating inorganic growth or divestiture options, 2026 is a year to decide whether to pursue scale, capability or niche positioning; the right move will depend on how a firm trades off operational complexity against access to regional customers and raw materials.
-
Innovation and premiumization: Demand pockets for higher‑value, functional packaging (coatings, easy‑open ends, retortable aluminum solutions) are emerging. Investment in R&D and co‑development partnerships can unlock premium price points and defensive margins even as overall market growth remains modest.
Market dynamics shaping 2026 decisions
-
Raw‑material shocks and trade policy: Tin prices have surged since the start of 2026, increasing cost pressure on tinplate users. At the same time, longstanding trade measures such as Section 232 tariffs on imported tinplate continue to affect sourcing economics for manufacturers relying on import channels. These factors combine to make local sourcing, alloy substitution and supplier diversification high‑priority actions.
-
Regulatory inflection points: The FDA’s 2025 revocation of numerous legacy Standards of Identity, together with the extension of FSMA Rule 204 traceability deadlines to July 2028, reshapes compliance roadmaps for canned fruits, vegetables and dairy products. California’s AB 660 introduces standardized quality or safety date requirements that will have knock‑on effects for national supply chains and retailer specifications.
-
Technological innovation: Coil‑applied coatings and next‑generation easy‑open ends are moving from pilot to commercialization. Product launches in 2026 highlight how coating chemistry and forming technology can drive category gains in pet food and ready meals by improving shelf life and consumer convenience.
-
Supply chain fragility: The combination of concentrated suppliers for key inputs, tariffs, and regional manufacturing footprints increases the risk profile for firms that have not stress‑tested logistics and single‑source dependencies. Scenario planning for port disruption, energy price shocks or rapid input inflation should be integrated into 2026 planning cycles.
Competitive landscape — what to watch from incumbents
The market structure demonstrates mid‑to‑high concentration: the top three players capture a substantial portion of value, while the top five solidify a dominant cluster. This creates a two‑track environment — scale leaders pursue efficiency and portfolio breadth, while regional and niche players target customer intimacy and technical differentiation.
-
Crown Holdings, Inc. (Atlanta, GA) — A major global producer with breadth across food and aerosol tinplate operations. Strategic priorities include optimizing North American tinplate capacity and leveraging beverage can capabilities for cross‑category synergies. ( https://www.crowncork.com)
-
Silgan Holdings Inc. (Stamford, CT) — Focused on metal cans for food and beverages, Silgan’s strength lies in food‑specific manufacturing lines and customer intimacy. Expect continued emphasis on automation and tailored logistical solutions. ( https://www.silgan.com)
-
Ardagh Group (Dublin, Ireland) — A key European and global producer of steel and aluminum cans, Ardagh will likely pursue margin enhancement through network rationalization and product innovation in protective coatings. ( https://www.ardaghgroup.com)
-
Ball Corporation (Westminster, CO) — A leader in aluminum solutions, including retort and two‑piece food cans. Ball is positioned to capture premium segments where lightweighting and retort performance command price premiums. ( https://www.ball.com)
-
Toyo Seikan Group Holdings, Ltd. (Tokyo, Japan) — A global metal packaging specialist whose route to growth lies through emerging market expansion and technical service offerings for food processors. ( https://www.toyo-seikan.co.jp/e/)
-
Regional and specialist players — Companies such as CPMC Holdings, Can‑Pack Group, Kaira Can, Nampak and Independent Can maintain important regional footprints and serve as agile partners for local processors. These firms often win on lead time, customization and regulatory responsiveness. Representative sites: ( https://www.cpmc.com.cn/), ( https://www.canpackgroup.com), ( https://www.kairacans.com), ( https://www.nampak.com), ( https://independentcan.com)
Recent developments worth immediate attention
-
Product innovation: April 2026 saw a major supplier introduce a first‑to‑market coil‑applied coating designed for pet food cans and easy‑open ends in the U.S., signaling accelerated commercialization of aluminum coating technology and new value offers to brand owners.
-
Trade shows and commercial outreach: Producers continue to use major packaging exhibitions to showcase integrated solutions and retrofit services — a reminder that go‑to‑market plays in 2026 will be as much about service bundles as product specs.
-
Regulatory updates and pricing dynamics: The conjunction of tightened tin supply, tariff regimes and state labeling laws has measurable implications for product formulations, labeling spend and margin engineering.
What PW Consulting’s Food Cans Market report delivers — practical, decision‑grade assets
-
Executive dashboard: A concise set of KPIs and early‑warning indicators (price, inventory, lead times) tied to actionable thresholds for procurement, R&D and commercial teams.
-
Scenario models: Three supply‑side and three demand‑side scenarios calibrated to commodity shocks, tariff shifts and regulatory ramps, with P&L impact and capital planning overlays.
-
Supplier heatmaps and risk scores: A validated supplier risk framework that flags single‑source exposure, material concentration and logistical fragility at the node level.
-
Regulatory impact playbook: Concrete steps to align product specifications, labeling and traceability systems with federal and state requirements through 2028, including recommended timelines and estimated implementation costs.
-
Commercial growth plays: Routes to market for premium and convenience segments, including recommended pricing architectures and trade promotion strategies that protect margin while preserving shelf velocity.
-
M&A and partnership screening: A shortlist methodology for identifying acquisition targets and technology partners, with diligence checklists and pro forma integration considerations.
-
Competitive intelligence pack: Company scorecards for leading manufacturers, mapped capabilities, capacity footprints and capability gaps — designed to inform supplier negotiations and partnership choices.
-
CapEx and automation ROI calculator: Tailored models to test investments in forming lines, coatings application and converting equipment under multiple input‑cost trajectories.
How to use this intelligence in 2026 planning cycles
-
Procurement and Sourcing teams should run cost‑to‑serve models incorporating tariff scenarios and revised supplier T&Cs; prioritize dual‑sourcing for critical inputs and consider local content when tariff exposure is material.
-
R&D and Packaging teams must fast‑track trials of alternative coatings and end designs that reduce dependence on constrained tinplate and meet strengthened traceability and labeling mandates.
-
Commercial leaders need to rework account plans to capture value from convenience and premium segments, while insourcing or partnering for value‑added services such as private‑label co‑packing and traceability reporting.
-
Finance and Corporate Development should recalibrate M&A screens to value capability (coatings, retortable aluminum) over pure capacity, given the medium‑term growth profile and competitive concentration.
Final note — the teaser approach
This briefing is intentionally focused on strategic implications and decision‑grade themes rather than exhaustive segment minutiae. The full PW Consulting Food Cans Market report contains the granular regional and application splits, supplier contracts, price curves and primary interview transcripts that corporate teams need to execute on the plays outlined above. For procurement modeling, M&A diligence or regulatory compliance roadmaps in 2026, the deep data set and execution toolkits in the full report are essential.
Next steps
If your 2026 planning cycle includes procurement commitments, capex approvals, or M&A screening in metal food packaging, engage PW Consulting for a tailored briefing. Our clients receive the full dataset, scenario models and a facilitated strategy workshop to convert insights into a one‑year operational plan and a three‑year roadmap.
For detailed analysis of this topic, please visit the official page: Food Cans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com