

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Polymer Gas Separation Membrane Market to Reach USD 220M by 2032 at 6.3% CAGR — PW Consulting

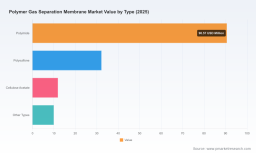
Polymer Gas Separation Membranes: Strategic Imperatives for Corporate Decision‑Making in 2026
As governments, energy companies and industrial gas users accelerate decarbonization and process‑efficiency initiatives, polymer gas separation membranes have moved from niche utility to a strategic enabling technology. PW Consulting’s latest market research—anchored on a 2025 base year—projects the global polymer gas separation membrane market to grow from a 2025 baseline of USD 144.5 Million and reach approximately USD 220 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.3% across the 2026‑2032 forecast window. This research note outlines why that trajectory matters for corporate leaders planning capital allocation, R&D priorities, supply‑chain strategies and inorganic moves in 2026.
Polymer Gas Separation Membrane Market
Why this market is strategically relevant in 2026
- Enabler for decarbonization: Polymer membranes are increasingly pivotal for carbon capture, hydrogen purification and methane upgrading—applications that sit at the intersection of emissions reduction and industrial productivity.
- Scale meets specialization: Market growth is steady and predictable at the macro level (CAGR ~6.3%), but value accrual will concentrate in specialized polymer types, module designs and system integration capabilities—creating differentiated margin pools.
- Supply‑chain sensitivity: Raw material and energy cost dynamics, plus evolving trade and tariff regimes, mean manufacturers and end‑users will need to manage input cost volatility and localization decisions as strategic levers.
What the numbers tell us (and what they don’t)
The headline figures—mid‑2020s base and low‑double‑digit percentage growth to 2032—signal a mature, investment‑worthy expansion rather than a speculative boom. This implies that 2026 is a year for operationalizing strategy rather than for speculative positioning: invest to capture share in proven applications, double down on value‑adding differentiation (such as high‑performance polyimides or hollow‑fiber engineering), and optimize the supply chain.
Polymer Gas Separation Membrane Market
We deliberately refrain from disclosing detailed regional or application splits here; the value of the underlying research lies in granular, proprietary segmentation and scenario analyses that are included in the full PW Consulting report. The public summary is a strategic preview—sufficient to guide high‑level decisions, but intentionally limited to encourage engagement with the full dataset for transaction‑level planning.
Polymer Gas Separation Membrane Market
Drivers of demand and upside opportunities
- Hydrogen economy ramp: As electrolytic and blue hydrogen projects move to commercial scale, the need for efficient H2 purification will create higher‑value membrane demand. Membrane performance characteristics that reduce compression or cooling requirements will command premium pricing.
- Carbon management: Polymer membranes that can be integrated into carbon capture or CO2 clean‑up stages of industrial processes present cross‑sector growth opportunities, especially where low‑energy separation delivers lifecycle emissions benefits.
- Distributed gas generation and industrial efficiency: On‑site nitrogen generation and oxygen enrichment are established applications that continue to drive steady, replacement and upgrade demand—an attractive base for subscription models and service contracts.
- Technology substitution and material innovation: Advances in polymer chemistry and module engineering (e.g., higher permeability combined with selectivity retention) will create periodic windows for incumbents and new entrants to reprice competitive dynamics.
Key risks and structural headwinds
- Raw material and energy volatility: Feedstock and utility price swings increase operational cost uncertainty for membrane manufacturers. Strategic players will need hedging strategies, vertical partnerships or geographic diversification to stabilize margins.
- Regulatory shifts and trade policy: Tariffs and changing import/export regulations can alter competitive cost positions overnight. Companies should model multiple trade‑policy scenarios into 2026 capex decisions.
- Technology commoditization: Lower‑cost membrane offerings can compress margins for generic product lines; differentiation through system integration, warranties and performance guarantees will be essential.
- Market concentration dynamics: While the sector is not dominated by a single player, market share is meaningfully clustered among a small group of specialized firms. That concentration favors firms that can combine technology leadership with scale‑efficient manufacturing and global service networks.
What our report delivers to help executives act in 2026
- Actionable market sizing and validated forecast scenarios—enabling internal valuation, investment case development and M&A screening.
- Proprietary segmentation frameworks that align polymer types, module architectures and applications to differentiated margin pools and go‑to‑market plays—presented without revealing competitive customer lists or sensitive contract economics in this preview.
- Supply‑chain diagnostics that map feedstock exposure, logistics risk and localization levers—accompanied by supplier scorecards and cost‑sensitivity analyses executives can operationalize.
- Regulatory and policy scenario planning—quantifying the impact of emissions rules, trade measures and certification pathways on demand and cost structures.
- Commercial playbooks—pricing, bundling and service strategies tailored to OEMs, EPC contractors and end‑users, plus KPI templates for performance monitoring.
- Investment, M&A and partnership roadmaps—prioritized deal themes and target archetypes informed by valuation benchmarks, synergy estimates and integration risks.
Competitive landscape: capability map and strategic postures
The industry comprises established industrial gas companies, specialty chemical manufacturers, and technology‑focused membrane firms. Key players combine polymer R&D, hollow‑fiber manufacturing, module engineering and global aftermarket service. Several archetypes stand out:
- Integrated industrial gas majors: Firms with deep customer relationships across air separation and industrial gas supply that can embed membrane offerings into larger solutions. Their strength is system sales and broad service footprints; their challenge is rapid product innovation compared to focused membrane specialists.
- Specialty polymer and materials innovators: Companies that own proprietary polymer platforms—enabling high‑performance membranes for H2 and CO2 applications—are positioned to capture premium segments if they can scale manufacturing efficiently.
- Module and system integrators: Firms that excel in turning membrane elements into reliable, packaged systems—offering uptime guarantees and lifecycle services—are increasingly valued by asset operators focused on total cost of ownership.
- Emerging challengers and regional champions: Smaller, agile firms that leverage niche IP or cost advantages to win specific markets; they are attractive acquisition targets for scale players seeking technology or market access.
Our analysis identifies specific competitive strengths across leading firms—ranging from polymer R&D leadership and hollow‑fiber manufacturing scale to global service networks and industrial‑grade systems engineering. Rather than disclose sensitive market shares here, we map each firm against capability vectors investors and corporate strategists care about: R&D depth, manufacturing scale, system integration, aftermarket presence and partnership appetite.
Reading recent industry developments through a strategic lens
- Partnerships between industrial gas companies and renewable energy firms signal a pivot toward integrated carbon management and low‑carbon hydrogen solutions—an indicator that collaboration will be a primary route to scale in 2026.
- New membrane product launches targeted at hydrogen separation evidence that material innovation continues to be a primary competitive battleground—companies that delay R&D investment risk losing premium segments.
- Capacity expansions and plant investments by select membrane manufacturers indicate that supply is being provisioned for meaningful growth; however, timing and regional placement of those capacities will determine near‑term market tightness and price dynamics.
- Private and public capital activity—spanning strategic partnerships, plant investments and targeted product development—underscores that M&A and alliance formation will accelerate in 2026 as firms seek to close capability gaps quickly.
2026 strategic playbook: priorities for corporate leaders
- Operationalize scenario planning: Build short lists of capital projects and supplier alternatives under conservative, base and accelerated demand scenarios.
- Secure feedstock resilience: Move from a transactional procurement model to strategic supplier partnerships, capacity reservations or co‑investment for critical polymer precursors and processing inputs.
- Differentiate through system value: Invest in integration capabilities, digital monitoring and service contracts to capture aftermarket economics beyond element sales.
- Pursue targeted M&A and partnerships: Prioritize deals that close capability gaps—especially in high‑performance polymers, hollow‑fiber manufacturing or regional service footprints—over broad market acquisitions that dilute focus.
- Embed regulatory surveillance: Operational and commercial teams must be able to translate policy signals (emissions rules, trade measures, cross‑border subsidies) into commercial actions within weeks, not quarters.
Conclusion — Why engage with the full PW Consulting report
For 2026, the imperative is clear: transition from strategic intent to executable programs that capture the steady, predictable upside in polymer gas separation membranes while defensively managing cost and regulatory risks. PW Consulting’s full report provides the granular segmentation, supplier benchmarks, scenario models and commercial playbooks necessary to convert the market’s macro promise into measurable corporate outcomes. This preview has surfaced the strategic contours; the full intelligence pack—containing proprietary splits, regional and application‑level economics, and validated supplier scorecards—enables transaction‑level decisions and operational planning.
Access the comprehensive analysis to align your 2026 investment roadmap with the differentiated opportunities this market presents. PW Consulting’s dataset and advisory services are structured to accelerate decision‑making, de‑risk execution and unlock margin‑rich positions across the polymer gas separation membrane value chain.
For detailed analysis of this topic, please visit the official page: Polymer Gas Separation Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com