

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plastic Sorting Machine Market to Reach USD 180M in 2025; 11.68% CAGR

Plastic Sorting Machine Market: Strategic Preview for 2026 Decision-Makers
Why this study matters now
As corporations and municipalities move from commitments to enforceable obligations, the plastic sorting machine market has transitioned from a niche operational purchase to a strategic lever for circularity, cost control, and regulatory compliance. Our PW Consulting analysis — grounded on a 2025 base year and a seven-year forecast horizon — shows the market expanding at a compound annual growth rate of roughly 11.7%. After a steady recovery in the early 2020s, market momentum accelerates into the late 2020s under the combined pressure of product stewardship laws, manufacturer recycled-content mandates and rising commercial demand for quality feedstock. For executives preparing capital budgets and transformation roadmaps in 2026, this study reframes plastic-sorting hardware as both a technology bet and a supply-chain hedge.
Plastic Sorting Machine Market
Macro dynamics that will shape 2026 choices
-
Regulatory inflection points: Policy is the single largest near-term demand driver. Extended producer responsibility (EPR) frameworks and recycled-content mandates are moving from proposal to enforcement in key markets. These create hard compliance deadlines and, therefore, compressed procurement windows for sorting equipment and downstream processes. Organizations that delay decisions face not just higher prices but also lower selection among vendors with available lead time slots.
Plastic Sorting Machine Market -
Capital intensity and component concentration: Optical sorting platforms—particularly those using short-wave infrared detectors—depend on a concentrated supply base for critical camera and detector modules. Our interviews and industry tracking identify pronounced lead-time volatility for specialized detector arrays; procurement cycles must therefore be planned with multi-quarter buffers. This concentration amplifies supply-side risk and elevates the strategic value of vendor relationships and technical due diligence.
Plastic Sorting Machine Market -
Labor and operational economics: High labor costs in certain markets increase the relative attractiveness of higher-automation configurations even when initial capital outlays are greater. For firms operating in high-cost jurisdictions, the business case for automated sorting improves materially when OPEX, throughput and contamination-reduction benefits are modelled over realistic operating horizons.
-
Market structure and consolidation: The market exhibits moderate concentration at the top. The leading three and five suppliers account for a majority share of commercial deployments, indicating both economies of scale in R&D and a growing service-after-sales advantage tied to installed bases. This concentration favors vendors with integrated software, spare-parts logistics and retrofit capabilities — dimensions that buyers should explicitly weigh beyond headline performance metrics.
Technology and operational trends: what to prioritize in 2026
-
Hybrid sensing architectures: Pure RGB camera systems remain competitive for certain use-cases, but NIR spectroscopy and hyperspectral approaches are increasingly decisive for mixed-plastic streams where polymer identification and pigment masking are challenges. Buyers should specify performance across realistic contamination profiles, not just idealized material samples.
-
AI and data-centred performance: Machine learning is moving from a marketing point to an operational requirement. Vendors that surface transparent training datasets, edge-inference models optimized for production environments, and standardized model-retraining pathways will reduce operator friction and unlock incremental purity gains.
-
Modularity and retrofitability: Given uneven capital budgets and evolving feedstock mixes, modular systems that can be upgraded — sensors, ejector arrays, or software — will deliver higher lifetime value. Procurement frameworks should include option-to-upgrade clauses and clear service-level agreements for performance validation post-upgrade.
-
Service, spares, and lifecycle economics: The true cost of sorting is realized over years, not at point of sale. Vendors with robust local service footprints, predictable spare-parts pipelines, and remote-diagnostics capabilities materially lower downtime risk. Consider service revenue and installed-base density as part of total-cost-of-ownership comparisons.
Competitive landscape: signals from the field
Our market scanner concentrates on suppliers that are shaping commercial standards and innovation trajectories. Leading OEMs from established clusters provide end-to-end optical sorting portfolios, many combining NIR-based polymer identification with AI-driven defect and color recognition. Regional specialists bring practical, cost-optimized solutions for post-consumer streams, while a subset of entrants focuses on high-performance, hyperspectral deployments for premium feedstock customers.
-
Tiered innovators: Some firms deliver full-range optical sorting platforms for bottles, flakes and pellets with AI-enabled modules and integrated control systems, positioning themselves for large recycling operators and industrial plastics processors.
-
Regional challengers: A number of players focus on RGB camera-based sorters tailored for cost-sensitive post-consumer recycling markets, prioritizing price-performance balance and local serviceability.
-
Differentiation vectors: In vendor selection, emphasize (1) sensor mix and upgrade paths, (2) validated throughput and purity under representative contamination, (3) spare parts and component sourcing resilience, and (4) evidence of field-proven AI models and retraining practices.
-
Market motions: Trade-show activity and exhibition footprints in 2025 and 2026 provide leading indicators of product focus and commercialization timelines. Several prominent firms showcased expanded optical-sorting lines at major plastics events, signaling near-term availability of next-generation modules and partnerships aimed at expanded retrofit business.
How PW Consulting’s study changes procurement and investment choices in 2026
-
Time procurement to supply realities: With concentrated component markets and documented lead-time volatility for specialized detector arrays, procurement teams should align RFP cycles with realistic fulfillment calendars and negotiate priority allocation or alternative sourcing commitments.
-
Prioritize pilots that stress-test your worst-case feedstocks: Require vendors to validate performance on contaminated, multi-polymer, and colored-material runs. Acceptance criteria should be based on measured purity, yield, and operational throughput rather than vendor-declared peak specifications.
-
Structure contracting around lifecycle outcomes: Move beyond one-off CapEx purchases. Consider service-based models, uptime guarantees, and performance-linked payments that align vendor incentives with material recovery objectives.
-
Embed regulatory scenario planning into technology selection: Choose platforms that are adaptable to incoming policy requirements on recycled-content verification and chain-of-custody reporting; digital traceability features will become differentiators in procurement evaluations.
-
M&A and partnership playbooks: For firms evaluating inorganic growth, target capabilities that fill gaps in service coverage, regional distribution, or sensor expertise. The value in tuck-ins often accrues through installed-base service revenues and faster local commissioning.
What the PW Consulting report delivers — practical contents for 2026 execution
This study is deliberately designed as a practitioner’s toolkit. The full report includes:
-
Market-sizing and forecast models with transparent methodology tied to policy and macro scenarios.
-
Vendor scorecards that evaluate technology, service footprint, upgradeability, and commercial models.
-
CapEx/Opex modelling templates and ROI calculators that let procurement teams compare configurations under customizable feedstock and labor-cost assumptions.
-
Operational playbooks for pilot design, acceptance testing, and ramp-to-scale, including checklists for sensor validation, ejector maintenance, and model-retraining cadence.
-
Regulatory impact matrices and compliance timelines keyed to major markets — a tool to align procurement horizons with policy enforcement dates.
-
Scenario-based strategic options (buy, lease, service-contract, or hybrid) supported by sensitivity analyses and risk-mitigation checklists for supply-constrained components.
-
Case studies and supplier negotiation playbooks informed by trade-show reveals and recent commercial rollouts; practical templates for statements of work and performance acceptance criteria.
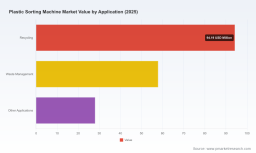
Note: This preview intentionally omits granular region-by-region and application-level splits. The full report contains the complete segmentation tables, regional demand matrices, and unit economics by application that underpin our recommendations.
Next steps for decision-makers in 2026
Executives and procurement leads should treat the next 12–18 months as a window of strategic choice: invest early to secure supplier capacity and upgrade pathways, or plan for phased deployments tied to regulatory milestones and feedstock maturation. Our analysis shows a market trajectory that rewards early movers with optimized feedstock economics and lower long-run OPEX, but also penalizes rushed procurements made without component-risk mitigation or service assurances.
Access the full intelligence
For teams preparing capital and operational plans in 2026, the full PW Consulting Plastic Sorting Machine Market report provides the data, tools and vendor intelligence to convert market growth into operational advantage. The preview above highlights the strategic levers; the complete study contains the granular models and negotiation tools you will need to execute.
For detailed analysis of this topic, please visit the official page: Plastic Sorting Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com