

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Formwork Market Set to Expand at 5.95% CAGR Through 2032

Formwork Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused, forward-looking introduction to our new Formwork Market research—designed to support executive decisions throughout 2026. This preview distills the study’s strategic implications and highlights how major industry forces will shape capital allocation, product strategy, and commercial models over the coming investment cycle. It deliberately signals the kind of rigorous, data-driven guidance contained in the full report while preserving granular segment detail to encourage direct access to our complete dataset and playbooks.
Formwork Market
Market Snapshot: Scale, Trajectory, and Market Structure
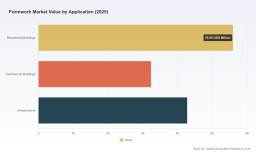
The formwork market has moved from niche contractor inventory to a strategic lever for productivity and risk management across construction portfolios. On a macro basis, the market recorded a clear recovery and expansion in the first half of the decade: total industry revenues rose from USD 98.0 Million in 2020 to USD 131.15 Million in our base year of 2025. Looking ahead, our forecast for 2026–2032 anticipates a steady compound annual growth rate (CAGR) of roughly 5.95%, reaching approximately USD 197.08 Million by 2032.
Formwork Market
Market concentration is meaningful: the top three players control a majority share (CR3 ~65.2%), while the top five capture near 78.4% of the market. For executives, that implies a dual dynamic—market leadership is consolidated enough that scale and system breadth matter, yet opportunities exist for focused innovation, regional engineering services, and rental-service hybrids to capture pockets of outsized margin.
Formwork Market
Why This Report Matters for 2026 Decisions
-
Investment Prioritization: With predictable mid-single-digit growth, capital deployed into product modularity, lightweight systems, or digital planning tools must be justified by clear ROI curves—our report provides scenario-modeled payback timelines across typical project types and utilization rates.
-
Supply Chain & Cost Management: The market’s margin profile will be sensitive to raw material volatility and regulatory-driven safety costs. We map cost-to-completion impacts under multiple commodity and tariff scenarios so procurement teams can hedge or redesign.
-
Commercial Reconfiguration: As construction firms prioritize speed and safety, rental-and-services models are gaining traction. We offer commercial playbooks that quantify when to lease, sell, or provide managed-services to maximize lifetime value of formwork assets.
-
M&A and Partnership Targeting: Given the concentration metrics, acquisition remains a viable path to scale for mid-market firms. The report identifies archetypal targets and integration risks aligned to different strategic intents: geographic roll-up, capability expansion, or digital platform consolidation.
Key Dynamics Shaping 2026 Strategy
-
Regulatory & Safety Pressure: Recent enforcement and standard updates place formwork handling squarely within tightened site-safety regimes. Updated regulatory emphasis on fall protection, scaffolding inspections, and expanded injury recordkeeping raises the cost of non-compliance—and increases the value of formwork systems that demonstrably reduce exposure and inspection time. Expect safety-driven differentiation to translate into procurement premiums for documented, certifiable systems.
-
Material Input Shocks: The supply chain remains a live risk. Steel mill product prices have risen materially in the latest cycle due to tariffs and constrained capacity, increasing replacement and repair costs for steel-intensive systems. At the same time, polymer feedstock cycles have shown elevated year-over-year variability. Our stress-tested scenarios quantify how these inputs impact lifecycle cost per pour for common system archetypes.
-
Digitalization and Productivity: Digital planning and BIM-aligned tools are no longer optional. Leading system providers are embedding planning software and logistics optimization to shorten setup times and minimize on-site labor. Such integration improves utilization rates and enables servitization—turning one-time equipment purchases into recurring revenue streams through managed deployment.
-
Product Innovation Focus: Lightweight materials, modular grids, and rapid-climb capabilities are shifting total cost equations. Innovations that reduce cycle time per lift or decrease labor intensity yield outsized commercial impact in high-wage markets; conversely, cost-effective expansions of aluminum lines can unlock volume in high-density housing programs in emerging regions.
Competitive Landscape: Who Moves the Market—and How
The competitive field blends deep global incumbents with nimble regional specialists. Our analysis synthesizes strategic positioning across engineering depth, product breadth, and service models—without disclosing market share breakdowns here.
-
PERI Group (Weißenhorn, Germany): PERI’s strength lies in modular grid systems and heavy-duty solutions for high-rise and infrastructure projects. Their recent launches emphasize safety and efficiency in large-scale pours, supporting clients seeking speed and predictable scheduling.
-
Doka GmbH (Amstetten, Austria): Doka pairs traditional formwork rigour with digital planning tools. Their focus on wall and slab systems, combined with software integration, positions them as a partner for contractors prioritizing design-to-delivery optimization.
-
ULMA Construction (Oñati, Spain) & MEVA (Haiterbach, Germany): Both emphasize aluminum and modular solutions. ULMA’s intent to expand aluminum lines targets mass-housing demand in growth markets, while MEVA’s lightweight systems cater to fast-repeat residential cycles and rental fleets.
-
RMD Kwikform, Altrad Group, and BrandSafway: These players strengthen the rental-and-services channel and support heavy civil workloads; their capability to bundle engineering services with equipment rental is a decisive competitive lever for major infrastructure programs.
-
Regional Specialists (EFCO, PASCHAL, NOE, Faresin, Pilosio, and others): These firms compete on tailored engineering, national code familiarity, and lower-cap-ex models for local contractors. They are often ideal partners for co-development or bolt-on acquisitions for firms seeking geographic densification.
Recent market activity reinforces these trends: product launches and trade-show demonstrations from major suppliers indicate a push toward modular grid systems and integrated planning tools; aluminum system expansions target faster cycles and affordability in volume housing; and new digital suites promise to tighten the planning-to-site handoff. These moves validate our view that performance improvement, not raw price competition, will drive differentiation in 2026.
Practical Playbooks and What the Full Report Delivers
This report is built to be operational. Senior teams will find:
-
Strategic Heatmaps: Visual prioritization of market opportunities by project type and risk profile, enabling rapid alignment of R&D and commercial resources.
-
Unit-Economics Templates: Build-your-own calculators for lifecycle cost per pour that incorporate material-price scenarios, labor rates, utilization, and safety compliance costs.
-
Go-to-Market Frameworks: Roadmaps for transitioning from product sales to hybrid rental-and-service models, including pricing playbooks and channel adjustments for different market maturities.
-
M&A and Partnership Diagnostics: Due-diligence checklists and integration risk templates tailored to the formwork industry’s engineering, inventory, and certification complexities.
-
Implementation Sprints: 90/180/365-day action plans for operationalizing digital planning, pilot deployments of modular systems, and cost-savings programs across procurement and logistics.
Signal Detection: Red Flags and Opportunity Triggers
-
Red Flags: Accelerating steel price inflation, tightened safety enforcement, and lagging digital adoption among mid-sized contractors; these can compress margins and elongate sales cycles.
-
Opportunity Triggers: Large public-housing tenders, infrastructure spending renewals, and OEM product launches that materially cut on-site labor hours—all create windows to scale service contracts and rental fleets rapidly.
How to Use This Preview in 2026 Planning
Use this document to orient board-level discussions on where to allocate R&D spend, whether to accelerate servitization pilots, and which external capabilities to seek through partnerships or acquisition. Teams focused on procurement should prioritize scenario-based hedging strategies and supplier segmentation. Meanwhile, sales and product leaders should treat safety certification and digital integration as commercial differentiators—features that justify premium contracting terms in bid packages.
Next Steps: Accessing the Full Intelligence
This preview outlines the backbone of our analysis: robust historical growth across 2020–2025, a clear mid-single-digit CAGR through 2032, concentrated market power among established global players, and a high-priority set of strategic moves that winners will make in 2026. The full PW Consulting Formwork Market Report contains the granular segmentation, regional demand matrices, supplier profiles, scenario-modeled ROI tables, and execution playbooks you’ll need to act decisively. For leaders ready to convert insight into action, the complete dataset and implementation materials are available through our research portal.
PW Consulting stands ready to support tailored strategy workshops, M&A screening, and pilot design—contact our industry team to schedule a briefing and to obtain the full report.
For detailed analysis of this topic, please visit the official page: Formwork Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com