

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pharmaceutical ethanol to hit USD 1.21M in 2026 at 6.5% CAGR

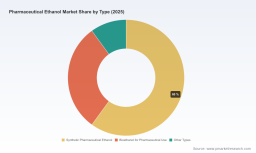
Pharmaceutical Ethanol Market — Strategic Briefing for 2026 Decision-Makers
Executive trailer: why this matters for 2026 strategy
Pharmaceutical-grade ethanol sits at an unusual intersection of commodity volatility, tight regulatory quality requirements, and accelerating demand from both traditional pharmaceuticals and novel biologics manufacturing. Between 2020 and our base year 2025 the market demonstrated steady expansion, and our forecast through 2032 projects continued growth at a compounded annual growth rate (CAGR) of 6.5%. The global market—traced across a six-year historical window and modeled for a seven-year forecast horizon—provides a clear signal: supply chain resilience, quality assurance, and strategic capacity allocation will be differentiators for industry leaders in 2026 and beyond.
Pharmaceutical Ethanol Market
What this briefing gives you (and what the full report delivers)
- High-confidence macro trajectory: clear, auditable market sizing from 2020–2025 and modelled outcomes to 2032 that reflect demand drivers, feedstock dynamics and regulatory scenarios.
- Operational playbooks for procurement, inventory and contract design that convert market insight into actionable 12–36 month measures.
- Competitive and capacity intelligence on leading producers, recent strategic moves and near-term commissioning projects that materially affect regional supply balances.
- A disciplined risk matrix with scenario-trigger thresholds to inform hedging, supplier diversification and capex timing.
Note: this is a deliberately condensed overview designed to show the depth of analysis you will need to act in 2026. Granular tables, region-by-region forecasts, application-level breakdowns and supplier scorecards are intentionally omitted here to preserve the strategic “trailer” — they are available in the full PW Consulting report.
Pharmaceutical Ethanol Market
Market pulse: the macro story in plain terms
From 2020 to 2025 the market expanded steadily, reflecting a combination of recovering pharmaceutical production after pandemic disruptions, recurring demand for sanitization products, and the steady ramp of biopharma manufacturing capacities globally. The market size at the 2025 base year and the trajectory to 2032 indicate not only growth but compounding structural shifts: feedstock substitution pressures in some geographies, regulatory harmonization in others, and a persistent premium for pharmacopeial-compliant supply chains.
Pharmaceutical Ethanol Market
Our central forecast to 2032—anchored on the historical series through 2025—assumes a baseline CAGR of 6.5%. Under this central scenario the market nearly doubles over the forecast window, creating compelling upside for suppliers able to combine regulatory-grade production with dependable logistics and quality management.
Where value will emerge in 2026
- Procurement sophistication: Buyers who move from spot-centric buys to blended strategies (term contracts + strategic spot exposure + regional inventory hubs) will reduce effective landed cost and de-risk disruptions.
- Quality and regulatory assurance as commercial moat: firms able to demonstrate consistent supply of pharmacopeial-grade ethanol (USP/EP/BP) at scale will command premium access to high-growth pharmaceutical manufacturing customers.
- Logistics and local presence: distribution hubs and local inventory will shorten lead times and reduce stock-out risk — a tactical advantage where lead-time reliability is valued over incremental price savings.
- Sustainability and feedstock transparency: customers (particularly in Europe and APAC) increasingly price in lifecycle emissions and feedstock traceability; producers with certified low-carbon pathways will win longer contracts.
Competitive landscape — who matters and why
The market exhibits moderate concentration, with the three- and five-firm concentration ratios signalling a balance between incumbent scale advantages and room for regional specialists to win. This structure creates a market where targeted investments can shift competitive positions meaningfully within 12–24 months.
- Greenfield Global Inc. (Toronto) — a producer/distributor focused on high-purity USP/EP/BP ethanol, with dedicated high-purity distilleries and a growing logistics footprint. Recent establishment of a distribution hub in the UK strengthens its ability to serve pharma, biotech and life-sciences customers with shorter lead times.
- Archer Daniels Midland Company (ADM) — an established supplier with deep commodity and processing expertise, supplying pharmacopeial-grade ethanol to a broad set of pharmaceutical applications. ADM’s integration across feedstock sourcing and processing remains a competitive advantage for scale and reliability.
- Godavari Biorefineries Limited (Hyderabad) — a regional manufacturer expanding capacity into pharmaceutical grades. The commissioning of a new grain-based distillery expected in early 2026 signals near-term supply additions that will alter regional availability and price dynamics.
- United Beta Industries (Saudi Arabia) — a fully domestic producer focused on 99.9% pharma and medical grade ethanol, compliant with European pharmacopoeia standards. Its geographic positioning and product specifications make it a strategic supplier for regional markets seeking secure, compliant sources.
These players illustrate the mix of scale, regional specialization and quality-focused niches that define competitive advantage. Tactical moves such as distribution hub launches and capacity commissionings are not merely incremental; they change lead-time economics and bargaining dynamics with large pharmaceutical buyers.
Supply-side dynamics and short-term shocks to watch
- Feedstock volatility: grain and molasses prices can shift feedstock economics quickly; scenario planning should include both price spikes and allocation-driven supply shortfalls.
- Regulatory shifts: tighter pharmacopeial interpretations or additional documentation requirements (e.g., traceability, contamination testing) can raise cost-to-serve and create temporary bottlenecks for marginal suppliers.
- Logistics and local stock: distribution hubs materially reduce exposure to ocean freight volatility, and the recent hub investments we’ve tracked demonstrate this is a prioritized commercial lever.
- Capacity additions: near-term commissioning projects will adjust regional balances; buyers and investors need forward-looking tracking to assess where temporary oversupply or under-supply may emerge.
Practical, 90-day to 24-month actions for 2026
- 90-day: Conduct a supplier risk heatmap and implement minimum dual-sourcing thresholds for any single-source pharmacopeial ethanol line items. Require proof-of-production and lead-time SLAs for prioritized suppliers.
- 6–12 months: Negotiate blended contract structures tying volume tiers to price collars and delivery windows. Pilot a regional inventory hub where lead-time or quality failures have highest operational impact.
- 12–24 months: Explore strategic partnerships or minority investments in high-integrity regional producers to secure preferential capacity access. Integrate lifecycle emissions accounting into procurement scorecards to protect market access in sustainability-conscious geographies.
Report contents — what to expect in the full PW Consulting study
The full report contains the granular data and tools your team will need to operationalize the strategic directions above. Highlights include:
- Comprehensive historical market sizing (2020–2025) and detailed forecast (2026–2032) with scenario variants and sensitivity testing.
- Region and application level demand models, with service level and price-elasticity matrices to support procurement optimization.
- Supplier scorecards and manufacturing footprint mapping, including quality certifications, capacity, and recent investments.
- Practical templates: procurement contract language, inventory sizing calculators, an M&A diligence checklist and integration playbooks for acquiring production capacity.
- Regulatory and compliance tracker aligned to pharmacopeia updates, plus an emissions accounting framework for ethanol feedstocks and production processes.
Why PW Consulting’s approach reduces 2026 execution risk
We combine quantitative market modelling with field-verified supplier intelligence and operational playbooks. That allows executives to translate market forecasts into executable procurement, sourcing and M&A decisions without getting lost in purely academic forecasts. The concentration metrics and the visible supplier moves we monitor (distribution hubs, greenfield commissionings) have direct operational implications for lead times, contract design and inventory strategy.
Final note — the trailer’s promise
This briefing is a strategic preview designed to show the depth of our analysis and the immediate actions it supports. To preserve the commercial integrity of our client-grade work and to provide the tactical datasets you need to act, we have withheld the granular region/application tables and the full supplier scorecards from this summary. The full PW Consulting Pharmaceutical Ethanol Market report includes those datasets plus downloadable models and procurement templates intended for direct use by commercial and supply-chain teams in 2026.
To access the complete market model, supplier dossiers, scenario tools and operational playbooks, please refer to our full report on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Ethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com