

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Guide Wires Market to Reach USD 2,204M by 2032 at 6.5% CAGR

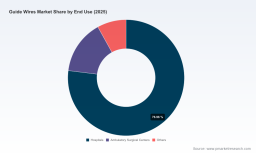
Guide Wires Market: Strategic Guideposts for 2026 Decision-Makers
Executive teaser
As healthcare systems recommit to minimally invasive care pathways and device makers pursue material and functional innovation, guide wires sit at the intersection of procedure economics, device engineering, and regulatory nuance. PW Consulting’s Guide Wires Market Guide frames the market as both a stable growth opportunity and a strategic battleground for the coming investment cycle. Using a 2025 base year and a forecast horizon through 2032, our model projects continued expansion at a compound annual growth rate (CAGR) of 6.5% (2026–2032), building on a market that grew from roughly USD 1,024.6 Million in 2020 to USD 1,430.0 Million in 2025. For executives making product, commercial, and M&A decisions in 2026, the implications are immediate: choose where to invest not only for incremental share but for durable value creation as clinical practice and regulation evolve.
Guide Wires Market
Why this matters for 2026 planning
2026 will be a turning point for several strategic reasons. First, procedure volumes for cardiology, vascular, neurovascular and adjacent specialties are recovering and structurally increasing as aging populations and expanded indications push more patients toward catheter-based interventions. Second, materials and coating technologies—especially nitinol cores, PTFE coatings, and advanced hydrophilic polymers—are enabling differentiated device performance, which in turn creates premiumization opportunities. Third, the competitive field is concentrated: the top 3 players command a significant portion of the market while the top 5 increase that dominance further, producing a market dynamic where scale, regulatory know‑how, and distribution reach meaningfully affect margins and access.
Guide Wires Market
What the macro numbers tell us (and what they don’t)
Reading headline figures alone can be misleading. The market’s trajectory—rising from roughly USD 1,024.6 Million in 2020 to USD 1,430.0 Million in 2025, and expected to continue growing at ~6.5% CAGR through 2032—confirms robust industry demand. Yet the real strategic value lies beneath those totals: which products are premiumizing, where reimbursement and coding shifts change procedure economics, and which regulatory clearances are lowering time‑to‑market for novel designs. This guide demonstrates how to translate aggregate growth into concrete choices—portfolio prioritization, contract negotiation levers, and M&A target screening—while preserving proprietary segmentation detail for subscribers to the full report.
Guide Wires Market
Market dynamics and regulatory context
-
Regulatory profile: Guide wires are regulated as Class II devices in the US (21 CFR 870.1330) and typically require 510(k) clearance to market. Manufacturers must maintain rigorous sterilization processes—typically validated ethylene oxide (EtO) cycles consistent with ISO 11135 and sterility assurance levels around 10^-6—and meet ISO 10993‑1 biocompatibility standards for blood‑contact devices. These requirements shape product development timelines, submission strategies, and manufacturing footprints.
-
Reimbursement and coding: Interventional radiology and catheter‑based procedures involving guide wires are subject to evolving CPT code assignments and physician fee updates. For 2026, updated CPT code guidance impacts procedure economics and therefore purchasing behavior in hospitals and ambulatory surgical centers. Manufacturers must align health economic messaging to these reimbursement realities when engaging payers and hospital procurement teams.
-
Supply‑chain realities: Material inputs—nitinol, stainless steel alloying elements, PTFE, and hydrophilic coatings—are critical constraints. Sourcing strategies, multi‑sourcing, and qualified second‑source roadmaps are practical levers to mitigate single‑supplier risk and to preserve time‑to‑market for differentiated products.
Competitive landscape — snapshot analysis
The guide wires market combines global incumbents with agile specialists. Below we summarize strategic positions of the major participants covered in the study. These vignettes highlight where incumbents compete and where white space exists; the full report contains detailed capability matrices, patent landscaping, and manufacturing capacity maps.
- Boston Scientific Corporation — Established strength in cardiovascular and peripheral guide wires, with a product portfolio emphasizing hemodynamic and pressure sensing wires. Competitive advantages include integrated product suites and broad clinician relationships in interventional cardiology.
- Medtronic plc — Large global reach and operational scale; strengths in vascular access and diagnostic guidewire variants. Medtronic’s advantage is its ability to bundle access devices with complementary therapies and capitalize on global distribution networks.
- Abbott Laboratories — Focused on interventional cardiology and pressure/FFR guidance technologies. Abbott leverages diagnostic analytics and clinician education programs to drive adoption of higher‑value guidewire use cases.
- Terumo Corporation — Strong hydrophilic wire technologies and deep penetration in key Asia and European markets. Terumo’s engineering focus on low friction profiles supports its competitive position in vascular access.
- Cook Medical — Niche and specialty guidewire offerings with an emphasis on PTFE coatings and procedural innovation. Cook’s flexible commercial model targets specialty and complex case segments.
- Asahi Intecc Co., Ltd. — Leader in nitinol guidewire technology and crossing systems for peripheral and neurovascular interventions; high R&D intensity and targeted clinical collaboration distinguish its product roadmap.
- Argon Medical Devices, Inc. — Broad interventional radiology portfolio with an emphasis on cost‑effective, procedure‑centric wire designs favored in high‑volume settings.
- Imperative Care, Inc. — Smaller, fast‑moving player focused on shapeable‑tip and access innovations. Notably, Imperative Care received FDA 510(k) clearance for its X‑Wire guidewire (August 2025), accelerating its ability to compete in peripheral and neurovascular use cases.
- Atraverse Medical, Inc. — Developing RF‑integrated and transseptal solutions; positions itself at the intersection of guidewire functionality and procedural efficiency.
- B. Braun Melsungen AG — Longstanding portfolio in angiography and PTCA guidewires with global OEM relationships and depth in hospital channels.
- Shenzhen Hainwise Medical Technology Co., Ltd. — Cost‑competitive portfolio and ISO 13485 manufacturing credentials support emerging market penetration and OEM partnerships.
- Acme Monaco — Specialist nitinol‑core hydrophilic designs oriented to catheter exchange and vascular access workflows.
Recent regulatory and product developments with strategic implications
-
FDA clearances: Recent 510(k) clearances—such as Imperative Care’s X‑Wire (Aug 2025) and a micro guidewire clearance by Peijia Medical (Mar 2026)—lower market entry barriers for specific differentiated designs and shift competitive dynamics in the peripheral and neurovascular segments. These clearances also illustrate the accelerating cadence of incremental device innovation that buyers now expect.
-
Standards and compliance: Expect increasing scrutiny on sterilization validation, biological safety testing, and supply traceability. Compliance investments are non‑negotiable and represent ongoing cost centers that must be planned into 2026 operating budgets.
What PW Consulting’s Guide contains — practical, transaction‑ready deliverables
The full Guide Wires Market report is built for decision‑makers and operators, not just analysts. Highlights include:
-
A transparent market model (2020–2032) with downloadable worksheets in Million USD, adaptable with client assumptions for bespoke forecasting.
-
Scenario analyses that stress test policy, reimbursement, and supply‑chain shocks—useful for investment committees and risk registers.
-
Competitive playbooks and capability matrices for each major vendor, including patent and quality inspection heatmaps, go‑to‑market positioning, and partnership vectors.
-
Commercial activation assets: value‑capture frameworks, hospital procurement negotiation scripts, pricing sensitivity grids, and sample 100‑day post‑acquisition plans.
-
Regulatory and clinical checklist: stepwise 510(k) playbook, recommended biocompatibility testing matrices (ISO 10993‑1 alignment), and validated EtO sterility protocol benchmarks (ISO 11135 considerations).
-
Manufacturing and sourcing analysis: supplier concentration scoring, dual‑sourcing templates, and CAPEX guidance for wave solder/assembly and coating lines.
-
M&A and portfolio prioritization tools: a proprietary target scoring model that evaluates strategic fit, revenue synergies, regulatory readiness, and integration complexity.
Strategic imperatives for 2026
-
Invest in differentiated performance: Prioritize coatings and core metallurgy that demonstrably reduce friction or enable new procedure techniques; payback horizons in premium segments justify targeted R&D investment.
-
Design regulatory‑first roadmaps: Build submission timelines into product development life cycles and allocate compliance resources early—this shortens commercialization lead times and preserves pricing power.
-
Secure supply resilience: Lock in multiple qualified suppliers for nitinol and coating chemistries; consider dual manufacturing footprints if clinical and regulatory strategies span US and EU markets.
-
Be surgical in M&A: Look for bolt‑on players that provide complementary product technologies, clinical access, or cost synergies rather than broad market rollups; the current concentration favors strategic consolidation where operational synergies are real.
-
Align commercial models to care settings: Differentiate go‑to‑market approaches for hospitals versus ambulatory surgical centers and tailor economic value propositions to the buyer’s procedure volumes and reimbursement environment.
Next steps — how to convert insight into action
This executive brief intentionally highlights strategic conclusions and the most consequential operational levers. It withholds the full granular segmentation tables, regional and application splits, and downloadable Excel models to preserve the value of the proprietary dataset in the complete Guide Wires Market report. PW Consulting can provide tailored briefings, validation workshops, and integration planning sessions that convert model outputs into a 90‑day action plan for product, commercial, regulatory or M&A teams.
For teams preparing budgets, vendor strategies, or transaction pipelines in 2026, this Guide is designed to be the operative reference. Request a demonstration of the underlying forecast model, competitor scorecards, and the transaction playbook to move from insight to executable strategy.
For detailed analysis of this topic, please visit the official page: Guide Wires Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com