

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tire Retreading Market—USD 230M in 2025, 5.72% CAGR to 2032

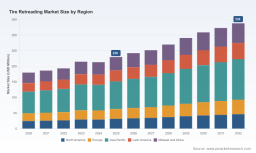
Tire Retreading Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, action-oriented introduction to our full Tire Retreading Market study. This briefing distills the evidence-based direction of the market through 2032 and highlights the strategic implications executives must factor into 2026 planning cycles. The intent is to demonstrate analytical depth and operational relevance while reserving the granular segmentation and proprietary forecasts for the full report.
Tire Retreading Market
Market Trajectory — What the Numbers Tell Us
The tire retreading market is at a clear inflection point. Using 2025 as our base year, the market is estimated at approximately 230 Million USD and is projected to expand at a compounded annual growth rate (CAGR) of 5.72% over the 2026–2032 forecast horizon. By 2032 our topline projection approaches the mid-hundreds in Million USD, reflecting sustained demand driven by fleet economics, tighter sustainability requirements, and technology-enabled productivity gains.
Tire Retreading Market
Historical performance (2020–2025) shows resilience through commodity cycles and macro shocks, with the sector rebounding from near-term volatility into a structurally higher growth path. For executives, the takeaway is unambiguous: retreading is shifting from a strictly cost-driven tactic to a strategic lever for resiliency, emissions reduction, and total-cost-of-ownership optimisation across commercial vehicle operators.
Tire Retreading Market
Key Growth Drivers
- Fleet economics and total cost-to-serve: With pressure on operating margins, fleet operators increasingly prioritize retreading to extend tire asset life and reduce replacement frequency. Retreading converts capital outlays into predictable service and lowers per-mile tire costs when integrated with telemetry and planned maintenance.
- Sustainability and regulatory momentum: Retreading delivers measurable environmental benefits — lower energy input per tire, materially reduced raw material consumption per unit, and lower lifecycle emissions versus new manufacture. Regulators and procurement policies that reward lower embodied carbon are elevating retreading in public and private tenders.
- Technology and automation: Advances in precured and mold-cure processes, non-destructive inspection (visual and electronic), and digital traceability (RFID, blockchain pilots) are improving yield, safety profiles, and the appeal of retreaded products to risk-averse fleet managers.
- Service model evolution: Bundling retreading with tire asset management, telematics, and performance-based contracts is expanding addressable spend beyond the initial retread unit — creating recurring revenue streams for operators and suppliers.
Cost, Materials and Environmental Leverage
From a resource perspective, retreading delivers outsized leverage: on average, a retread consumes substantially fewer raw materials and energy than a new tire, with industry analyses showing single-unit oil and material savings and a marked reduction in energy intensity. These efficiencies translate to both direct cost savings for fleets and reputational/ESG benefits for manufacturers and buyers. For example, the process reduces energy consumption by roughly one-third in comparative production scenarios, and a single retread typically requires significantly less oil than manufacturing a new commercial tire.
Beyond unit economics, the retreading value chain is a major employer and industrial anchor. It supports a sizeable workforce directly involved in remanufacturing and an extended supplier network. This social and operational footprint strengthens the argument for continued public and private support of retreading as part of circular-economy initiatives.
Quality, Safety and Regulatory Context
Quality control remains a critical market gate. Leading manufacturers maintain certifications and stringent quality controls to ensure retreaded tires meet safety benchmarks; regulatory bodies and independent testing consistently show that properly retreaded and maintained tires can provide reliability comparable to well-maintained new tires. This quality assurance is a prerequisite for wider adoption among risk-averse fleet operators and for entry into regulated procurement channels.
Competitive Landscape — Strategic Profiles
The market structure combines global OEMs with deep technical capabilities and a broad network of retread operations, alongside specialised technology and materials suppliers, and regional independents that excel in service proximity and custom solutions. Competition is best understood through capability clusters rather than pure market share alone:
- Global OEMs with integrated networks: Major tire manufacturers operate extensive retread plants and proprietary retread programs designed to deliver branded, high-consistency retreads supported by scale manufacturing, R&D, and logistics. Their strategies emphasize premium product lines, global distribution, and integrated fleet service offers.
- Technology and materials specialists: Firms focusing on precured treads, mold technology, and advanced resurfacing materials are defining performance differentials — from splice-less designs to abrasion-resistant compounds and optimized casing repair systems.
- Regional independents and service specialists: These players compete on speed-to-asset, local service coverage, and bespoke retreading solutions, winning business through close fleet relationships and rapid turnarounds.
Notable industry participants profiled in our study include established global OEMs with deep R&D footprints, premier retread process innovators, and leading regional service providers. Each has pursued different strategic plays: product innovation (new tread architectures and precured systems), capacity investments and automation, and service-model extensions into full-service fleet management. Recent company moves reflect an emphasis on automation, capacity realignment for regional demand, and extension of premium retread ranges tailored to key fleet segments.
Recent Industry Movements — What They Signal
- Capital and capacity reallocation: Several global and regional players have announced capacity and automation upgrades to reduce unit costs and improve throughput. These moves indicate confidence in medium-term demand and a race to capture scale-efficiency advantages.
- Product portfolio expansion: R&D-led rollouts of new precured and mold-cure offerings target fleet managers seeking near-new performance at lower cost. The productization of retread options — including nominative hot retreads and splice-less solutions — is lowering adoption barriers.
- Process digitization and traceability: Adoption of RFID and digital tracking is starting to tie retread units into telematics and fleet maintenance systems, improving lifecycle visibility and enabling performance-based contracting.
Operational Playbook — What the Full Report Delivers
Our full report is built for decision-makers who need executable intelligence. It contains:
- Actionable go-to-market scenarios for OEMs, materials suppliers, and service chains — including playbooks for premiumization, regional expansion, and service bundling.
- Operational benchmarks and process-improvement templates (yield, throughput, inspection pass rates) that facilities can deploy to lift margins quickly.
- Commercial frameworks to design performance-based contracts linking retread warranties to telematics and maintenance protocols.
- Risk matrices and regulatory checklists tailored to procurement teams and compliance functions.
- A curated M&A and partnership heatmap identifying where to buy capabilities versus where to partner for technology or scale.
Strategic Imperatives for 2026
As firms finalize 2026 budgets and three-year plans, the retreading market requires a nuanced set of responses:
- Prioritize integration of retreads into TCO models: CFOs and fleet managers must model retread adoption in scenario analyses tied to fuel, labor, and downtime variables. Retreading should be positioned as a service-enabled cost and emissions control lever rather than an ad-hoc procurement choice.
- Invest selectively in automation and traceability: Capital allocation should target technologies that improve first-pass yield and reduce manual inspection variance. Traceability investments unlock contractual relationships with large fleets and support premium pricing.
- Differentiate via product and service pairing: Premium retread offerings will win where they are bundled with fleet management, warranty alignment, and performance analytics.
- Scan M&A and partnership targets: Where regional service density or specialized tread technologies are gaps, consider acquisition or strategic partnerships to accelerate market access.
- Align on sustainability credentials: Marketing and procurement teams should quantify lifecycle benefits of retreading to capture both financial and ESG procurement value.
How PW Consulting Can Support Your 2026 Agenda
The full PW Consulting study provides the granular segmentation, regional demand matrices, application-level demand drivers, supplier scorecards, and a prioritized implementation roadmap tailored to your organization’s operating model. It also contains a downloadable toolkit with negotiation templates, facility upgrade checklists, and a vendor short-list customized for different strategic intents (scale-up, premiumization, or regional consolidation).
We purposefully withheld detailed segmentation metrics in this briefing to preserve the value of the full study; the complete dataset includes proprietary demand curves and scenario-tested revenue implications at the region, application, and product-type levels that your strategy and commercial teams will need to execute with confidence.
Next Steps
For executives preparing 2026 budgets and strategy plans, retreading is no longer a tactical savings instrument — it is a strategic lever for cost, resilience, and sustainability. We invite procurement leaders, operations chiefs, and corporate strategists to access the full PW Consulting Tire Retreading Market report to obtain the segmented forecasts, supplier scorecards, and implementation roadmaps that translate market insight into executable plans.
Contact PW Consulting to receive the complete report and a complementary 60-minute briefing tailored to your specific operating footprint and strategic priorities.
For detailed analysis of this topic, please visit the official page: Tire Retreading Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com