

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Advanced Ceramics Market Poised for 6.1% CAGR Through 2032

Advanced Ceramics Market: Strategic Outlook for 2026 Decision‑Making
As companies prepare investment and portfolio decisions for 2026, the advanced ceramics sector presents a classic strategic inflection: accelerating end‑market demand driven by electronics, electrification, healthcare and aerospace converges with persistent supply‑side friction (raw materials, qualification cycles and capital intensity). PW Consulting’s Advanced Ceramics Market research frames this moment with a disciplined, executable lens — combining macro forecasts, supplier benchmarking and operational playbooks that convert market intelligence into boardroom actions. The summary below signals the line-of-sight we provide while intentionally withholding the transaction‑level segment tables that are available in the full report.
Advanced Ceramics Market
Why this report matters for 2026 planners
- Translate macro growth into choices: move from high‑level TAM forecasts to decisions about capacity, vertical integration and product mix.
- Reduce qualification risk: map multi‑year approval windows and design pragmatic acceleration paths for semiconductor and medical customers.
- Protect margins: model raw‑material volatility and contract structures that preserve profitability during periods of input price inflation.
- Target M&A and partnerships: identify non‑obvious targets and partnership archetypes that accelerate time‑to‑market or secure critical inputs.
Market trajectory — a concise macro snapshot
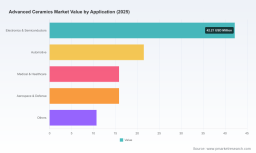
Our baseline view uses 2025 as the reference year. The advanced ceramics market expanded from roughly USD 79 million in 2020 to approximately USD 106 million in 2025. Under PW Consulting’s base forecast the market grows at a compounded annual growth rate of 6.1% over the 2026–2032 period, reaching an estimated USD 159 million by 2032. That pace reflects both structural demand — driven by higher frequency electronics, EV and energy systems, medical implants and high‑temperature industrial applications — and ongoing product innovations in non‑oxide materials and ceramic additive manufacturing.
Advanced Ceramics Market
Two structural features are particularly salient for strategic planners. First, market concentration is meaningful: the three largest firms account for a material share of global supply and the top five expand that presence further, creating oligopolistic pockets where scale and certified supply chains matter. Second, demand is unevenly distributed across use cases and materials, so portfolio positioning (premium, specialized components versus higher‑volume substrates) will determine which players capture above‑market returns.
Advanced Ceramics Market
Structural dynamics and supply‑chain constraints
- Raw material pressure: Inputs remain a key margin lever. Notably, bulk bauxite and metallurgical alumina import prices increased during 2025; metallurgical alumina unit costs moved higher year‑over‑year, reflecting pressure on refining and logistics. High‑purity alumina and specialty powders — necessary for many high‑performance ceramic grades — are a particular pinch point.
- Qualification and standards: ISO and industry‑specific standards create high barriers to entry. Quality and safety standards for bioceramics and the SEMI requirements for semiconductor components mean that vendors who win qualification enjoy multi‑year, sticky revenue streams. The implication is that go‑to‑market timelines must explicitly budget for protracted validation cycles.
- Capital intensity and geographic risk: Ceramic fabrication, finishing and sintering lines demand both capex and skilled process control. New capacity announcements in 2025–2026 point to selective regional investment, but geographic diversification of supply chains remains incomplete, exposing buyers to source concentration risk.
- Input concentration and strategic sourcing: Dependence on imported high‑purity feedstocks and some rare‑earth oxides creates vulnerabilities; firms are responding with hedging, long‑term offtake agreements and backward integration where economics permit.
Competitive landscape — what incumbents and challengers are doing
The sector combines global industrial incumbents and specialized engineering houses. Several recurring strategic moves are visible across leading players:
- Broad material portfolios and proprietary formulations: Established manufacturers with extensive material libraries retain advantages for custom applications and rapid product matching for electronics and industrial customers.
- Precision manufacturing and clinical focus: Firms targeting medical implants emphasize biocompatibility, traceability and automated production to compress qualification times and meet regulatory expectations.
- Partnerships and revenue diversification: Strategic alliances with OEMs — particularly in aerospace and next‑generation electronics — are accelerating innovation cycles and anchoring demand streams.
Representative company dynamics (select examples):
- CoorsTek, Inc. leverages a broad material portfolio and advanced substrates capability to target high‑frequency electronics while maintaining engineered solutions for aerospace and defense. Recent product launches in 2025 reinforce a go‑to‑market focus on higher‑value electronic substrates.
- KYOCERA Corporation is doubling down on precision ceramics and medical applications; its new automated medical ceramics facility in Germany (early 2026 startup) exemplifies a strategy that blends manufacturing automation with regulatory quality systems to scale implant production.
- Saint‑Gobain Ceramic Materials remains strong in high‑temperature and industrial segments, pairing refractory expertise with filtration and coating technologies that capture cross‑sell opportunities in chemical and energy sectors.
- CeramTec and Morgan Advanced Materials demonstrate specialization: CeramTec in medical and biocompatible components, Morgan in carbon/ceramic solutions for aerospace and semiconductors. Morgan’s 2025 partnership with an aerospace OEM shows how supplier‑OEM collaboration accelerates next‑gen ceramic adoption.
- Smaller specialists (e.g., non‑oxide specialists and bespoke manufacturers) are winning design‑in for demanding mechanical or thermal applications, but scale and feedstock security remain limiting factors for broad expansion.
Recent industry moves and what they signal
- Capacity expansions across several manufacturers in late 2025 and early 2026 indicate supply responses to EV battery and high‑frequency electronics demand, but they are targeted rather than broad — signaling selective rather than ubiquitous supply growth.
- Product launches focused on high‑frequency substrates and medical components show where margin pools are increasing and where lead customers are likely to consolidate procurement.
- Strategic partnerships between materials suppliers and OEMs are increasingly the fastest path to scale commercial adoption; formal alliances are appearing in aerospace and next‑generation electronic modules.
What the PW Consulting report contains — operational, ready‑to‑use modules
The full Advanced Ceramics Market report is structured to move executives from insight to implementation. Key actionable components include:
- Transparent market sizing and scenario models (base, upside and downside) with sensitivity levers for input prices, qualification timelines and end‑market adoption curves.
- Supplier benchmarking and a vetted due‑diligence checklist that scores capability across materials, finishing, traceability, and regulatory history.
- Raw‑material cost model and procurement playbook that quantifies exposure to alumina, specialty powders and rare‑earth oxides and prescribes hedging and supplier diversification tactics.
- Qualification path maps for semiconductor and medical buyers, including sample timing, testing milestones and recommended pilot program structures to shorten vendor approval cycles.
- Capacity‑planning templates and capex sizing tools tailored to ceramic process economics, yield assumptions and sintering throughput.
- M&A and partnership candidate shortlist with thematic rationales (technology access, market entry, feedstock control) and high‑level commercial rationale.
- Regulatory and standards timeline (ISO, SEMI, clinical) with impact assessments for new product introductions and market entry windows.
- Risk heatmaps covering supply concentration, input price volatility, and geopolitical exposure — with mitigation playbooks for procurement and site selection.
Decision framework for 2026 — five pragmatic moves
- Secure critical feedstocks: Negotiate long‑term offtake or invest in upstream capacity for high‑purity alumina and specialty powders to protect gross margins against cyclical spikes.
- Prioritize qualification acceleration: Co‑develop pilot programs and invest in joint validation phases with strategic OEM customers to shorten time‑to‑revenue and lock in multi‑year contracts.
- Choose focus between premium and scale: Decide whether to pursue premium, high‑margin niches (medical, high‑frequency electronics) vs. volume substrate plays (EV, industrial). Each requires different capex and go‑to‑market structures.
- Form targeted alliances: Use partnerships to access application knowledge, share qualification costs and distribute capital risk — particularly for aerospace and semiconductor programs with long lead times.
- Make contingency plans for raw‑material shocks: Build price indexation clauses, diversified sourcing and buffer inventories into commercial contracts.
Conclusion — the strategic value of this research in 2026
Advanced ceramics will be a material contributor to the next wave of electrification, miniaturization and medical device innovation. For 2026 decisions, the value of market intelligence lies in turning forecast numbers and structural diagnostics into executable steps: which plants to expand, which suppliers to partner with, how to price multi‑year contracts, and where to place M&A chips. PW Consulting’s report provides the scenario models, supplier intelligence and tactical playbooks necessary to make those choices with conviction.
To access the proprietary segment breakdowns, company‑level datasets and the full set of operational tools referenced here, consult the complete Advanced Ceramics Market report on PW Consulting’s portal — the release is designed as a working dossier for strategy teams, corporate development and procurement leaders who need both the macro context and the micro playbooks to act in 2026.
For detailed analysis of this topic, please visit the official page: Advanced Ceramics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com