

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Vertical Farming & Plant Factory Market to Grow at 23.71% CAGR — PW Consulting

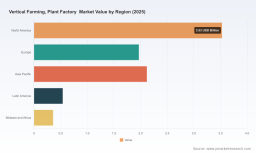
Vertical Farming & Plant Factory Market: Strategic Imperatives for 2026
As global supply chains remain stressed by climate volatility, urbanization, and changing consumer preferences for freshness and traceability, vertical farming and plant factories have shifted from experimental niches into boardroom conversations. PW Consulting’s latest market research — anchored on a 2025 base year, a detailed historical window (2020–2025), and forward-looking projections to 2032 — quantifies this evolution and translates it into operationally useful insight for executives making 2026 investment and portfolio decisions.
Vertical Farming, Plant Factory Market
Why this report matters for decisions in 2026
- Timing: The sector has entered a high-growth phase. After a steady build from 2020, 2024–2025 marked an acceleration in commercial-scale deployments and capital flows; our forecast path to 2032 implies persistent steep growth at a compound annual growth rate of 23.71%.
- Portfolio prioritization: Corporates must choose between asset-heavy scale-up, asset-light platform play, or hybrid partnerships. Each path has distinct capex, opex, and time-to-market trade-offs that the report models transparently.
- Risk calibration: Policymakers and lenders are sending mixed signals (targeted grant programs alongside tightened loan guarantees). Understanding how those policy vectors interact with unit economics is essential before underwriting new projects.
- Supplier & channel strategy: Suppliers of lighting, automation, and modular systems are becoming strategic partners to retailers and foodservice operators. The research highlights which partnership archetypes produce the fastest route to positive ROI.
High-level market trajectory and what it signals
Vertical farming’s total addressable market has expanded materially over the last half decade. Our compiled market series shows growth from an early-stage base in 2020 to a substantially larger commercial market by 2025, with a further projected maturation across 2026–2032. This trajectory — underpinned by a 23.71% CAGR over the forecast horizon — signals a multi-year window in which incumbent food producers, technology vendors, real estate owners, utilities, and strategic investors must decide whether to lead, follow, or selectively participate.
Vertical Farming, Plant Factory Market
The acceleration observed around 2024–2025 reflects three converging forces: (1) commercial operators proving repeatable, larger-scale economics for specific crop sets; (2) converging technology stacks (lighting, control systems, robotics) that materially improve yields and reduce labor intensity; and (3) concentrated buyer demand from retail and foodservice channels seeking local, year‑round supply. At the same time, the market remains capital-intensive and energy-sensitive, producing clear winners for those able to optimize systems and for strategic partnerships that lower capital outlays.
Vertical Farming, Plant Factory Market
Key dynamics shaping 2026 strategic choices
- Policy divergence: Targeted public grants have become more common even as certain lending windows have been temporarily tightened. Executives must model both forms of support — direct subsidies and constrained debt availability — into business plans and scenario analyses.
- Consolidation and concentration: The competitive landscape shows material concentration among a few leading operators and systems integrators. The market favors scale and repeatability for retail contracts and wholesale accounts; strategic M&A and partnership activity is expected to accelerate.
- Energy & labor as cost levers: Energy consumption is a dominant operating cost in high-intensity installations (our benchmarking places typical consumption in a multi-thousand kWh per square-meter annual range). Labor economics also vary by crop: leafy greens typically demonstrate lower labor cost per-pound relative to certain herb lines, which has direct implications for crop selection and automation investment.
- Technology convergence: Successful operators are combining advanced LED horticultural lighting, precise environmental control, data-driven growth recipes, and increasing levels of automation and robotics — shifting value from simple control systems to integrated hardware‑software-service bundles.
Competitive landscape — strategic placements to watch
The market now features a mix of specialist operators, systems suppliers, and technology vendors. Leading aeroponic and hydroponic operators have established routes to market with major retail partners and are demonstrating the commercial viability of scaled indoor production. Parallel to operators, a dense ecosystem of lighting suppliers, hardware integrators, and modular system manufacturers is emerging — each with distinct strategic implications:
- Operator-first players: Some firms have focused on large-scale controlled-environment farms, building direct retail and foodservice distribution. Their value proposition centers on scale, product consistency, and established offtake relationships.
- Technology/system suppliers: A second cohort sells modular systems, containerized farms, and integrated hardware-software stacks to third‑party operators and institutions. These vendors shorten time-to-market for new entrants and enable franchised or distributed supply models.
- Lighting & control specialists: Horticultural LED companies and control-system providers are increasingly the differentiators in yield-per-square-meter and energy efficiency. Strategic partnerships between lighting firms and systems integrators are becoming routine.
- Consolidators & aggregator plays: M&A activity — including purchases that consolidate modular system suppliers — is already evident and will likely continue as incumbents seek cost synergies and broader geographic reach.
For corporate strategists, the implication is straightforward: partnerships and selective M&A are the fastest paths to secure supply, capture margin, or normalize capex intensity. For suppliers, embedding services and data analytics into product offerings will reduce commoditization and increase customer stickiness.
Operational economics & practical levers included in the report
The full research translates high-level projections into operationally actionable instruments. Among the practical elements we provide:
- CapEx / OpEx models with sensitivity levers for energy pricing, labor productivity, and yield improvements.
- Site selection and real estate decision frameworks that balance proximity to demand, utility tariffs, and logistics costs.
- Energy benchmarking and load-management approaches, including on-site renewables and demand-response strategies to reduce effective cost per unit produced.
- Automation and process-design playbooks that show break-even points for robotics and labor-substitution investments across crop categories.
- Supplier scorecards and procurement frameworks to evaluate lighting, HVAC, and control system partners against a combined metric of yield, energy efficiency, and total cost of ownership.
- Regulatory and financing risk matrices reflecting the current policy environment: targeted grant support on the one hand, and constrained loan guarantees on the other.
Strategic recommendations for 2026 decision-makers
- Test-and-scale: Execute short, measurable pilots that validate crop recipes, yield per-square-meter, and retail acceptance before committing to large greenfield builds. Use pilots as learning assets to de-risk larger deployments.
- Prioritize energy optimization: Given the sector’s energy sensitivity, early wins come from investing in lighting efficiency, thermal management, and utility partnerships (including on-site generation where economics permit).
- Modularize growth: If capital is constrained or market access is uncertain, prefer modular/containerized models or JV structures with systems providers; they preserve optionality while enabling regional market penetration.
- Lock strategic offtakes early: Retail contracts and foodservice agreements compensate for higher unit costs in infancy. Structuring long-term offtake or revenue-share arrangements reduces market-entry risk.
- Plan for consolidation: Expect continued M&A; prepare to act as an acquirer to secure supply chains or as a seller if integrating vertical farming is not core to your strategy.
What the full PW Consulting report contains (select, non-exhaustive)
- Granular market models (base year 2025: historical 2020–2025; forecast 2026–2032) with scenario outputs tied to different energy and policy assumptions.
- Actionable ROI calculators you can run with your own input assumptions.
- Detailed supplier and competitor profiles with strategic implications, partnership archetypes, and acquisition targets to watch.
- Operational playbooks for site selection, crop mix optimization, and workforce transition strategies.
- Regulatory impact assessments and financing pathways mapped to different geographies and buyer segments.
Concluding perspective
For 2026, the vertical farming and plant factory sector presents both an accelerated opportunity and a nuanced risk profile. Growth is real and rapid — our market series shows a material increase in market scale through 2025 and a robust trajectory thereafter — but success is conditional on optimizing energy, securing offtake, and navigating a shifting policy landscape that currently mixes selective public support with tightened lending for certain models. The full PW Consulting study equips executives with the frameworks, modeled scenarios, and vendor-level intelligence required to make defensible, time-sensitive decisions: whether that means leading the next wave of scale, partnering to mitigate capital risk, or positioning your core business to benefit from local, controlled-environment sourcing.
For the detailed segmentation, country‑level analysis, and the proprietary modeling that underpins our recommendations, reference the full report and supporting tools available through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Vertical Farming, Plant Factory Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com