

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microbial Protein (Gaprin) Market - 9.6% CAGR to USD 3,078.16 Million by 2032

Microbial Protein (Gaprin) Market — A Strategic Preview for 2026 Decision‑Makers
As companies decide where to allocate capital and executive attention in 2026, microbial protein (Gaprin) is moving from niche innovation to mainstream commercial opportunity. PW Consulting’s new market study — built on a 2025 base year, a historical series through 2020–2025, and a projection window for 2026–2032 — models a compound annual growth rate (CAGR) of 9.6% across the forecast period. The market we modelled more than doubled in scale across the 2020–2032 timeline, rising from just over 1.0 billion USD in 2020 to a multi‑billion USD market by 2032. Notably, our 2026 checkpoint shows a material step‑up from 2025 levels, underscoring immediate strategic choices for investors, CPGs, feed producers and policy stakeholders.
Microbial Protein (Gaprin) Market
The strategic imperative in 2026
-
Timing matters: 2026 is a pivot year in which pilot facilities transition to commercial footprints. The investment and partnership decisions you make this year determine whether you capture scale‑economy benefits or pay a premium to retrofit later.
Microbial Protein (Gaprin) Market -
Cost and feedstock dynamics are in flux: energy, CO2 sourcing, methane affordability and access to side‑stream carbon will differentiate winners in unit economics and supply reliability.
Microbial Protein (Gaprin) Market -
Regulatory clarity and market acceptance are improving but uneven: approvals and novel‑food classifications in key markets remain a gating factor for food‑grade routes and premium positioning.
What our PW Consulting study delivers — practical intelligence for 2026 action
-
Robust market trajectory and scenario planning: base and alternative scenarios across 2026–2032 with sensitivity to energy, feedstock and regulatory timelines.
-
Actionable unit‑economics models: factory‑level capex and opex templates (editable), break‑even curves and margin ladders for different feedstocks and process technologies.
-
Commercial roadmap: go‑to‑market playbooks for B2B feed offtake, private‑label food launches and co‑branded pet nutrition products, including staged commercialization checklists.
-
Supply‑chain and site selection framework: criteria to evaluate co‑location with renewable power, industrial CO2 sources, natural gas availability and logistics hubs, plus a risk‑ranking matrix for energy exposure.
-
Regulatory navigator: market‑by‑market approval timelines, plausible gating points for novel foods and feed approvals, and recommended engagement sequences with regulators.
-
M&A and partnership playbook: target archetypes, valuation considerations, integration risks and templates for JV & offtake agreements.
-
Commercial datasets and dashboards: time‑series market sizing, demand curves by application cluster, and a “what‑if” scenario engine for CFOs and strategy teams.
Core market dynamics shaping 2026 decisions
-
Demand-side momentum: Appetite for alternative proteins in feed, pet and select food categories continues to accelerate as both consumer interest and commercial adopters broaden. Institutional buyers are beginning to include microbial solutions in sustainability procurement targets, which shortens sales cycles for proven product specifications.
-
Supply-side scale-up: Multiple production technologies — methane fermentation, hydrogen‑/electricity‑driven CO2 fixation and side‑stream fermentations — are moving from demonstration to industrial scale. The 2026 inflection is characterized by capacity announcements and first commercial rollouts, which is reshaping supplier bargaining power and route‑to‑market options.
-
Energy & feedstock cost sensitivity: Industrial fermentation remains exposed to fuel and electricity prices. For example, Henry Hub natural gas averaged roughly $3.50 per MMBtu in 2026 (down from prior year), illustrating how commodity volatility can compress or expand margins quickly. Companies that lock in long‑term energy arrangements or co‑locate with stable renewable power/CO2 sources will have a measurable cost advantage.
-
Regulatory inflection points: Regional regulators are updating novel food and feed guidance. An example is the European Food Safety Authority’s guidance refresh in late 2024; by early 2026 some precision‑fermented proteins still awaited full safety opinions. Regulatory timing is a determinative variable: a six‑ to twelve‑month shift in approval can change payback assumptions on greenfield investments.
-
Geopolitical & policy drivers: Policy actions — including energy import strategies in the EU and strategic industrial investment plans in Asia — are reshaping where and how microbial protein projects are financed and permitted. Public programs and strategic industrial plans have already mobilized significant capital flows into alternative proteins in select jurisdictions.
-
Market structure: The ecosystem remains fragmented — innovation is distributed across specialty start‑ups, regional food players and vertically integrated feed producers. No single cluster currently dominates, which keeps acquisition and partnership opportunities abundant but increases commercial due diligence demands.
Competitive landscape — a strategist’s read on core players
-
Unibio (Denmark) — Specializes in methane‑based microbial protein (Uniprotein®) aimed at animal feed and future food applications. Strategic posture: technology‑led scale‑up with emphasis on non‑GMO credentials. Considerations for partners: offtake security for animal feed volumes and co‑investment in downstream processing to unlock food‑grade routes.
-
Calysta (USA) — Developer of FeedKind and FeedKind Pet (methane‑derived bacterial protein). Strategic posture: commercialization via strategic food and pet brand partnerships — illustrated by a recent pet food launch in Europe. Considerations: building upstream feedstock security and diversified offtake to avoid single‑channel risk.
-
Solar Foods (Finland) — Producer of Solein, using electricity and CO2 to create microbial protein. Strategic posture: premium food‑grade positioning with an explicit sustainability narrative; capacity expansion plans point to ambitions beyond initial factory economics. Considerations: securing renewable power and CO2 contracts are core to competitive advantage.
-
MicroHarvest (Germany) — Focused on fermenting industry side‑streams for pet food, aquaculture and human food. Strategic posture: fast retail rollouts and regional capacity build‑out (including a planned facility targeting tens of thousands of tonnes annual capacity). Considerations: tight retail relationships enable rapid market penetration, but scaling to industrial capacity requires upstream feedstock consistency.
-
KnipBio (USA) — Offers single‑cell protein for aquafeed and related applications. Strategic posture: application‑specific specialism (aquaculture) and technical differentiation through microbial strain selection. Considerations: aquaculture is a high‑value beachhead for scaling feed formulations and demonstrating performance outcomes.
-
ENOUGH / 3F Bio (UK) — Mycoprotein producer focused on feed and food. Strategic posture: plant‑based mimicry and ingredient licensing; regulatory approvals and consumer acceptance remain critical milestones for food expansion.
Recent industry moves that matter in 2026
-
Commercial product launches are accelerating — e.g., a notable branded pet product leveraging methane‑derived protein reached European retail in early 2025, signalling faster commercial adoption in pet nutrition channels.
-
Capacity investments are being announced and executed — firms that announced expansion plans in 2025–2026 are entering a critical construction and commissioning window; their success will determine supply elasticity in 2027–2028.
-
Retail and foodservice partnerships are forming early — companies with retail distribution and scale line‑ups will constrain the price premium for new proteins and force incumbent producers to clarify differentiation around cost, functionality and sustainability.
How to use this intelligence in 2026 — a practical playbook
-
For investors: prioritize staged capital deployment tied to regulatory milestones and plant commissioning. Use our scenario engine to stress‑test exit multiples under different approval and energy‑price paths.
-
For CPG and feed companies: secure supply via offtake and co‑location agreements that include energy and CO2 supply guarantees; pilot private‑label launches in pet and aquafeed to build procurement scale and learn formulation economics.
-
For technology providers and start‑ups: design modular scale‑up plans that allow conversion of demonstration lines into commercial modules; focus on feedstock flexibility to withstand regional energy or gas shocks.
-
For public sector and policymakers: target infrastructure support where industrial symbiosis can reduce both capital requirements and operational carbon intensity — renewable power corridors and industrial CO2 capture hubs yield outsized returns for microbial protein projects.
What we intentionally withhold here (and why)
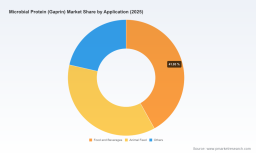
This preview is designed as a “trailer”: it demonstrates the depth of our research and the practical value of the models and playbooks PW Consulting provides, while deliberately withholding the granular regional and application split tables, and the full downloadable financial models. Those core sub‑segment datasets, interactive dashboards and editable capex/opex models are included in the full report and dataset package, which we make available through our publication portal to enable confidential client analysis and custom scenario runs.
Conclusion — the decision horizon for 2026
Microbial protein is entering the commercialization era. The headline growth trajectory — close to a double‑digit CAGR across the 2026–2032 forecast window and a clear step‑up in market scale between 2025 and 2026 — creates a narrow window for strategic positioning. Firms that lock in feedstock and energy resilience, align regulatory and quality strategies, and secure initial commercial offtake will capture the most value. PW Consulting’s full study provides the granular, transaction‑ready intelligence (market sizing, factory models, legal/regulatory checklists and partnership templates) that executives need in 2026 to turn strategic intent into realized advantage.
To access the complete dataset, editable financial models and scenario dashboards that underpin this preview, please consult the full Microbial Protein (Gaprin) Market report on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Microbial Protein (Gaprin) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com