

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: TVS Diodes Market Poised for 8.2% CAGR, Reaching USD 330 Million by 2032

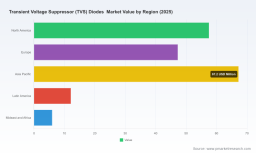
Transient Voltage Suppressor (TVS) Diodes Market — Strategic Outlook for 2026 Decision‑Making
Executive trailer
As electrification, high‑speed communications, and industrial automation accelerate, overvoltage protection is moving from a commodity specification to a strategic system design decision. PW Consulting’s new Transient Voltage Suppressor (TVS) Diodes Market study translates this macro shift into a practical playbook for corporate leaders who must decide product roadmaps, sourcing strategies, qualification timelines, and inorganic moves in 2026. This preview outlines the study’s core takeaways and the strategic value it delivers while deliberately withholding the complete proprietary segmentation tables and financial models — the full dataset is available on our report page.
Transient Voltage Suppressor (TVS) Diodes Market
Market snapshot: scale, trajectory, and concentration
Using 2025 as the study’s base year and a proprietary bottom‑up demand model, the TVS diode market is estimated at approximately USD 190 million in 2025 after steady expansion from the earlier part of the decade. Our forecast horizon (2026–2032) projects sustained growth driven by higher system voltages in electric vehicles, densification of telecom infrastructure, and increased protection requirements across industrial and datacom equipment. The model points to a compound annual growth rate (CAGR) of 8.2% across 2026–2032 and an expected market scale near the mid‑hundreds of millions of USD by the end of the forecast window. Competitive dynamics are neither perfectly fragmented nor fully consolidated — the top three players account for a clear majority share, with the top five further increasing concentration, creating an environment where scale, qualification capabilities, and trusted supply relationships matter.
Transient Voltage Suppressor (TVS) Diodes Market
Why this matters for corporate leaders in 2026
- Product differentiation: Protection components are now integral to system performance (energy efficiency, reliability, EMI/EMC) rather than line‑items; design wins drive long life and recurring revenue.
- Qualification overhead: Automotive and high‑reliability segments require AEC‑Q101, PPAP, or military‑grade qualifications — qualification investments and time‑to‑market materially affect supplier selection and design timelines.
- Sourcing and resilience: Market concentration implies that supplier capacity constraints, wafer supply, or allocation policies can translate quickly into product delays; supplier diversification and co‑development contracts are strategic levers.
- M&A and partnerships: Given the moderate concentration and growing technical differentiation (high‑voltage, low‑clamp, array devices), targeted acquisitions or JV’s can accelerate capability gaps faster than organic R&D.
Demand and technology dynamics shaping 2026 choices
Three technology and end‑market trends will dominate buyer and supplier behavior this year:
Transient Voltage Suppressor (TVS) Diodes Market
- Automotive electrification and higher nominal voltages. The migration toward 400–800 V architectures in EV powertrains expands demand for high‑voltage and low‑clamping TVS devices, with suppliers increasingly offering automotive‑grade, PPAP‑capable series to address battery management systems, battery disconnect units, and high‑voltage HVAC circuits.
- System densification and miniaturization. SMD portfolio extensions, array solutions, and lower capacitance parts are being prioritized by designers in telecom, datacom, and consumer electronics where space and signal integrity matter.
- Qualification and traceability. Across automotive, industrial, and mil‑grade markets, buyers demand documented qualification paths (AEC‑Q101, PPAP readiness, and in some cases MIL‑PRF levels), driving longer qualification cycles but higher switching costs once approved.
Competitive landscape — what leading suppliers are doing
The market features a mix of broad semiconductor houses and specialist component manufacturers. Each player’s route to competitiveness reflects different strengths:
- Littelfuse, Inc. — Strong emphasis on automotive and high‑voltage offerings; recent product introductions underline a strategy focused on AEC‑Q101 qualification and PPAP capability for EV power electronics. Their launches signal an intent to own protection in high‑voltage domains.
- Bourns, Inc. — Known for robust automotive‑grade TVS lines and a focus on design‑in reliability for harsh environments; emphasizes compliance and customer support for OEM qualification.
- Infineon Technologies AG — Brings semiconductor integration expertise; leverages broad power portfolio to bundle protection solutions into system‑level offerings.
- Vishay Intertechnology and STMicroelectronics — Large, diversified portfolios that offer scale advantages, global distribution networks, and cross‑sell opportunities into existing product lines.
- ON Semiconductor and Diodes Incorporated — Active in automotive qualification and tailored TVS solutions; competing on delivery performance and application‑specific optimization.
- Semtech Corporation — Positions EClamp and TVS technology into surge protection niches with an emphasis on protocol or connector‑level protection.
- INPAQ, PROTEK DEVICES, MCC, Nexperia, Texas Instruments, Microchip — Range from cost‑competitive volume suppliers to high‑reliability specialists. Microchip, for example, maintains MIL‑PRF‑level device families for high‑reliability applications that require JANTX‑type qualification.
Collectively, these firms compete across product performance (clamping voltage, standoff voltage, leakage), qualification capability, package formats, and supply assurance. Recent product announcements underscore a tilt toward automotive and high‑voltage portfolios, reinforcing the strategic importance of qualification and thermal/mechanical robustness.
Key near‑term market developments to watch in 2026
- New high‑voltage TVS series being introduced with automotive PPAP readiness and AEC‑Q101 qualification — suppliers are racing to secure early design wins in 800 V EV subsystems.
- Greater deployment of TVS arrays and integrated surge solutions in datacom and 5G front‑haul equipment to balance signal integrity and protection requirements.
- Supply continuity measures: capacity expansion announcements, allocation frameworks, and tiered premium pricing for guaranteed volumes.
Strategic implications and actionable recommendations for 2026
For product, sourcing, and corporate strategy teams, the PW Consulting study translates market dynamics into a disciplined set of actions:
- Prioritize qualification roadmaps. If targeting automotive or industrial high‑reliability markets, embed supplier qualification gates early in the product lifecycle; allocate engineering cycles to supplier co‑testing and PPAP artifacts.
- Diversify supply with purpose. Segment components by criticality and qualify at least two sources for system‑critical TVS parts; for high‑voltage or uniquely specified parts consider strategic supply agreements or joint development contracts.
- Revisit BOM economics. Rising demand and qualification premiums will create pricing pressure; model total cost of ownership (including qualification time and margin erosion) rather than unit price alone.
- Assess M&A and partnership opportunities. Use targeted bolt‑on acquisitions to gain specialized packaging, high‑voltage process know‑how, or higher qualification credentials faster than organic development.
- Implement scenario planning. Build upside/downside demand cases around EV adoption rates and telecom infrastructure rollouts; use these scenarios to size buffer inventory and capacity commitments.
What PW Consulting’s full report contains (practical, decision‑ready deliverables)
- Granular, downloadable forecast model (2020–2032) with interactive filters by region, type, and application — including sensitivity levers for EV penetration and telecom capex.
- Supplier scorecards covering product portfolios, qualification status, manufacturing footprint, commercial terms, and go‑to‑market strengths.
- Component‑level technical benchmarking (clamp curves, capacitance, leakage, thermal performance) and recommended specification language for design contracts.
- Regulatory and qualification checklist (AEC‑Q101, PPAP pathways, MIL‑PRF considerations) and an NPI timeline template calibrated for common OEM procurement cycles.
- Supply risk matrix and mitigation playbook (dual‑sourcing templates, buffer strategies, contract clauses, long‑lead component forecasting).
- M&A heatmap and partnership shortlist indicating technology adjacencies and likely targets by strategic intent.
- Primary interviews and field validation with OEM design teams, ODMs, and leading suppliers to ground the forecast and strategic recommendations.
Note: This preview intentionally refrains from reproducing the detailed regional and application splits and line‑item tables in the public text. Those granular segmentation outputs and the full Excel model are included in the paid report package.
How to use this study in 2026 — a short playbook
- Product teams: Update protection specifications to reflect expected system voltages and thermal environments; lock supplier qualification milestones into the product development schedule.
- Sourcing leaders: Run a segmentation of parts by strategic criticality and execute dual‑source qualification where the cost of disruption exceeds inventory carry costs.
- Strategy and corporate development: Use our M&A heatmap to validate tuck‑ins that fill capability gaps (high‑voltage processes, packaged arrays, or qualification credentials).
- Operations and finance: Stress‑test supply agreements against 8.2% CAGR scenarios and perform cashflow sensitivity analysis for premium allocation to secure capacity.
Conclusion and next step
The TVS diode market in 2026 is a growth market with strategic inflection points. The combination of higher system voltages, stringent qualification requirements, and moderate supplier concentration means that design wins and supplier relationships will be decisive for OEMs and component makers alike. PW Consulting’s full report delivers the quantitative models, supplier analytics, and tactical playbooks required to convert this macro trend into concrete actions.
To access the complete dataset, interactive forecast model, supplier scorecards, and the full set of actionable recommendations, visit the report page. Our team is also available for bespoke workshops to apply the findings directly to your product portfolio, sourcing strategy, or M&A screening process.
For detailed analysis of this topic, please visit the official page: Transient Voltage Suppressor (TVS) Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com