

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Rubber Flooring Market Hits USD 8,611.34M in 2025; Poised for 4.91% CAGR Through 2032

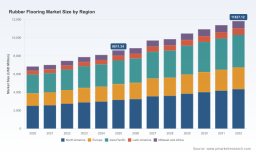
Rubber Flooring Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As companies prepare budgets, supply chains, and product roadmaps for 2026, the rubber flooring market presents a mix of steady expansion, regulatory levers, and technology-driven product shifts that demand proactive strategic responses. Our latest PW Consulting market study—grounded in a 2020–2025 historical baseline and a detailed 2026–2032 forecast—shows the industry expanding from roughly USD 6.8 billion in 2020 to about USD 8.6 billion in 2025, with a projected compound annual growth rate (CAGR) of 4.91% across the 2026–2032 horizon. By 2032 the global market is expected to approach roughly USD 11.8 billion. These headline metrics frame an industry that is mature but dynamic: large enough to support scale plays, and yet fluid enough that differentiated strategies will outperform broad-based, undifferentiated approaches.
Rubber Flooring Market
Why this study matters for 2026 decisions
-
Timing capital allocation. The mid‑single-digit CAGR masks pockets of higher and lower growth driven by product innovation, sustainability incentives, and end‑use demand cycles. Companies that align capital deployment—capex, R&D, and M&A—against these pockets will achieve superior returns in a modestly growing market.
Rubber Flooring Market -
Supply‑chain hedging. Feedstock cost swings and incentive programs are already reshaping sourcing economics. Understanding the interaction between raw material trends and legislative incentives is essential to lock in margins and avoid costly short‑term reactive moves.
Rubber Flooring Market -
Portfolio and channel choices. The market’s concentration (with the top three and five firms controlling a meaningful share) creates both incumbency advantages and entry points for specialist players. Our research shows that product quality, sustainability credentials, and channel relationships are the primary vectors for competitive differentiation in 2026.
-
Regulatory arbitrage and sustainability. New and expanding incentive programs for recycled content are shifting economics in favor of recycled‑content solutions. Firms that can operationalize circular feedstock strategies and document lifecycle impact will capture preferential procurement opportunities across public and private sectors.
What the PW Consulting report delivers — practical, decision‑ready intelligence
-
Robust market sizing and trajectory: yearly historicals and a transparent 2026–2032 forecast model, with scenario analyses for alternative macro and policy outcomes.
-
Cost‑to‑serve and input‑cost sensitivity: modeling that links key raw materials, production routings, and logistics to margin outcomes—enabling procurement to quantify hedging value and product teams to set price floors.
-
Regulatory and incentive mapping: detailed treatment of national and subnational programs that materially affect recycled‑content economics, tariff changes, and procurement rules—built for legal, compliance, and commercial teams to action.
-
Competitive playbooks: benchmarking of incumbent and challenger firms across product performance, sustainability credentials, route‑to‑market, and manufacturing footprint—complete with acquisition target screens and partnership archetypes.
-
Commercial activation templates: go‑to‑market roadmaps for enterprise, commercial, and specialty channels, plus tender response playbooks for public procurement that reflect evolving sustainability scoring.
-
Executive scenario planning: three investment and growth scenarios with trigger metrics and KPIs to guide capital allocation through 2032.
Market dynamics to watch in 2026
-
Sustainability incentives are reshaping product economics. Federal and state programs in major markets are explicitly incentivizing the use of recycled crumb rubber and devulcanized feedstocks in flooring products. These incentives have a direct and immediate impact on competitive positioning for manufacturers that can validate recycled content and circular supply chains.
-
Trade and tariff policy is a near‑term risk vector. Recent executive guidance on reciprocal tariffs and procedural changes to floor‑related materials trade creates both cost risk and potential short‑term dislocations for global procurement teams—necessitating stress tests of sourcing strategies.
-
Feedstock pricing volatility persists. Synthetic rubber feedstocks continue to experience price movements tied to petrochemical cycles; for example, benchmark butadiene pricing has shown upward pressure in 2026. Manufacturers with vertical integration, long‑dated purchase agreements, or access to recycled inputs will be better insulated.
-
Product innovation is accelerating premiumization and substitution. New formulations and platforms that reduce PVC use, extend service life, and improve design flexibility are changing specification behavior in contract and commercial channels.
Competitive landscape and strategic implications
The sector blends global players with specialty regional manufacturers; market concentration data indicate significant share held by top firms, underscoring the importance of scale and brand in certain end markets. That said, there is a persistent role for focused innovators and sustainability‑led challengers.
-
Interface, Inc. — Bringing a portfolio emphasis on long service life and low carbon footprints, recent product launches (notably a PVC‑free resilient platform introduced in early 2026) signal the company’s intent to lead premium, environmentally conscious specifications in contract and architectural projects. For competitors, Interface’s move highlights the need to accelerate validated lifecycle claims and to be ready for spec‑level battles in high‑visibility projects.
-
Large U.S. specialty players (examples include established roll and tile manufacturers) — These firms continue to leverage distribution strength, bespoke manufacturing runs, and close relationships with fitness and commercial installers. Their agility in product customization is a counterbalance to globalized scale producers.
-
Recycled‑content specialists — Manufacturers with validated processes to convert end‑of‑life tires into high‑performance surfacing enjoy two structural advantages: improving margin through incentive capture, and favorable positioning in public sector tenders prioritizing landfill diversion.
-
Premium athletic and specialty system providers — Firms focused on sports halls and performance environments emphasize differentiating features such as antibacterial properties, acoustic performance, and engineered shock absorption. These technical differentiators support higher ASPs but require ongoing investment in testing and certifications.
Strategic playbook for 2026
-
Prioritize recycled‑content validation. Invest now in materials testing, chain‑of‑custody systems, and third‑party verification to qualify for incentive programs and sustainability procurements. The delta in net cost can be material once incentives and avoided disposal costs are included.
-
Lock supply where it matters. Hedging or vertically integrating feedstock lines (synthetic rubbers vs. recycled crumb) should be evaluated against forecast price curves and scenario stress tests. Small percentage improvement in feedstock cost translates to significant P&L impact in a mid‑growth market.
-
Differentiate through product and specification services. Competing on price alone is a low‑margin path. Invest in quantifiable performance metrics (durability, acoustics, anti‑microbial features) and in specification support teams to win commercial tenders.
-
Use M&A and partnerships to fill capability gaps. Identify targets that provide validated recycled feedstocks, niche technical IP, or access to under‑penetrated distribution channels. Structured earnouts tied to recyclate sourcing milestones can align incentives and de‑risk buys.
-
Prepare for procurement policy shifts. Public procurement increasingly favors circular content and lifecycle cost assessments. Update sales and tender teams with lifecycle calculators and compliance checklists to convert specification wins into lasting contracts.
What we recommend executives do in Q1–Q2 2026
-
Run a 90‑day procurement stress test that models tariff scenarios, incentive capture, and a 10–20% feedstock price swing to identify critical supply dependencies.
-
Complete a product certification sprint: obtain at least one third‑party recycled‑content verification and one performance certification (acoustic or antibacterial) for a priority product platform.
-
Shortlist and perform diligence on two inorganic targets or partnership models that accelerate access to recycled feedstock or a high‑margin end market.
-
Revise commercial incentives for specification leads in major accounts to reward lifecycle‑based wins, not just headline revenue.
Final note — why the full report is essential
This executive brief outlines the strategic contours you need for near‑term action. The full PW Consulting Rubber Flooring Market report includes the granular datasets, regional and application breakouts, supplier cost models, and detailed company profiles that are essential to convert strategy into executable plans. In particular, our downloadable financial model and scenario engine allow teams to quantify how incentives, feedstock shifts, and specification wins translate into EBITDA outcomes under multiple policy and price paths.
For procurement directors, product leaders, and corporate strategy teams making decisions in 2026, this intelligence is not academic—it is the difference between protected margin and margin erosion, between winning transformative contracts and missing specification windows. Access the full report for the detailed segment breakouts, validated supplier benchmarks, and the operational playbooks required to act with confidence.
For detailed analysis of this topic, please visit the official page: Rubber Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com