

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
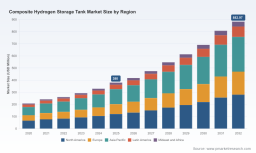
PW Consulting: Composite Hydrogen Storage Tank Market to Hit USD 882.97M by 2032 (12.8% CAGR)

Composite Hydrogen Storage Tank Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As hydrogen scales from niche deployments to an integrated low-carbon energy vector, composite hydrogen storage tanks have moved from engineering curiosity to a commercial battleground. Our latest PW Consulting market study — base year 2025, forecast 2026–2032 — shows the global composite hydrogen storage tank market crossing the mid‑hundreds of millions of USD in 2025 and tracking to nearly a billion‑dollar opportunity by the end of the forecast horizon, at a compound annual growth rate of roughly 12.8%. That trajectory reflects simultaneous acceleration across mobility, refueling infrastructure, and industrial distribution use cases, and it frames the commercial decisions CEOs, investors, and procurement leads must make in 2026.
Composite Hydrogen Storage Tank Market
Why this report matters for 2026 strategic decisions
-
Timing: 2026 is a pivotal execution year. Supply capacity expansions, certification milestones and first‑wave infrastructure rollouts translate market intent into measurable demand. Companies that move early can secure supply, capture technology learning curves, and shape standards adoption.
Composite Hydrogen Storage Tank Market -
Risk management: The hydrogen value chain is capital‑intensive and technology‑varied. Our study provides scenario-based downside and upside outcomes tied to policy, certification, and raw‑material pathways — enabling procurement and treasury teams to size commitments with clearer risk buffers.
Composite Hydrogen Storage Tank Market -
Commercial positioning: Whether you are an OEM, station operator, cylinder manufacturer, or materials supplier, 2026 choices on partnerships, localization, and certification investments will lock in cost and access advantages for the rest of the decade.
Market trajectory: what the headline numbers tell us
From a solid base in 2025, the composite hydrogen storage tank market is forecast to expand at a sustained double‑digit rate through 2032. The pace reflects three overlapping growth vectors: mobility (light vehicles, commercial trucks, and trailers), refueling and distribution modules, and industrial on‑site replacement of legacy steel cylinders. The projection to nearly the end‑of‑decade milestone captures both unit growth (more tanks deployed) and mix effects (higher‑pressure, Type‑4 systems and integrated modules carrying premium ASPs). For strategy teams, the headline growth rate is a signal: invest in capacity and certification now, or accept a position as second‑tier supplier when demand ramps.
Key market dynamics shaping 2026 strategies
-
Technology evolution: Type‑4 composite tanks (polymeric liners wrapped with carbon fibre) continue to gain preference in mobility and high‑pressure applications. Concurrent R&D on ultra‑high‑pressure cylinders (approaching and exceeding 700 bar) and trailer‑scale tube systems is redefining system architectures for distribution‑scale hydrogen.
-
Standards and certification are decisive gatekeepers: Recent certification achievements in Europe and equivalent technical targets set by major R&D sponsors are clearing pathways to commercial deployment. Companies that secure timely approvals obtain first‑mover access to regulated fleet and infrastructure contracts.
-
Supply‑chain inflection: Key raw materials — notably carbon fibre — have experienced meaningful price declines versus late‑2010s peaks and industry forecasts point to continued cost pressure over the medium term. That trend improves the economics of composite systems but also compresses margins for incumbent suppliers unless offset by scale or differentiated value‑adds.
-
Manufacturing localization: New production lines and facilities optimized for certified cylinder production are being commissioned; proximity to large mobility OEMs and refueling hubs reduces logistics and certification complexity. These investments create regional clusters that matter for procurement timelines.
-
System integration pull: End‑users increasingly buy integrated storage modules (tank + valves + sensors + mounting systems) rather than loose cylinders. This favors suppliers who can move up the value chain or who have secure partnerships with integration specialists.
Competitive landscape — strategic positions and implications
The market is populated by a mix of specialty composite manufacturers, traditional cylinder producers that have migrated to CFRP solutions, and large OEMs integrating tanks into fuel cell platforms. Each archetype poses different opportunities and threats to buyers and investors.
-
NPROXX (Netherlands) — Focused on Type‑4 CFRP pressure vessels for high‑pressure truck and station use. Recent product launches engineered for 700‑bar truck applications demonstrate a clear push toward heavy‑duty mobility. Strategic implication: NPROXX is a partner of choice for transport fleets seeking robust, vehicle‑grade tanks and for OEMs demanding integration support for high‑pressure systems.
-
Sinoma Science & Technology (Suzhou) — A vertically integrated Chinese player producing aluminum‑lined composite cylinders and storage systems for vehicles and infrastructure. Its integrated manufacturing model shortens product development cycles for localized markets. Strategic implication: Asian manufacturers with upstream capabilities can offer competitive lead times for large fleet deployments and should be evaluated for regionally‑focused rollouts.
-
CIMC‑Hexagon — A JV that has delivered TPED‑certified Type‑4 cylinders for European distribution modules. Certification handshakes such as this unlock access to regulated commercial programs. Strategic implication: Certification credentials are a commercial moat — suppliers with them can become default choices for regulated infrastructure tenders.
-
Hexagon Purus — Supplies lightweight Type‑4 cylinders and integrated systems for mobility and distribution. Their role in module assemblies positions them as a preferred systems supplier for fleet and station OEMs. Strategic implication: Suppliers combining cylinder production with module assembly capability reduce integration risk for buyers.
-
Luxfer Gas Cylinders — A legacy cylinder manufacturer that has expanded into carbon composite Type‑3/Type‑4 lines. Its broad product portfolio enables multi‑segment reach — from portable solutions to vehicular packs. Strategic implication: Large, diversified incumbents can undercut niche margins via scale; smaller specialists must defend with differentiation (weight, certification speed, or service).
-
Quantum Fuel Systems — Focused on advanced Type‑4 cylinders, including higher‑pressure designs for trailers. Strategic implication: Players pushing the pressure envelope enable long‑range and high‑capacity transport solutions, which can open new markets in logistics and long‑haul mobility.
-
Toyota Motor Corporation — As an OEM integrating Type‑4 tanks into fuel cell vehicles, Toyota’s design and procurement choices greatly influence upstream specifications and supplier selection. Strategic implication: OEMs with integrated programs shape technical standards and can accelerate supplier consolidation around their preferred technologies.
Recent corporate moves underscore market acceleration: product launches for 700‑bar truck tanks, development collaborations targeting 930‑bar trailer systems, and delivery of certification‑compliant cylinders to European distribution modules. These events are not academic — they indicate buyer readiness and supplier maturity. For strategic teams, each press release is a market signal to reassess sourcing, partnership, and investment timing.
Report contents: practical modules for immediate use
Our study is built as an execution tool for commercial and technical teams, not just an academic forecast. It includes:
-
Bottom‑up market sizing and a transparent methodology, reconciling unit deployments, average selling prices by system class, and validated supply‑side capacity constraints.
-
Scenario modelling (policy up/down, raw‑material price paths, and certification timing) with sensitivity tables to inform capex and inventory decisions.
-
Detailed supplier profiles and capability maps (manufacturing footprint, certification portfolio, integrations experience), designed for RFP short‑listing.
-
Cost build‑ups and target cost curves for Type‑I to Type‑IV systems, highlighting key cost levers and potential sourcing strategies for margins improvement.
-
Regulatory and standards tracker — certification timelines, critical technical targets, and compliance risks by region.
-
Go‑to‑market playbooks for OEMs, distributors and start‑ups: partnership archetypes, pricing strategies, and recommended contracting terms to de‑risk long lead times and yield performance guarantees.
-
Investment thesis and the M&A landscape: what to buy, when to build, and which assets are likely to consolidate first under different demand scenarios.
Strategic recommendations for 2026
-
Prioritize certification and integration capability. In most plausible scenarios, certified system supply will be the binding constraint in 2026; firms with on‑hand approvals or clear pathways will capture disproportionate share of early contracts.
-
Lock in material contracts and hedges selectively. While carbon‑fibre and polymer prices have eased, volatility remains. Hedging selectively for key production phases reduces schedule and margin risk.
-
Design for system economics, not component benchmarks. Buyers should push suppliers on system‑level metrics (kg H2 per vehicle, volumetric and gravimetric energy density, integrated safety) rather than component weight alone.
-
Form strategic partnerships that cover the whole value chain. Joint development agreements, supply‑backed offtakes, and shared certification programs accelerate time‑to‑market and split capital burden.
-
Use staged capacity commitments. Consider options and phased investments tied to certification milestones and demand triggers to avoid stranded capacity in adverse scenarios.
How to use this briefing and next steps
This document is a concise strategic primer. The full PW Consulting Composite Hydrogen Storage Tank Market report contains the granular inputs, segment analyses, and actionable models you need to finalize 2026 procurement, investment, and product roadmaps. If your priority is tender preparation, supplier short‑lists, capex phasing, or M&A screening, the report provides tailored decision support modules and customisable financial models that convert market signals into executable plans.
For teams preparing 2026 budgets and contracts, the choice is binary: treat composite hydrogen storage as an emerging but peripheral component — or treat it as a strategic supply‑chain and systems decision. The market dynamics, certification progress, and supplier activity we outline here make one thing clear: there is a narrow window in 2026 to secure technical advantage and commercial positioning. Our full study is designed to make that window actionable.
For detailed analysis of this topic, please visit the official page: Composite Hydrogen Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com