

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Coolant Flow Control Valves Market to Hit USD 1,844M by 2032 at 7.7% CAGR

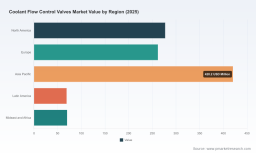
Coolant Flow Control Valves Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s senior industry advisory team, we present a strategic preview of our full Coolant Flow Control Valves Market study to equip executive teams with the context they need when planning product roadmaps, manufacturing investments, supplier strategies and M&A through 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study demonstrates a sustained recovery and structural growth: the global market expanded from roughly USD 815 Million in 2020 to about USD 1,098 Million in 2025, and is projected to grow at a compound annual growth rate of 7.7% through the forecast window, approaching USD 1,844 Million by 2032. This trajectory is being driven less by single short-term cycles and more by architecture shifts in vehicle thermal management and tightening performance requirements.
Coolant Flow Control Valves Market
Why this study matters to 2026 strategic choices
-
Timing of investment: With macro growth firmly established, near-term capital allocation (2026–2028) should prioritize modular valve platforms and scalable testing capacity rather than one-off tooling for legacy designs.
Coolant Flow Control Valves Market -
Product strategy: Multicircuit thermal architectures in electrified platforms require valves that combine mechanical robustness with embedded actuation and diagnostics. Decisions made in 2026 on platform roadmaps will determine who competes at scale in 2027–2030.
Coolant Flow Control Valves Market -
Supply-chain positioning: Raw material selection and supplier qualification windows are lengthening. Firms that secure high-quality stainless steel and specialty polymers and that qualify multiple actuator suppliers will reduce time-to-production risk.
-
M&A and partnerships: The market shows meaningful concentration at the top—three players control a large share of revenue—and mid-market consolidation remains a realistic route to obtain platform IP, test capability, and OEM channels.
Key market dynamics and technology inflection points
The market’s growth profile reflects a deeper technical shift: cooling is no longer a simple single-loop function. Electrification and thermal optimization have turned coolant flow control valves into system-level components that coordinate batteries, power electronics and motors, in addition to traditional engine cooling. Manufacturers and OEM thermal teams are treating valves as levers for efficiency, range and safety rather than as commodity shutoffs.
-
Electrification drives multi-port demand: As vehicle platforms move from integrated engine loops to distributed thermal zones, demand patterns favor multi-way valve architectures that enable independent circuit control and finer thermal zoning.
-
Durability and standards: New durability benchmarks matter. For example, industry standards in hybrid and electric powertrains now require valve actuation components to endure more than three million switching cycles to ensure long-term reliability (Bosch Mobility Solutions, 2025). Compliance with these thresholds cannot be an afterthought in product development.
-
Materials and chemical compatibility: Valve bodies increasingly combine stainless steel and high-performance polymers to resist ethylene glycol-based coolants and to balance cost, weight and manufacturability (Industry Market Data, 2025).
-
Electronics and controls integration: Valve differentiation is migrating into mechatronics — precise actuator control, integrated position sensing and fault reporting that tie into the vehicle’s thermal and battery management systems.
Competitive landscape — who matters and what to watch
The supplier field remains led by established component and systems players with deep automotive relationships and platform capabilities. The market concentration metrics indicate top-tier dominance, but also meaningful opportunities for technology leaders and well-capitalized challengers. Below we synthesize the strategic posture of dominant and fast-moving suppliers.
-
Vitesco Technologies (Regensburg, Germany) — Strengths: modular multi-port valve platforms and clear OEM footprints across ICE and EV lines. Strategic implication: invest in software-enabled valve modules and seek co-development agreements with OEM thermal teams to secure system-level specs early in vehicle program cycles. Consider licensing or joint-testing arrangements to accelerate adoption into BEV cooling packs.
-
VOSS Automotive (Wipperfürth, Germany) — Strengths: robust portfolio of thermally and electrically actuated valves and deep materials know-how. Strategic implication: leverage materials and actuation IP to offer performance-differentiated products; explore bundling valves with fluid distribution fittings to capture greater BOM value.
-
INZI Controls (South Korea) — Strengths: multi-way valves and actuator systems spanning ICE to FCEV. Strategic implication: aggressive pitch to Asian OEMs on integrated actuators and compact multi-way solutions can capitalize on regional EV platform growth; potential acquisition target for players seeking a footprint in high-volume Asian supply chains.
-
THOMAS Group (Germany) — Strengths: modular mixing and control valves focused on battery and drive-unit thermal management. Strategic implication: partnering on thermal simulation and co-validation programs will reduce OEM qualification friction and speed time-to-production.
-
Robert Bosch GmbH (Gerlingen, Germany) — Strengths: system-level credibility, electromagnetic switching valve technology and broad integration capability. Strategic implication: Bosch’s presence raises OEM expectations on diagnostic and safety features; suppliers should map clear competitive differentiation if they seek to displace system incumbents.
-
Modine Manufacturing Company (Racine, Wisconsin, USA) — Strengths: EV-focused 3-way valve solutions for batteries, power electronics and motors. Strategic implication: Modine’s systems heritage positions it well for thermal modules; partnerships with battery-pack integrators could accelerate adoption.
Across these players, common themes emerge: (1) success requires platform modularity and software-enabled features, (2) OEM program access is decisive, and (3) scale to meet EV-related thermal volumes is a gating factor. For new entrants, differentiators should pivot on superior actuation lifetime, integrated diagnostics and material resilience.
Practical, actionable recommendations for 2026
-
Prioritize qualification for durability thresholds: If your product does not demonstrate compliance with the new multi-million-cycle switching expectations, reallocate R&D immediately. Testing rigs, accelerated life tests, and field validation programs should be budgeted into 2026 capital plans.
-
Invest selectively in mechatronics: The next wave of value is in integrated control and sensing. Firms that can include position feedback, temperature-coupled control logic and standard vehicle-bus interfaces will command higher margins and stronger OEM lock-in.
-
Secure raw-material and polymer supply lines: Implement multi-sourcing strategies for stainless steel feedstock and specialty polymers, and negotiate forward pricing or strategic partnerships to blunt volatility in 2026 procurement cycles.
-
Re-evaluate manufacturing footprint for modular scalability: Rather than large single-site investments, prefer flexible cell-based production lines that can be retooled for multiple valve families to support mixed ICE/EV platform demand.
-
Use M&A and partnerships tactically: Target acquisitions that deliver test capability, mechatronic actuation IP or direct OEM program access. Small to mid-size bolt-on deals can be accretive if they shorten qualification timelines.
-
Monitor channel and aftermarket dynamics: With thermal systems becoming more serviceable, aftermarket retrofit and diagnostic services represent a secondary revenue stream; build capabilities to capture post-sale value.
What the full PW Consulting report delivers (high-level)
Our full market study is built to be operationally useful to product, sourcing and corporate development teams. Key deliverables include:
-
Demand-side and scenario modeling across the 2020–2032 horizon, showing sensitivity to EV penetration rates, platform architecture choices, and regulatory durability baselines.
-
Supplier scorecards and risk matrices that evaluate technology readiness, scale, geographic coverage, and program win rates for major vendors.
-
BOM-level cost benchmarks, test and qualification timelines, and suggested validation protocols aligned to industry durability requirements.
-
Go-to-market playbooks for OEM engagement, tier-1 partnership strategies, and aftermarket commercialization pathways.
-
Scenario-ready financial models that translate the 7.7% CAGR and the projected market growth into investment break-evens and payback windows for typical valve programs.
In keeping with the “preview” remit, this article highlights strategic direction and actionable thinking while withholding detailed segment-level figures and granular regional or application breakdowns—these are presented in the proprietary data tables and interactive models in the full report to which this preview points readers.
Next steps for executives and teams
-
Use this preview to align 2026 annual planning across R&D, procurement and corporate development. Identify which levers (durability testing, mechatronics investment, supplier qualification) produce the highest risk-adjusted returns.
-
Request tailored briefings from PW Consulting: we offer program-level sensitivity runs and supplier deep-dives that map directly to OEM launch calendars.
-
Plan pilot programs focused on embedded diagnostics and multi-way actuation lifecycles to demonstrate differentiators to targeted OEM customers within 12 months.
For teams preparing capital allocations and strategic priorities in 2026, the choices you make now—about platform modularity, qualification intensity and partner selection—will determine whether you capture disproportionate share as the market expands from roughly USD 1.1 Billion in 2025 toward the USD 1.8+ Billion opportunity by 2032. PW Consulting’s full report contains the detailed segmentation, regional forecasts and supplier-level analytics required to convert this strategic overview into executable plans.
Contact PW Consulting to schedule a demonstration of the interactive models and to access the complete dataset and supplier scorecards.
For detailed analysis of this topic, please visit the official page: Coolant Flow Control Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com