

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Quartz Surfaces Market to Reach USD 210.1M by 2032 at 5.2% CAGR

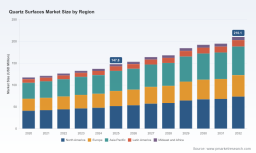
Quartz Surfaces Market 2026: Strategic Imperatives from PW Consulting’s Benchmark Study
Executive trailer
As the built environment continues to prioritize durability, aesthetics and low-maintenance materials, the quartz surfaces market is entering a phase of steady, structurally-driven expansion. PW Consulting’s Quartz Surfaces Market study -- anchored to a 2025 base year with historical coverage from 2020–2025 and forward-looking projections through 2032 -- provides the empirical foundation and executable recommendations leaders need to make confident commercial choices in 2026. The study synthesizes market sizing, competitive mapping, manufacturing economics, regulatory exposure, and go-to-market playbooks into a single strategic reference. Our model shows the market expanding from USD 117.4 Million in 2020 to USD 147.8 Million in 2025 and continuing to grow at a compound annual growth rate of 5.2% across the 2026–2032 forecast window, reaching USD 210.1 Million by 2032.
Quartz Surfaces Market
Why this study matters for 2026 decision-making
-
Actionable horizon: 2026 is the inflection year for many firms planning capital deployment, SKU rationalization and channel expansion. The report translates high-level growth into discrete scenarios (base, upside, downside) so executives can align capex, hiring and M&A timetables to realistic demand trajectories.
Quartz Surfaces Market -
Risk-aware investment: with a mid-single-digit CAGR and measurable volatility in upstream inputs and labor, the study quantifies sensitivity to raw-material pricing, specialized labor availability, and regional regulatory regimes – enabling CFOs and strategy teams to size hedges and contingency reserves.
Quartz Surfaces Market -
Competitive clarity: our competitive framework situates established global brands alongside regional specialists and vertically integrated producers, offering a route map for when to compete on price, design, service or sustainability credentials.
Market dynamics at a glance
Over the historical window (2020–2025) the market demonstrated resilient recovery and product diversification, supported by residential renovation cycles and expanding commercial specification. Our forecasts for 2026–2032 assume steady demand drivers: rising remodeling activity, preference for non‑porous low‑maintenance surfaces, and design-led premiumization. At the same time, manufacturers face persistent cost pressures from specialized labor requirements for mixing, molding and quality control, and compliance demands tied to low-emission certifications and standardized quality management systems.
Key structural drivers and headwinds
-
End‑user preference shift: Consumers increasingly favor materials that combine stain resistance and low lifecycle maintenance with high-end aesthetics. This drives higher penetration in residential remodeling and selective commercial segments.
-
Product innovation cadence: Leading vendors are expanding collections and finishes at a faster pace, shortening replacement cycles and increasing SKU complexity for distributors and fabricators.
-
Regulatory and quality standards: Low-emission certifications and facility-level quality systems (for example, GREENGUARD-level expectations and ISO-aligned manufacturing) are becoming de‑facto requirements for institutional and hospitality specifications.
-
Labor and manufacturing cost base: Production requires skilled technicians and quality-control regimes; labour scarcity or wage inflation can compress margins unless offset by automation, process redesign or near-market capacity placement.
-
Moderate market concentration: Our concentration metrics indicate room for both scale players and premium niche specialists. Market concentration is notable but not prohibitive for challengers pursuing targeted differentiation.
Competitive landscape — what the big names are doing (strategic reads, not scorecards)
-
Caesarstone: Continues to leverage heritage in engineered quartz design and color breadth. Their play is brand-driven premiumization and channel control, particularly in higher-margin residential and contract segments.
-
Cambria: As a family-owned premium manufacturer with a strong domestic-production narrative, Cambria’s differentiation centers on American-made assurance and warranty propositions, useful in markets where provenance matters.
-
MSI Surfaces: A distribution and assortment advantage with rapid new-collection rollouts. MSI’s model demonstrates how breadth of styles and national distribution infrastructure can accelerate adoption among remodelers.
-
Wilsonart: Notable for technical differentiation — low-silica formulations, large-format slabs and formal quality certifications — positioning Wilsonart to capture both performance-sensitive and design-focused buyers.
-
Spectrum Quartz, LG Hausys, Cosentino Group, HanStone Quartz: Each pursues a mix of technology-led aesthetics, global distribution and local manufacturing footprints. The common playbook elements are improved veining realism, durability claims and expanded color libraries.
Recent product activity through mid‑2026 underscores an intensified innovation rhythm. Multiple firms introduced new collections in 2026, expanding palettes and performance claims—illustrative of competition shifting from pure price to design, sustainability certification and supply reliability.
What’s inside the PW Consulting study (practical deliverables)
-
Market model and downloadable workbook: Annualized historicals (2020–2025) and forecast scenarios (2026–2032) with line-item drivers that let you re-run outcomes under alternate assumptions.
-
Segment playbooks: Go‑to‑market blueprints for product types and end-use channels, including channel economics for distributors, fabricators and installers.
-
Manufacturing and cost engineering: A factory-level cost model that isolates raw materials, labor composition, energy and yield variances; includes automation levers and payback analyses for common equipment upgrades.
-
Regulatory & certification matrix: Mapping of relevant low-emission and industry standards, with compliance timelines and supplier audit checklists to support specification wins in institutional projects.
-
Competitive profiles and M&A screen: Strategic SWOT for leading players, plus an acquisition target filter that scores candidates on capacity, channel access and IP (surface finishing and veining tech).
-
Distribution & installer economics: Heatmaps of channel density, average installation margins, and playbooks to reduce prize leakage via partner training and branded installation programs.
-
Commercial tools: Price elasticity templates, promotional lift models, SKU rationalization frameworks and ROI calculators for showroom investment or new slab lines.
-
Risk & resilience checklist: Supplier concentration assessment, crisis response playbook for supply disruptions, and labour contingency planning templates.
Strategic recommendations for 2026
-
Prioritize portfolio segmentation: Differentiate clearly between mass-market styles and aspirational collections. Use limited-edition runs and design collaborations to protect margin on premium pieces.
-
Invest in near-market manufacturing and automation: Relocate capacity or deploy semi-automated lines to reduce exposure to skilled-labor scarcity and shorten lead times for regional channels.
-
Leverage sustainability & certification as commercial assets: Certifications and documented low-emission practices should be packaged as part of the offer for hospitality and institutional bids.
-
Scale distribution with installer enablement: Strengthen distributor‑fabricator‑installer ecosystems with co-marketing, financing options for showrooms and standardized installation training to reduce failure rates and warranty costs.
-
Use M&A selectively to close capability gaps: Focus on targets that provide immediate access to underserved geographies, proprietary finishing processes or a dense fabricator network.
-
Adopt a scenario-based supply strategy: Maintain rolling 18–24 month plans with trigger points for raw-material hedging, capacity expansion, or SKU rationalization.
How PW Consulting’s research supports board-level decisions
Boards and executive committees need concise, defensible inputs when approving capital and M&A. Our study translates the macro trajectory (market size evolution from 2020 baseline through 2032) into investment-grade scenarios, cost-of-ownership analyses and near-term tactical moves that materially influence margin and share. The report’s downloadable models let users test sensitivity to labor inflation, certification cost corridors and SKU proliferation—so approvals rest on quantifiable downside protection and upside capture strategies.
What we intentionally withhold (and why)
In line with the “trailer” principle, this introduction surfaces strategic conclusions and high‑value deliverables while withholding granular segmentation tables and proprietary split-level figures that are central to competitive execution. Detailed regional and application-level breakouts, complete company revenue shares and the full Excel model are available only with the full report. This ensures decision-makers who need transaction-grade inputs use the authoritative source rather than partial excerpts.
Next steps
-
If your 2026 playbook includes capital expenditure, distribution expansion, or M&A in the quartz surfaces space, request the full report and the accompanying financial model to quantify trade-offs and inform board approvals.
-
For tailored advisory, PW Consulting offers a rapid-read engagement (4–6 weeks) to apply findings directly to your supply chain, product portfolio and go-to-market plans.
PW Consulting’s Quartz Surfaces Market study combines granular modeling, competitive insight and implementation-ready tools to move leaders from hypothesis to decision. For the complete data tables, regional and application splits, and the ready-to-use Excel workbook that powers our scenarios, visit the report page and secure the full brief.
For detailed analysis of this topic, please visit the official page: Quartz Surfaces Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com