

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrochlorination Systems Market — 6.52% CAGR Forecast (2026–2032)

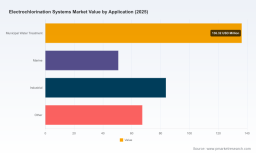
Electrochlorination Systems Market — Strategic Briefing for 2026 Decision-Makers
As companies prepare strategic agendas for 2026, electrochlorination systems are emerging from niche utility status into a mainstream tool across municipal, marine and industrial water treatment portfolios. This briefing synthesizes the directional intelligence from PW Consulting’s latest market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) and translates it into actionable guidance for executives. It demonstrates why boardrooms and business units must treat electrochlorination not as a tactical treatment option but as a portfolio-level capability with predictable growth, regulatory tailwinds, and concentrated supplier dynamics that affect procurement, product development and M&A timing.
Electrochlorination Systems Market
Market Trajectory: a predictable expansion with operational inflection points
The electrochlorination market has moved through steady expansion since 2020 and—based on our forecast—continues on a reliable upward trajectory. From the study’s base year of 2025, the market projects forward at a compound annual growth rate (CAGR) of approximately 6.52% across 2026–2032. Over the near term this translates into meaningful incremental addressable spend for technology providers and service partners, while also creating a multiyear procurement window for end-users to lock in technology roadmaps and total cost of ownership (TCO) reductions.
Electrochlorination Systems Market
For decision-makers, two pragmatic implications follow. First, suppliers will be able to amortize R&D investments in more efficient cell designs and autonomous operations over a growing installed base, which should reduce unit economics pressure over time. Second, buyers that adopt staged rollouts—piloting in constrained applications and scaling to critical systems—can capture both safety and operational benefits before commoditization drives price competition.
Electrochlorination Systems Market
Regulatory, safety and standards drivers: the new baseline for procurement
- Standards are converging: ISO 20468-9:2025 establishes formal performance evaluation and safety expectations for NaOCl generators used in water reuse, including disinfection by-product management. This narrows acceptable performance envelopes and raises the bar for compliance documentation in tenders.
- Context-specific mandates: Revised institutional standards—illustrated by the April 2025 update to Water Corporation’s Design Standard DS 112—are already requiring explicit hydrogen management and dedicated electrochlorination storage practices. These changes force integration of gas-handling and leak-detection design elements earlier in project timelines.
- Regulatory acceptance for specific use-cases: Contemporary EPA guidelines (2025) recognize electrochlorination among validated options for ballast water treatment, which materially expands the pathway for maritime uptake where regulatory certainty was previously a gating factor.
Collectively, these developments mean procurement teams must move beyond unit price negotiations to qualify vendors on standards compliance, third-party verification, and documented safety lifecycles. For vendors, compliance becomes a market-access function—not just a feature—and should be positioned as such in commercial bids.
Technology and operational dynamics that will define winners
- Cell and anode innovation: Advances in anode materials, concentric tubular designs, and cell architectures are driving both reliability and operating-cost improvements. Vendors that can demonstrate lower energy per unit of active chlorine and extended anode life will win preferred-supplier status in long-term contracts.
- Integration with asset automation: Systems that embed adaptive control, remote diagnostics and hydrogen management reduce operational risk and maintenance overhead for end-users. Expect buyers to demand modular, serviceable designs with digital condition monitoring as a default.
- Operational safety as a value proposition: Hydrogen evacuation, automated venting, and self-cleaning mechanisms are shifting from optional upgrades to procurement must-haves—especially for larger municipal and seawater applications where risk profiles are elevated.
These technological vectors favor suppliers that combine electrochemical know-how with systems engineering (mechanical, gas handling and digital). Companies that remain single-discipline players risk being out-bid on total cost and system resilience.
Competitive landscape — what to watch in 2026
The competitive arena is characterized by a mix of specialized electrochlorination specialists, broader water technology vendors and component innovators. Key firms featured in our study include:
- De Nora (Italy) — Known for seawater electrochlorination (SEACLOR®) and low-strength hypochlorite generators (ClorTec®). Recent product evolution emphasizes energy efficiency and operating-cost reductions.
- Xylem (United States) — Offers Chloropac® systems, including marine shipboard variants; emphasizes integrated service and lifecycle support for operators.
- Gaffey Technical Services Ltd (United Kingdom) — Brings modular HYPROLYSER® iSEC® systems with adaptive response control targeted at variable-load sites.
- John Cockerill (Belgium) — E-ChloPure® systems incorporate vertically mounted units for continuous hydrogen evacuation and self-cleaning; recent launches target seawater cooling applications.
- Kanadevia Corporation (Japan) — Long experience in seawater electrolyzers with a large installed base; historic depth is a competitive moat in specific maritime markets.
- Water Process Solutions Ltd (UK) , ProMinent (Germany) , Grundfos (Denmark) , Evoqua (US) , MIOX (US) , and Optimum Anode Technologies (US) — A mix of specialists and systems integrators offering pumps, generators, metering and anode technology that together form supplier ecosystems buyers will evaluate.
Recent vendor activity underscores ongoing product differentiation: John Cockerill’s mid-2025 E-ChloPure® launch and De Nora’s ClorTec Gen III announcement (June 2025) both highlight cost and safety innovations. These moves are occurring against an operational backdrop where utility standards (e.g., DS 112 revisions) prioritize hydrogen detection and storage design—advantaging vendors with demonstrable system-level safety features.
Market structure and deal implications
The market shows a moderate degree of supplier concentration: a handful of established vendors command significant influence over system architecture, standards compliance pathways and global aftermarket support. For corporate strategists, this implies three tactical paths:
- Partnership-first models: Companies focused on water treatment need not vertically integrate immediately; partnerships with established electrochlorination vendors can secure access to certified platforms and ongoing R&D without capex risk.
- Targeted M&A: For equipment vendors seeking to rapidly expand capabilities (digital controls, hydrogen management, specialized anodes), acquisitive strategies will accelerate time-to-market and strengthen procurement defensibility.
- Service-led differentiation: Given the importance of lifecycle safety and compliance, service offerings (installation, verification, predictive maintenance) are becoming a primary margin pool and a seller-buyer lock-in mechanism.
What PW Consulting’s full report delivers (practical, executable content)
- Validated market sizing and scenario modeling (base year 2025; historical 2020–2025; forecast 2026–2032) with multiple demand pathways tied to regulatory adoption and maritime uptake.
- Vendor scorecards assessing technology performance, compliance readiness, service networks and aftermarket economics—framed for procurement RFPs and supplier selection workshops.
- Operational playbooks for implementing electrochlorination across municipal, marine and industrial sites—covering safety design checklists, hydrogen management, commissioning protocols and maintenance KPIs.
- Commercial templates (term sheet considerations, service-level agreement clauses, capex/opex modeling) that teams can adapt for tenders and internal capital approvals.
- Scenario-driven risk matrices tying regulatory shifts (e.g., ISO 20468-9:2025 and revised institutional standards) to product compliance exposures and required mitigation investments.
We intentionally structure the report to be actionable within 60–90 days of purchase: procurement teams receive scorecards and RFP language, engineering teams get design checklists and safety requirements, and strategy teams obtain scenario models to support investment cases.
How to use these insights in 2026 — prioritized actions
- Short term (0–6 months): Update procurement specs to include ISO 20468-9:2025 compliance and hydrogen-detection validation. Run a vendor pre-qualification round using the report’s scorecard to identify two supply-path options (primary and contingency).
- Medium term (6–18 months): Pilot integrated electrochlorination systems at a controlled site with defined KPIs (energy use per unit active chlorine, downtime, maintenance intervals). Negotiate outcome-based service terms tied to those KPIs.
- Strategic (18–36 months): Evaluate partnerships or bolt-on acquisitions that bring either digital condition monitoring, advanced anode materials or localized aftermarket services to capture lifecycle margin and defend bid positions.
Concluding guidance — invest in capability, not just equipment
Electrochlorination is transitioning from component purchase decisions to capability-based investments. The market’s steady CAGR and predictable growth window create a low-risk environment to build reproducible deployment playbooks, capture operating-cost improvements, and lock in service relationships. Vendors that demonstrate compliance, system-level safety and integrated digital value will capture outsized share; buyers that treat procurement as capability-building will realize superior TCO and operational resilience.
To move from directional insight to executable plans, PW Consulting’s full Electrochlorination Systems Market report contains the datasets, vendor scorecards and procurement templates required to accelerate action in 2026. For teams preparing capital plans, RFPs or M&A agendas, the report functions as both the evidentiary base and the implementation manual—without which decisions risk being tactical and short-lived.
Request the full study
Contact PW Consulting to obtain the complete study and the interactive models that underpin this briefing. The full report includes comprehensive vendor benchmarking, procurement-ready templates and scenario tools that we intentionally omit from this primer to preserve the value of the primary research.
For detailed analysis of this topic, please visit the official page: Electrochlorination Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com