

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shapewear Market Poised for 8.05% CAGR (2026-2032)

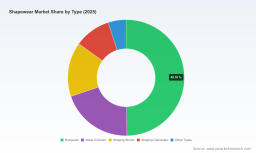
Shapewear Market 2026: Strategic Preview and Decision Framework
As PW Consulting’s Chief Industry Analyst, I present a concise yet strategically rich preview of our Shapewear Market study — an evidence-based foundation designed to shape executive decisions in 2026. This preview demonstrates the analytical depth and practical orientation of our full report while reserving the granular segment and regional datasets to encourage direct access to the full research package.
Shapewear Market
Why this study matters for 2026 decision-makers
The shapewear category has transitioned from a niche specialty into a mainstream apparel segment with durable growth characteristics. Our base year is 2025 (USD, Million), when the global market reached USD 1,800 Million. Looking back, the market expanded from USD 1,200 Million in 2020 to USD 1,800 Million in 2025 — a clear recovery and expansion trend. Under our baseline projection, the market proceeds into the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.05%, arriving at an expected USD 3,070 Million by 2032.
Shapewear Market
For 2026 planners, these dynamics translate into three immediate strategic implications:
Shapewear Market
- Scale and timing: The market’s mid-single-digit to low double-digit growth cadence supports near-term scaling investments that can pay back within 24–36 months, conditional on channel and product mix choices.
- Portfolio prioritization: Sustained growth creates both runway for new product innovation (e.g., seamless, bonded-panel technologies) and pressure to rationalize lower-margin SKUs.
- Risk management: Elevated policy-driven supply chain volatility and rising effective import duties require active sourcing and pricing strategies to protect margins.
What the full report delivers — practical, actionable content
Our full study is deliberately operational. It synthesizes market-level forecasting with executable playbooks that link strategy to execution for 2026: marketing, sourcing, manufacturing, pricing, channel optimization, and M&A. Highlights include:
- Top-level market model (2020–2032) with base-year validation and scenario-based forecasts for 2026–2032, including sensitivity bands and demand drivers.
- Go-to-market playbooks tailored to channel archetypes (direct-to-consumer, wholesale/department store, specialty e-retailers), with conversion levers and expected ROI timelines.
- Product and technology scorecards (seamless construction, bonded panels, compression fabrics, integrated bra-top designs), mapped to customer cohorts and margin profiles.
- Supply chain and cost models, including manufacturing cost build-ups, landed-cost scenarios under alternate tariff regimes, and near-shoring vs. offshore comparisons.
- Regulatory impact assessment and an import-duty stress test — quantifying tariff pass-through to price, margin, and volume outcomes under plausible 2026 policy scenarios.
- M&A and partnership playbooks: acquisition target screens, valuation priors, and integration checklists for capabilities gaps (e.g., sustainability materials, proprietary fit tech).
- Brand and retailer scorecards, competitor benchmarking, and a prioritized list of commercial experiments with A/B test designs for 2026 pilots.
Note: The full report contains detailed segment and regional revenue breakdowns that are purposefully omitted here to preserve value for report subscribers.
Competitive landscape — who matters and why
The shapewear market exhibits a moderate concentration profile: CR3 at 35.5% and CR5 at 49.2%. This structure leaves space for nimble challengers while rewarding scale players that can combine product innovation, brand power, and distribution efficiency.
- Spanx, Inc. (Atlanta, GA) — a category architect with continuous product innovation (e.g., bonded panels, flexible boning and LYCRA FitSense integration). Spanx’s recent launches in 2025 underline a dual strategy: technical performance upgrades and eco-friendly material lines.
- SKIMS (Los Angeles, CA) — excels in curve-inclusive design, DTC marketing excellence, and premium pricing power through aspirational brand positioning and size inclusivity.
- Maidenform (New York, NY) — competes on foundational and value-based offerings, retaining distribution relationships across traditional retail but investing selectively in seamless construction.
- Honeylove (New York, NY) — focal point for high-compression, shape-first consumers; product efficacy and perceived performance underpin customer loyalty.
- Commando (Los Angeles, CA) — recognized for invisible smoothing and light-support solutions; proprietary seamless techniques are the primary moat.
- Leonisa (Bogotá, Colombia) — leverages niche leadership in post-surgical and medically oriented compression as well as everyday fashion shapewear in Latin American markets.
- Wacoal Holdings Corporation (Kyoto, Japan) — blends lingerie expertise with shapewear, emphasizing supportive compression and fit engineering.
- Yitty (Los Angeles, CA) — modern brand focusing on every-body fit and social-first marketing.
- Shapellx (United States) — known for sustainability experiments (OceanHug collection using regenerated oyster shells) and product differentiation through material storytelling.
- Miraclesuit (United States) — positions around structured silhouettes and swim-integrated shaping.
Our competitive assessment in the full report includes win-loss cases, go-to-market effectiveness benchmarking, and acquisition candidate mapping that connects capability gaps to potential buyers.
Industry dynamics and 2026 headwinds
Three external dynamics will disproportionately impact strategic outcomes in 2026:
- Trade and tariff volatility: Policy shifts during 2025 produced materially higher effective import duty rates across key apparel-sourcing markets, elevating landed costs and injecting pricing risk into the supply chain. In short: brands that rely on traditional Asian manufacturing footprints face higher cost uncertainty and should model tariff stress in any 2026 pricing or sourcing plan.
- Sustainability as a material and commercial factor: Over 65% of new product lines in 2025 incorporated recycled or sustainable materials. For 2026, sustainable sourcing is both a cost consideration and a demand driver — differential pricing and brand loyalty accrue to firms that can credibly demonstrate lifecycle advantages.
- Shifting consumer use cases: Everyday wearability and body-positive product narratives are enlarging the customer base beyond special-occasion buyers. Growth is increasingly driven by frequent, lower-ticket purchases as shapewear moves into daily wardrobes.
Each of these dynamics appears in our report with quantified impact scenarios, practical mitigation steps, and example P&L sensitivity runs that senior leaders can adopt directly.
Practical strategic recommendations for 2026
Based on our integrated analysis, the following actions should be considered by brands, retailers, suppliers, and private equity sponsors planning for 2026:
- Prioritize resilient sourcing: Build dual-sourcing strategies, increase regional near-shore capacity where economically viable, and negotiate tariff contingency clauses with suppliers.
- Invest selectively in performance innovation: Allocate R&D funding to technologies that deliver measurable fit and comfort improvements (bonded panels, variable compression knitting) and quantify margin uplift from premiumization.
- Monetize sustainability: Turn material credentials into clear value-capture mechanisms — premium SKUs, corporate reporting, and retailer sustainability programs that reduce channel friction.
- Optimize channel mix for ROAS: Re-balance investments toward channels with fastest customer acquisition payback while maintaining wholesale relationships that deliver scale and brand discovery.
- Use scenario planning for pricing: Run price/margin scenarios that incorporate tariff pass-through rates and consumer elasticity, and prepare promotional calendars that protect brand equity during inflationary cycles.
- Prepare M&A playbooks: Identify targets that fill capability gaps (fit analytics, sustainable textiles, regional manufacturing) and use our valuation priors to negotiate disciplined multiples.
Next steps — how to use this preview
This preview is a strategic compass: it validates the growth opportunity (CAGR 8.05% across 2026–2032, with the market rising from USD 1,800 Million in 2025 to an estimated USD 3,070 Million by 2032) and surfaces the most consequential operational levers. For teams preparing budgets, product roadmaps, or M&A pipelines in 2026, the full PW Consulting study supplies the detailed segmentation, regional models, price/margin tables, and exemplar P&L scenarios necessary to translate strategy into execution.
To access the complete dataset, proprietary segment breakdowns, and executable playbooks referenced in this preview, please consult the full Shapewear Market report on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Shapewear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com