

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
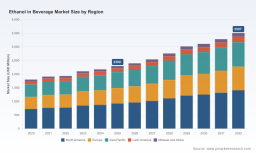
PW Consulting: Ethanol in Beverage Market to hit USD 3,507M by 2032 (6.5% CAGR)

Ethanol in Beverage Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an evidence-based briefing designed to position executives, investors, and supply-chain leaders to act decisively in 2026. This article summarizes the strategic value of our full Ethanol in Beverage Market study (base year 2025), explains why 2026 is a pivotal year for decision-making, and outlines the practical levers companies should prioritize. The full report contains the underlying segment-level data, regional breakouts, and scenario models that we deliberately omit here to encourage direct engagement with the source intelligence.
Ethanol in Beverage Market
Market snapshot — trajectory and concentration
The beverage-grade ethanol market has evolved from a modest, steady-growth commodity into a more dynamic, higher-value sector driven by premiumization, regulation, and supply-chain shifts. At the aggregate level, global industry revenues increased from USD 1,800 Million in 2020 to USD 2,300 Million in 2025 (base year). PW Consulting’s forecast models, reflecting macro demand trends and supply-side constraints, project continued expansion through 2032 — with the market reaching in excess of USD 3,500 Million by the end of the forecast horizon. This path is consistent with a compound annual growth rate of approximately 6.5% for the forecast period (2026–2032).
Ethanol in Beverage Market
Market concentration remains moderate: the three largest players account for roughly one-third of the market (CR3 ≈ 35%), and the top five capture a little over 40% (CR5 ≈ 42%). Those concentration metrics underline an industry structure where mid-sized regional specialists coexist with a handful of global integrators — an environment that favors targeted M&A and partnership strategies.
Ethanol in Beverage Market
Why 2026 matters: five strategic inflection points
-
Regulatory tightening and compliance cost escalation — Distillers and suppliers face intensified scrutiny around food-grade production, traceability, and excise compliance. Regulatory requirements (including approvals for ≥190 proof production and specific non-beverage formulations) raise the bar for plant validation and quality systems. Firms that delayed capital upgrades in prior cycles will confront higher marginal compliance costs in 2026.
-
Tariff and trade friction — Targeted tariffs on denatured ethanol introduced in late 2025 continue to reshape competitive dynamics for industrially adjacent suppliers. The persistence of these trade measures favors localized supply chains and vertically integrated models for beverage producers seeking to stabilize input costs.
-
Raw material and input volatility — While season-average corn prices and spot feeds have shown relative stability in recent datasets, weekly and regional fluctuations persist. Producers with procurement agility and hedging capability will maintain margin resilience as feedstock swings feed through to production economics.
-
CapEx cycle acceleration — New greenfield investments and capacity repurposing for beverage-grade ethanol are underway. Notably, recent announcements of dedicated beverage ethanol facilities signal a wave of capacity upgrades focused on quality differentiation rather than cost-only competition.
-
Premiumization and product differentiation — beverage alcohol producers continue to pursue higher-margin products and ready-to-drink innovations that require specialized ethanol specifications and chain-of-custody assurances. Suppliers who can certify provenance and deliver consistent organoleptic neutrality capture disproportionate value.
What the PW Consulting report delivers — operationally focused intelligence
Our full study is built as a decision-support toolkit for 2026 action plans. Key deliverables include:
- Quantified market sizing (historical 2020–2025 and forecast 2026–2032) with scenario-based outlooks across demand, price, and regulatory sensitivity.
- A regulatory tracker and compliance playbook that maps certification requirements, filing pathways, and lead times for high-proof beverage ethanol production.
- Supply-chain heatmaps and supplier scorecards that rank counterparty risk on quality, capacity, logistics, and tariff exposure.
- Capital-expenditure templates and modular plant specifications for beverage-grade ethanol production, including purity, filtration, and testing benchmarks.
- Price-elasticity matrices, margin models, and stress tests that quantify the impact of feedstock swings and excise shifts on supplier and brand economics.
- An M&A and partnership pipeline with rationale-based target lists, valuation priors, and integration checklists for buyers seeking regional scale or specification capability.
- Commercial playbooks for beverage brands: procurement levers, co-pack partnerships, and traceability frameworks to support premium claims.
Each deliverable is supported by PW Consulting’s proprietary database and validated by interviews with plant operators, beverage manufacturers, and regulatory bodies. The downloadable report contains the granular figures and segment breakouts needed to build CapEx models, negotiate contracts, or initiate M&A diligence.
Competitive landscape — profiles and implications
Five firms exemplify the strategic archetypes active in the market today. Rather than disclosing proprietary share slices for each firm, we summarize strategic positioning and tactical implications for 2026 decision-makers.
-
Pristine Alcohol LLC (United States) — A specialist in neutral, high-purity food-grade ethanol positioned to serve premium spirit producers and RTD innovators. Strategic implication: domestic brands seeking supply-security and specification control should prioritize multi-year supply agreements with producers who can demonstrate consistent organoleptic neutrality and batch traceability.
-
Greenfield Global Inc. (Canada) — A vertically integrated manufacturer with recent capital commitment to beverage-focused capacity (notably a dedicated facility announced in 2025). Strategic implication: expect competitive pressure in North American beverage-grade supply as new capacity comes online; consider strategic alliances or off-take agreements to mitigate localized oversupply and price pressure.
-
Ethimex Limited (United Kingdom) — A sourcing and distribution specialist serving flavor, fragrance, and beverage markets. Strategic implication: distribution specialists are pivotal for brands without direct procurement scale. Emphasize contractual protections against quality variance and tariff pass-throughs when working via intermediaries.
-
Ultra Pure (United States) — A bulk supplier with a broad portfolio of high-proof spirits and industrial alcohols. Strategic implication: bulk suppliers remain essential for scale-focused buyers, but premium brands should layer technical acceptance criteria and testing regimes into purchase agreements to avoid downstream product risk.
-
Premier Innovations Group (United States) — Provides clean ethanol as part of turn-key beverage solutions. Strategic implication: turnkey providers reduce time-to-market for new beverage SKUs; however, buyers must evaluate IP, co-pack dependency, and exit options prior to committing to vertically bundled supply solutions.
The competitive landscape reflects a mix of manufacturers, distributors, and solution providers. In aggregate, competitor actions and the CR3/CR5 concentration data indicate a market where nimble, quality-focused firms can challenge incumbents through specification, service, and strategic alliances.
Operational playbook for management teams in 2026
-
Short-term (0–12 months): Shore up supply security via staggered contracts, increase quality auditing frequency, and implement a compliance readout for TTB and excise filing requirements. Institute raw-material hedges calibrated to weekly cash-flow sensitivities.
-
Medium-term (12–36 months): Execute targeted CapEx to upgrade purification and testing capabilities, or pursue strategic equity stakes in regional producers to capture quality-differentiated capacity. Reconfigure logistics networks to avoid tariff exposure and reduce cross-border transit costs.
-
Long-term (36+ months): Build differentiated provenance claims (traceability, sustainability) into product architecture. Consider M&A for backward integration into feedstock sourcing or forward integration into co-packing and branded RTD platforms to capture margin pools beyond raw ethanol.
Scenario planning and KPIs to monitor
Leading teams will stress-test strategies across three scenarios: constrained-supply (tight feedstock + compliance delays), balanced-growth (steady demand + incremental capacity), and accelerated-premiumization (higher-margin premium demand). Key metrics to track monthly and quarterly:
- Verified production throughput at ≥190 proof and proportion of batches passing organoleptic and purity spec on first test.
- Contracted vs. spot procurement mix and weighted-average feedstock cost per liter.
- TTB and local compliance lead times; number of outstanding regulatory actions.
- Tariff exposure as a percent of total cross-border volume.
- Customer concentration and share of revenue from premium specifications.
Decision-ready next steps
For CFOs and Heads of Supply Chain, the immediate priority is stress-testing 2026 procurement budgets against the PW Consulting elasticity models and updating contracting terms to reflect tariff/risk pass-through clauses. For CEOs and corporate development teams, the opening window for acquisitive scale or capability buys is defined by the current CapEx cycle — moves made in 2026 will set competitive economics into 2028 and beyond.
PW Consulting’s full Ethanol in Beverage Market report provides the granular figures, regional and application-level splits, supplier scorecards, and customizable Excel models necessary to translate this strategy into execution. This article intentionally omits those critical segment-level datapoints to ensure that decision-makers engage directly with the full dataset when constructing investment cases or contract negotiations.
Contact PW Consulting for the complete report, bespoke briefing, and workshop support to convert these insights into operational priorities for 2026. Our team will help you map the data to your balance sheet, optimize procurement design, and build the governance to manage regulatory risk and capture the premium opportunities emerging in the beverage ethanol value chain.
For detailed analysis of this topic, please visit the official page: Ethanol in Beverage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com