

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Clinical Reference Labs Market to Reach USD 2,020.9M by 2032 at 7.25% CAGR

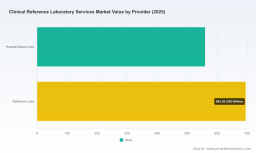
Clinical Reference Laboratory Services Market 2026: Strategic Preview for Enterprise Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise yet substantive preview of our full Clinical Reference Laboratory Services Market study. This briefing is designed to clarify the strategic choices executives must make in 2026 — and why this study should be part of the decision‑making toolkit. We expose the directional drivers, competitive dynamics, and operational levers that matter most, while intentionally reserving detailed subsegment tables and proprietary unit economics for the full report.
Clinical Reference Laboratory Services Market
Market trajectory and macro context
Between 2020 and 2025 the clinical reference laboratory market experienced steady expansion, reflecting a confluence of demographic demand, diagnostic innovation and increased outsourcing of complex testing. Using 2025 as the practical base year, our top‑line modelling shows the market continuing to scale through the forecast window (2026–2032) at a compound annual growth rate of 7.25%. By the end of the forecast the market more than doubles relative to the early‑2020 baseline, signaling sustained investment opportunities across diagnostics, molecular platforms and integrated service models.
Clinical Reference Laboratory Services Market
-
Historical momentum (2020–2025) created the structural runway: diagnostic adoption, molecular assay maturation, and expanded payer recognition have all contributed to a materially larger addressable market entering 2026.
Clinical Reference Laboratory Services Market -
The forecast period (2026–2032) is characterized by steady expansion at ~7.25% CAGR, driven by portfolio diversification (specialty and genomic assays), digital care workflows, and cross‑border clinical service models.
Why 2026 is an inflection year for corporate strategy
2026 is not just another year on the calendar; it is the moment many strategic initiatives launched in 2023–2025 begin to converge operationally and financially. For leadership teams planning capital allocation, partnership formation or M&A, several calendar‑sensitive realities make 2026 decisive:
-
Operational scale advantages will crystalize as networks that invested early in automation and digital sample logistics push unit costs down.
-
Reimbursement and regulatory adjustments that were proposed or piloted in prior years come into sharper focus, altering revenue recognition timetables for new tests.
-
Telehealth integration and remote specimen collection programs — now moving from pilot to roll‑out in multiple markets — change the channel economics for reference services.
Consequently, 2026 is the year to choose between three high‑level strategic postures: scale‑and‑consolidate, differentiate through specialty niches, or partner tightly with care delivery and digital health platforms. Each choice carries distinct investment profiles and timing implications explored in our full work.
Market dynamics that determine winners and losers
The report frames market dynamics across five interdependent vectors that will determine competitive advantage over 2026–2032:
-
Regulation and accreditation: Compliance requirements and HHS certification continue to shape addressable markets and buyer confidence. Being listed on federal registries or meeting new accreditation thresholds materially affects contract eligibility with large public and private payers.
-
Reimbursement regimes: Payer policy remains a gating item for rapid adoption of high‑value molecular and specialty assays. Shifts in fee schedules or coding clarity can accelerate or compress revenue curves for new tests.
-
Workforce and automation: A persistent shortage of skilled lab technologists increases the premium on automation, laboratory information systems and workflow redesign. Early adopters of automated sample handling and AI‑assisted interpretation are already realizing lower error rates and faster turnaround.
-
AI and digital diagnostics: Artificial intelligence is moving from pilot analytics into core diagnostic workflows — improving assay interpretation, triage and sample routing. This improves throughput and supports differentiated service SLAs.
-
Supply chain and outsourcing: The strategic decision to insource versus outsource specialized testing is increasingly guided by resilience and cost curves. Public health planning and HSE guidance in multiple geographies underscore the benefits of outsourced specialty capacity to manage surge events and rare assays.
Competitive landscape — structure, players and strategic implications
The market has moderate concentration: the share occupied by the three largest firms and the leading five players highlights both significant national players and meaningful room for niche specialists. This competitive structure produces a mixed landscape of scale economics and differentiated clinical capabilities.
-
Clinical Reference Laboratory, Inc. — a large privately held U.S. reference lab with strengths in toxicology, workplace testing and personalized medicine — continues to leverage certification advantages and an extensive commercial client base. Its profile makes it an attractive partner for employers and public sector contracts.
-
Quest Diagnostics and LabCorp — both operate integrated reference networks and provide professional laboratory management to health systems. Their investment cadence and strategic alliances (for example, LabCorp’s 2025 collaboration with a major telehealth provider) signal an emphasis on channel expansion and care integration.
-
Mayo Clinic Laboratories and ARUP — research‑oriented, clinically integrated reference providers — compete on the complexity and rarity of assays, and by leveraging academic specialty expertise to command premium pricing and referral flows.
-
Sonic Healthcare, Eurofins, Synlab and Unilabs — international networks pursuing scale through acquisitions, product launches and cross‑border platform plays. Recent activity (notably Eurofins’ acquisition of a U.S. kidney disease testing specialist and Synlab’s launch of a clinically validated bipolar disorder test) shows how M&A and product innovation are used to expand specialty footprints and clinical breadth.
Strategic implication: incumbents with national networks will continue to pursue scale and channel partnerships, while specialist labs and vertically integrated academic providers will compete on clinical differentiation. New entrants should plan either to plug into existing networked logistics or to develop a clear clinical niche with evidence that justifies payer support.
What the PW Consulting report delivers for 2026 decision‑makers
The full study is intentionally practical. It is structured to move teams from situational understanding to executable programs over 6–18 months. Key deliverables include (high level):
-
Proprietary market sizing and scenario models that allow you to stress‑test revenue outcomes under differing reimbursement, adoption and geographic rollout assumptions for 2026–2032.
-
Competitive benchmark matrices with capability maps — highlighting where scale, specialty expertise, digital capabilities and regulatory certifications create defensible positions.
-
M&A playbook and valuation reference points tailored to reference laboratory transactions, including integration scorecards for assay portfolios, IT interoperability and logistics.
-
Operational playbooks for automation adoption, workforce transition and AI governance that reduce implementation risk and shorten time‑to‑value.
-
Regulatory and reimbursement decision frameworks that orient evidence generation plans, coding strategy and payer engagement priorities.
-
Commercial go‑to‑market roadmaps for partnerships with telehealth platforms, health systems, and employer groups — including sample pricing constructs and contract guardrails.
These elements are delivered with supporting annexes: contract templates, KPI dashboards, risk heatmaps and a prioritized action plan calibrated for executives focused on value creation in the 18–36 month horizon.
How to use the study in 2026 strategic planning cycles
Use the study to accelerate three core decisions:
-
Capital allocation: identify which combinations of lab automation, assay development and distribution logistics offer the shortest path to margin expansion under varying reimbursement scenarios.
-
Partnerships and channel strategy: define whether partnership with telehealth platforms, health systems or payers yields better returns than greenfield expansion in target markets.
-
M&A and portfolio prioritization: deploy our M&A playbook to size acquisition targets, model integration economics and set bid ceilings that protect downside while capturing upside synergies.
Final note — what we intentionally withhold and why
True to the “trailer” principle, this preview demonstrates methodological depth and decision relevance while withholding granular subsegment revenues, market shares by region/application, and detailed unit economics. These elements are core intellectual property of the full report and necessary for transaction‑level diligence and contract negotiation. If your team requires the granular models, scenario outputs and annexed templates, the comprehensive study provides them in downloadable, workshop‑ready formats.
Contact PW Consulting to schedule a briefing and scenario workshop: use the study to stress‑test your 2026 strategic choices and convert diagnostic market growth into defensible enterprise value.
For detailed analysis of this topic, please visit the official page: Clinical Reference Laboratory Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com