

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wind Power Flange Market to reach USD 1,162.9M by 2032 (7.35% CAGR)

Wind Power Flange Market — Strategic Outlook for 2026 Decision-Making
Executive summary
As governments and utilities accelerate wind deployments, the market for wind power flanges is entering a sustained growth phase. PW Consulting’s base-year analysis (2025) shows the global market has expanded materially over the last five years, and our forecast through 2032 projects continued double-digit expansion in aggregate terms. The market is expected to grow at a compound annual growth rate (CAGR) of approximately 7.35% over the forecast period (2026–2032), with total market value moving from roughly USD 703 million in 2025 toward the end-period horizon in 2032. For executives making capital, procurement or M&A decisions in 2026, the commercial windows to secure scale, certification and strategic partnerships are both time-sensitive and consequential.
Wind Power Flange Market
Why this research matters for 2026 choices
- Market timing: 2026 is the inflection year in our scenario set where capacity commitments and offshore project awards meaningfully shape supplier economics. Pre-emptive capacity or partnership moves executed in 2026 will determine access to growth through the remainder of the forecast period.
- Supply-chain risk management: Raw material premiums and manufacturing technology choices (forging vs. ring-rolling) materially affect margins and timelines. Suppliers and OEMs need a 24–36 month roadmap to de-risk sourcing and logistics for large-diameter flanges.
- Regulatory gating: Certification and local-content requirements in major procurement tenders create non-price entry barriers. Companies that secure required certifications and local presence by mid‑2026 position themselves for multi-year contracts.
Market trajectory — headline data and implications
Historical momentum from 2020 to 2025 shows consistent expansion in installed capacity upstreaming demand for flanges; the market value grew from the low hundreds of millions USD to approximately USD 703 million by 2025. Our modeling, which incorporates technology substitution, regional tender timing and material-cost scenarios, indicates a steady CAGR of ~7.35% through 2032, with sizeable uplift in absolute terms by the end of the forecast period. This trajectory validates continued supplier investment but also underscores the importance of targeted strategy: simply expanding capacity without securing order pipelines, certifications and logistics will compress returns.
Wind Power Flange Market
Competitive landscape — who matters and why
The market combines established regional forging specialists with global engineering vendors. PW Consulting’s qualitative assessment highlights several archetypes that shape competitive dynamics:
Wind Power Flange Market
- Large integrated forgers with global footprint — exemplified by firms that combine large-capacity presses with multi-country manufacturing reach, positioning them to serve both onshore and offshore projects.
- Regional specialists — medium-size producers with deep local relationships and cost advantages, particularly relevant for localized procurement mandates and smaller onshore projects.
- Niche technical vendors — boutique manufacturers focused on very large-diameter or non-standard flanges, where engineering expertise and customization command pricing premiums.
Representative companies profiled in our study include established manufacturers and distributors across Asia, Europe and North America. Each profile in the full report includes production capabilities, plant footprints, certifications, typical turbine classes served, and strategic positioning (cost leader, specialist, or integrated supplier). Recent market moves — for example cross-border joint ventures and high-tonnage press commissions — are altering competitive dynamics and are examined in detail in the report.
Operational and technological dynamics
- Manufacturing scale: Investments in high-tonnage forging presses and ring-rolling lines are the principal levers to produce large-diameter flanges for modern turbines. The capital intensity means lead-time to commercial-scale output is measured in quarters, not weeks.
- Process innovation: Seamless ring-rolling reduces material waste and improves dimensional integrity relative to traditional forging approaches — our sector analysis cites waste reductions that translate into both cost and sustainability benefits for large-volume producers.
- Material premiums: Offshore-grade alloy steels and corrosion-resistant treatments attract significant price premiums versus standard grades. These premiums must be modeled into bid strategies for offshore substructure components and influence decisions on in-house metallurgical capabilities.
- Logistics and installation: Large flanges generate transport and handling complexity — decisions about plant location, co-located logistics hubs and port access materially affect landed cost and schedule reliability for offshore projects.
Regulatory environment and procurement trends
Regulatory and procurement requirements are increasingly decisive in tender outcomes. Key dynamics that our 2026-ready strategies must account for include:
- Local content and supplier qualification clauses that require on-the-ground capabilities or approved domestic partners for public utilities and state-backed tenders.
- Enhanced certification regimes for offshore structures focused on fatigue life, welding standards and corrosion protection — these are becoming non-negotiables for substructure flanges.
- Procurement hygiene such as mandated ISO welding certifications (e.g., ISO 3834) in specific markets, which translates into timeline and CAPEX implications for suppliers that must retrofit capabilities.
Strategic plays for 2026 — pragmatic options by player type
Our actionable playbook is calibrated for suppliers, OEMs and financial investors contemplating moves in 2026. Each recommendation is supported by scenario modeling and sensitivity testing in the full report.
- For large suppliers: Prioritize capacity sequencing and certification roadmaps. Invest selectively in large-tonnage forging capacity or secure long-term OEM contracts before large capital outlays. Consider JV partners in target geographies to satisfy local-content rules.
- For regional manufacturers: Leverage speed-to-market and cost advantage for onshore projects; pursue targeted certification upgrades to compete for larger offshore components where margin premiums justify investment.
- For OEMs and project developers: Integrate flange procurement earlier in project planning to lock supply and avoid price escalation. Employ dual-sourcing strategies for critical forgings to hedge material and logistics risk.
- For investors and private equity: Assess platform consolidation opportunities — bolt-on acquisitions of regional forgers with complementary certifications or strategic ports can accelerate go-to-market without the full greenfield timeline.
Illustrative recent market developments (directional)
- Strategic JV formations in Southeast Asia are emerging as a popular route to access fast-growing onshore pipelines while satisfying local supply rules.
- High-tonnage press additions by leading forgers reflect a bet on larger-diameter demand from both nearshore and offshore segments; these investments are reshaping capacity maps and time-to-market dynamics.
- Procurement mandates and updated offshore standards in major markets have already started to reallocate premium volumes toward certified suppliers with proven metallurgical and welding credentials.
What the full PW Consulting report delivers (practical contents)
The published report is designed as an operational toolkit for 2026 decision-makers. Key deliverables include:
- Market sizing and trend models (historical 2020–2025 and forecast 2026–2032) with scenario toggles for material cost, tender timing and technology adoption rates.
- Supplier scorecards and plant-level capability matrices (certifications, press capacity, geographical reach, typical turbine classes served).
- Contracting and procurement playbooks including template bid pricing models, certification timelines and logistics cost estimators.
- Opportunity matrix by strategic theme (capacity expansion, JV/localization, vertical integration, and M&A) with prioritized actions for 12–36 month horizons.
- Risk heatmaps covering raw-material volatility, regulatory shifts and execution bottlenecks for large-diameter forgings.
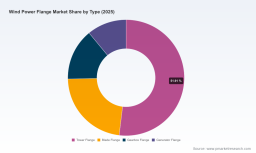
Note: The online report contains the full set of regional and application splits, concentration metrics, and price curves. This preview intentionally omits core segment tables and granular regional shares to preserve the report’s tactical value — clients and subscribers can access those datasets through the source link.
How to use these insights in 2026 planning
- Align capital allocation with contract pipelines: defer large greenfield spending absent bilateral offtake or secured OEM commitments; prioritize partnerships that shorten commercial lead times.
- Certify now, bid later: pursue required welding and material certifications immediately to be eligible for the next wave of offshore tenders.
- Model material scenarios: incorporate alloy-premium and recycling benefits into bidding tools; small percentage changes in alloy prices or waste rates materially shift competitiveness.
- Adopt a portfolio approach: balance high-margin niche engineering work with volume contracts to stabilize utilization and finance capacity turns.
Closing — the strategic decision window
2026 represents a strategic inflection point for actors across the wind power flange value chain. The market’s medium-term growth profile offers attractive expansion opportunities, but success will depend on timing, certification readiness, and the ability to hedge material and logistics risks. PW Consulting’s full Wind Power Flange Market report equips leaders with the granular data, supplier intelligence and decision-support tools required to convert market growth into durable commercial advantage. For access to the complete datasets, regional and application splits, supplier scorecards and our interactive scenario model, please visit the report landing page.
For detailed analysis of this topic, please visit the official page: Wind Power Flange Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com