

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shotcrete Accelerator Market to Reach USD 538.3 Million by 2032 at 7.85% CAGR

Shotcrete Accelerator Market — Strategic Preview for 2026 Decision-Makers
Executive Trailer
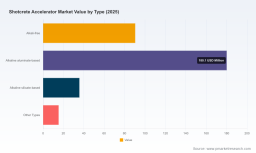
PW Consulting’s latest market study on Shotcrete Accelerators frames a decisive moment for producers, contractors, and investors as the sector enters a new growth phase. Anchored on a 2025 base year and a robust historical series (2020–2025), our model projects the market to expand from an estimated USD 321.5 Million in 2025 to USD 538.3 Million by 2032, operating at a compound annual growth rate of 7.85% through the forecast horizon. These headline figures reflect durable demand from tunneling, underground construction and mining activities, shifting product preferences, and renewed investment in infrastructure across multiple markets.
Shotcrete Accelerator Market
Why this report matters for 2026
- Tactical timing: 2026 is the first full planning cycle in which recently announced capacity moves and regulatory clarifications materially reshape supply-side choices. Companies that update strategy this year will lock in manufacturing footprints, procurement contracts, and product road maps that determine competitiveness through 2032.
- Margin preservation under volatility: Raw material price swings and the uneven pace of product adoption create acute margin and operational risks that require actionable mitigation plans — procurement, hedging, and formulation redesign.
- Commercial differentiation: Accelerators are now as much a systems play (compatibility with wet-process equipment, rebound reduction, fast early strength) as a chemistry play. First movers who couple performance guarantees with field service capture disproportionate share gains.
High-level Market Dynamics
Our analysis identifies three structural dynamics shaping the market in 2026 and beyond.
Shotcrete Accelerator Market
- Technology and product substitution: Alkali-free gel accelerators have accelerated substitution away from traditional sodium silicate and other high-alkali chemistries. This transition is driven by occupational safety, environmental restrictions, and equipment compatibility with modern wet-process shotcrete systems. For manufacturers, this means reformulation investments and certification costs that are now table stakes.
- Supply-chain and input-cost volatility: Nitrogen-based intermediates and specialty sulfates underpin several accelerator chemistries. Energy market disruptions in recent years produced material price swings that directly compressed margins for formulators. Manufacturers with vertically integrated supply or long-term offtake arrangements are better insulated.
- Regulation and project-level specifications: Several jurisdictions have moved to mandate alkali-free solutions for projects in sensitive water environments. Where specification certainty exists, procurement cycles shorten and premium pricing becomes more sustainable; where it does not, competition remains primarily price-based.
Competitive Landscape — What to watch
The market exhibits moderate concentration, with close to half of market volume tied to the top three players and a clear dominant group among the top five — a structure that supports both scale advantages and tactical openings for agile specialists. Key incumbent strategies and capabilities are summarized below to highlight where competitive advantage currently clusters.
Shotcrete Accelerator Market
- Sika AG (Baar, Switzerland) — A leader in alkali-free liquid accelerators through its Sigunit® series and a strong presence in dry powder variants. Sika’s advantage is deep field service, global distribution, and integration across construction chemistries, enabling bundling opportunities on major tunneling projects.
- BASF SE (Ludwigshafen, Germany) — Offers a broad accelerator portfolio across MasterRoc® and Rheobuild® lines, addressing both dry- and wet-mix applications. BASF’s strengths are R&D scale and formulation breadth, allowing rapid responses to specification shifts and OEM partnerships.
- Mapei S.p.A. (Milano, Italy) — Focused product optimization for wet-mix European applications and a strong technical-service model that supports performance claims for contractors operating in mature markets.
- GCP Applied Technologies, The Euclid Chemical Company, Fosroc, Chryso, Denka, Normet and MC-Bauchemie — Each offers differentiated strengths: niche chemistries, regional manufacturing, equipment integration, or service-led commercialization. Normet, for example, demonstrates the commercial upside to integrating accelerators into complete spray systems.
Recent strategic moves underscore the competitive tempo. Master Builders Solutions announced a U.S. capacity expansion in May 2026 to support rising underground construction volumes. Chryso’s heightened trade-show presence in early 2026 signals an intensified effort to win specification and precast partnerships. Expect further product and capacity announcements as players chase market access and specification-driven premiums.
Where value is created (and lost)
- Value capture through formulation leadership: Alkali-free, low-rebound, fast-strength chemistries that also reduce dust and improve sprayed surface quality command price premiums and shorten construction schedules — a clear commercial lever.
- Operational resilience: Manufacturers with diversified raw-material sourcing, proximity to key underground construction clusters, and flexible production formats (liquid vs. powder packaging) maintain higher realized margins through cycles.
- Service and systems integration: Companies offering technical support, on-site dosing equipment, and training create switching costs and defend margin erosion from commoditization.
Practical contents of the PW Consulting report (what you will get)
The full study is designed as a hands-on playbook rather than a descriptive summary. Highlights include:
- An interactive market model (2020–2032) with scenario switches for demand drivers, price trajectories and substitution rates.
- Segment-level demand drivers and sensitivity matrices that quantify the P&L impact of raw-material price swings and regulatory shifts.
- A supplier benchmarking suite that evaluates technology, manufacturing footprint, distribution reach, and field-service capabilities across leading vendors.
- Product-level road maps and R&D scorecards identifying the most defensible chemistries and formulation trade-offs for next-generation accelerators.
- Procurement and hedging playbooks that translate supply-risk scenarios into recommended contract structures and inventory strategies.
- An M&A and partnership matrix highlighting targets that accelerate access to equipment integration, regional coverage, or differentiated chemistries.
- Country- and project-level Go/No-Go checklists for buyers and suppliers to assess specification, logistics, and compliance risks prior to bidding large underground projects.
- Primary research appendices: interviews with technical managers, procurement heads, and project owners; raw-material price histories; and regulatory compliance maps.
Actionable strategic recommendations for 2026
Below are prioritized moves we recommend for different stakeholders preparing decisions in 2026.
- For accelerator manufacturers:
- Prioritize alkali-free gel development and certification where regulatory adoption is advancing. Treat wet-process compatibility as a key performance metric.
- Mitigate raw-material exposure through supplier diversification, selective vertical integration, and multi-year purchasing agreements — especially for nitrogen- and sulfate-based inputs.
- Evaluate localized pack and formulation strategies (liquid vs. powder) to balance freight costs and on-site handling constraints.
- For contractors and miners:
- Negotiate supplier contracts that bundle product supply with on-site technical services and performance guarantees tied to early strength and rebound reduction.
- In procurement rounds, include technical scoring for equipment compatibility to avoid productivity losses post-award.
- Consider pilot programs with integrated suppliers (accelerator + spray equipment) to de-risk large tunneling contracts.
- For investors and private equity:
- Target platform plays that combine formulation capability with regional manufacturing. Track potential roll-up targets that offer unique chemistries or OEM relationships.
- Use the interactive scenario model in this report to stress-test returns under alternative raw material and regulatory outcomes.
Risks and watch items into 2026
- Raw material price volatility — recent multi-year swings materially affect cost of goods sold and can compress margins rapidly if not hedged.
- Regulatory changes that accelerate mandatory use of alkali-free chemistries in additional jurisdictions could reprice demand and favor market leaders with certified portfolios.
- Equipment compatibility and contractor acceptance remain adoption bottlenecks in some markets; success depends on credible field proofs and warranty frameworks.
Concluding call to action
This preview outlines the strategic stakes and the practical levers available to participants in 2026. PW Consulting’s full Shotcrete Accelerator Market report provides the granular segmentation, regional roll-ups, product-by-application forecasts, and an interactive financial model you need to move from intent to implementation. It also compiles the primary-source evidence and company-level assessment that will enable decisive action on capacity, procurement, R&D, and M&A decisions this year.
For executives planning capital allocation, product road maps, or transaction activity in 2026, the window to operationalize these insights is narrow. Access the full study to see the underlying segment detail, model assumptions, and supplier scorecards that support durable, revenue-anchored decisions.
For detailed analysis of this topic, please visit the official page: Shotcrete Accelerator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com