

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Crude Sulfate Turpentine Market to Reach USD 241.5M by 2032 (5.65% CAGR)

Crude Sulfate Turpentine Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As companies reposition portfolios for a bio-based future, crude sulfate turpentine (CST) has shifted from an industrial by‑product to a strategic feedstock. PW Consulting’s latest market study — with base year 2025, historical coverage 2020–2025 and a forecast window spanning 2026–2032 — quantifies that transition and converts it into decision-ready options. Our model projects the global CST market to grow from a 2025 baseline to a materially larger market by 2032 at a compound annual growth rate (CAGR) of 5.65% (currency: USD; revenue unit: Million). This industry brief outlines why that projection matters for 2026 corporate choices, what immediate risks and opportunities executives must prioritize, and how the full PW Consulting report equips leaders to act.
Crude Sulfate Turpentine Market
Why this study matters for 2026 decision-makers
-
Procurement and cost control: volatile feedstock dynamics and supplier pricing actions in early 2026 have already created procurement windows and hazards that will influence contractual strategies through 2028.
Crude Sulfate Turpentine Market -
Regulatory and market access: tightening regulatory frameworks in key markets are re‑shaping compliance costs and market entry criteria — making certification and traceability strategic requirements rather than optional credentials.
Crude Sulfate Turpentine Market -
Value chain repositioning: producers, refiners and end‑users are all considering upstream integration and downstream capture of higher‑margin terpene derivatives; timing these moves is critical to preserve margins while scaling.
-
M&A and partnership prioritization: a moderately concentrated supplier landscape amplifies the impact of consolidation, making targeted transactions potentially transformative for supply and technology access.
Report scope and the practical outputs you can use
PW Consulting’s full report is deliberately practical. It blends a rigorous macro forecast with operational tools designed for 2026 execution, including:
-
An audited market-size time series (2020–2025) and scenario-based projections 2026–2032 using a base-case CAGR of 5.65%.
-
Three investment and pricing scenarios (base, upside, downside) calibrated to regulatory paths, feedstock shocks, and adoption curves for bio-based alternatives.
-
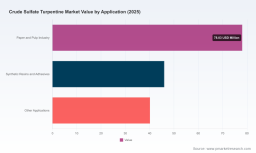
Supply‑demand balances and trade‑flow mapping by origin and destination (detailed regional and application splits are included in the full report for licensed users).
-
Supplier scorecards and a five‑factor concentration assessment (market concentration metrics are provided to help prioritize counterparties).
-
Actionable procurement templates — from term‑sheets to indexation clauses — and a certification roadmap for ISCC PLUS and equivalent schemes.
-
M&A heatmaps, buyer synergies, and an integration checklist for acquirers seeking scale or technology access.
Market dynamics and near‑term inflection points
Between 2020 and 2025 the market experienced steady growth, reflecting rising industrial demand for pine‑derived terpenes and increased premiumization of bio‑based inputs. The 2026–2032 forecast period embeds structural drivers that include: renewed demand from adhesives, resins and fragrance end‑markets pursuing renewable feedstocks; regulatory preference in the EU for certified bio‑based alternatives; and operational shifts at pulp and paper mills that control the majority of upstream CST volumes.
Regulatory developments are decisive. European chemical regulation and the Green Deal’s incentives for renewable feedstocks are materially raising the cost of market entry for suppliers that cannot demonstrate sustainable sourcing. Industry tracking indicates that by 2028 ISCC PLUS or equivalent certifications will be the de facto market access ticket in many European segments. Concurrently, North American VOC and safety standards are increasing compliance burden, raising operating costs and creating strategic arbitrage between compliant and non‑compliant suppliers.
Supply‑side signals are already visible. A major supplier announced a global price adjustment in mid‑2026, and some producers have accelerated certification efforts to secure high‑value European contracts. These moves underscore two realities: (1) price discovery for CST is increasingly sensitive to a few upstream players; and (2) certification and traceability are no longer future considerations but active competitive levers.
Price trajectory, volatility and risk scenarios
Our base‑case trajectory uses the market growth profile to simulate revenue expansion while modeling price and volume shocks. The CET (cost, extraction, and transport) component of CST is linked to pulp mill economics and broader tall oil/turpentine markets. Short‑term price spikes — whether through coordinated supplier price actions or upstream feedstock shortages — can materially alter downstream margins.
We model three plausible 24‑month scenarios for 2026–2027:
-
Base case (CAGR-aligned): steady demand growth at or near the 5.65% trajectory, with supplier pricing normalizing after short-term adjustments.
-
Downside (policy or demand drag): slower substitution and higher compliance costs depress demand growth, compressing margins and forcing excess capacity adjustments.
-
Upside (accelerated bio pivot): faster regulatory enforcement and rapid adoption in high‑value fragrance and adhesive markets, causing tightness in certified supply and premium pricing.
For procurement teams, the immediate implication is to adopt dual tracks: lock in portioned volumes under longer‑term contracts with sustainability clauses, while retaining flexibility through spot access and optionality clauses. For producers, hedging against feedstock cost volatility and accelerating certification efforts are priority actions to protect premiums.
Competitive landscape — who matters and why
The CST supplier and consumer ecosystem includes integrated pulp and paper players, specialty chemical producers, aroma corporations and dedicated pine‑chemical firms. Market concentration is moderate: the three largest suppliers account for a meaningful portion of supply, and the top five materially increase supplier leverage (CR3: ~42.5%; CR5: ~58.2%). This mix creates both supply risk and strategic opportunity.
-
Kraton Corporation — a specialty polymers and pine chemical player — now markets certified terpene products and has signalled pricing power through recent price actions. Their certification achievements and market moves make them a bellwether for premium CST supply.
-
DRT — a long‑standing European resin and terpene specialist — combines deep process know‑how with established footprints in fragrance and nutrition chains, positioning it to convert regulatory shifts into market share.
-
Symrise and IFF — global fragrance and flavor leaders — continue to anchor demand for high‑purity terpenes, integrating supplier relationships into product innovation pipelines.
-
Pulp‑integrated suppliers (e.g., Stora Enso, UPM, Georgia‑Pacific) — as co‑product owners they influence volume availability and can prioritize captive downstream value creation.
-
Specialist suppliers (e.g., Pine Chemical Group, Ingevity, Lawter, Arakawa, Privi) — nimble players that can pursue niche high‑value segments and engage in toll‑refining or co‑development agreements.
For acquirers and strategic buyers, the competitive map suggests two high‑probability paths to value: acquiring upstream feedstock control or acquiring downstream refining and formulation capabilities that capture terpene value uplift.
Strategic playbook for 2026
To convert market intelligence into advantage, PW Consulting recommends a prioritized playbook for executive teams:
-
For buyers (end‑users): adopt a tiered sourcing strategy that combines certified long‑term supply for core needs with flexible spot capacity for innovation and seasonal variation. Insert sustainability pass‑through clauses and audit rights into contracts.
-
For producers: fast‑track ISCC PLUS (or equivalent) certification, invest in traceability and increase downstream partnerships with fragrance and adhesive companies to capture premium streams.
-
For investors: prioritize targets that offer either upstream feedstock control or differentiated refining/derivative capabilities. Use the PW M&A heatmap to screen for synergies and regulatory exposure.
-
For policy and compliance teams: map exposure to EU REACH, VOC standards and potential carbon policies; embed certification timelines into capex and operating plans to avoid market access shocks.
-
For R&D and product teams: accelerate formulation work that substitutes petrochemicals with pine‑derived terpenes where performance parity or sustainability premium exists.
How PW Consulting’s full report supports execution
The intent of this brief is to reveal strategic contours while reserving the granular segmentation and supplier metrics that underpin executable plans. The full PW Consulting report contains the proprietary data and tools executives will need to implement the playbook: regional and application breakdowns, supplier pricing curves, a certification readiness checklist, contract templates, and a scenario modeling workbook aligned to the 2026–2032 forecast horizon.
In an environment where regulatory preference and sustainability credentials are reshaping price formation and access, having validated demand forecasts, counterparty risk scores and a tactical procurement toolkit is not a luxury — it’s a strategic requirement. Our study translates a market projected to grow materially from its 2025 baseline into precise levers that procurement, strategy and M&A teams can activate now.
Next steps
Access to the full dataset and playbooks will enable you to: quantify exposure to supply concentration, model contract structures against our three scenarios, and prioritize investments that secure certified feedstock and downstream capture. PW Consulting is accepting briefings to discuss tailored strategic roadmaps and to run client‑specific scenario workshops for 2026 planning cycles.
For decision‑makers preparing budgets, supplier negotiations, or potential transactions in 2026, the timing is clear: translate this industry inflection into concrete actions before certification deadlines and supplier re‑pricing events crystallize the next market regime.
For detailed analysis of this topic, please visit the official page: Crude Sulfate Turpentine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com