

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LED Work Lights Market to Reach USD 338.9M by 2032, 4.1% CAGR

LED Work Lights Market — 2026 Strategic Preview
Executive snapshot
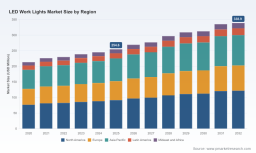
As organizations plan capital allocation and product roadmaps for 2026, the LED work lights market presents a modestly expanding, innovation-driven opportunity. Our latest analysis (base year 2025) benchmarks the global market at approximately USD 254.6 Million, up from about USD 213 Million in 2020 — reflecting steady demand across construction, industrial maintenance, and field-service applications. We forecast continued expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of roughly 4.1%, reaching a market size approaching USD 339 Million by 2032.
LED Work Lights Market
Why this study matters for 2026 decisions
- Capital planners: prioritize R&D and tooling investments where unit economics and product lifecycles align with mid-single-digit market growth.
- Product leaders: refine platform strategies (battery compatibility, modular mounts, and digital features) to capture share in a fragmented supplier landscape.
- Channel executives and distributors: rebalance assortments toward durable, integrated solutions while managing inventory risk during incremental demand shifts.
- Private equity and corporate development teams: identify consolidation and bolt‑on niches enabled by low-to-moderate market concentration.
Market dynamics shaping 2026 decisions
Two complementary forces underpin the market’s trajectory. On the demand side, ongoing activity in construction, industrial maintenance, and fleet services sustains baseline consumption of portable and mounted LED work lights. On the supply side, technology advances — particularly battery energy density, LED efficacy, thermal management, and ruggedization — continue to expand product utility and enable new form factors.
LED Work Lights Market
Historically the market has shown steady, mid-single-digit growth (2020–2025). Looking forward, our 2026–2032 forecast assumes a continuation of that pattern, adjusted upward slightly to reflect several secular factors: broader adoption of cordless battery platforms across trade tools, an increased premium on safety and hazard-rated lighting in regulated industries, and incremental replacement demand as legacy incandescent and halogen units are retired.
LED Work Lights Market
At the same time, the market structure remains disaggregated: the top three suppliers account for just over one-fifth of global sales, and the top five capture less than one-third — a concentration profile that favors nimble entrants, private-label players, and differentiated niche specialists. That fragmentation shapes go-to-market dynamics, pricing elasticity, and consolidation potential in 2026.
Competitive landscape — what leading players signal
Our competitive scan focuses on firms that are shaping product and channel expectations today. Rather than provide exhaustive rank tables in this preview, below we synthesize strategic positioning and practical implications for each archetype of competitor.
- Platform-integrators (e.g., Milwaukee Tool, DeWalt, Makita, Stanley Black & Decker) : These vendors leverage battery-platform ecosystems and professional trade channels. Their strengths lie in cross-sell opportunities with power tools, system-level warranties, and field-proven durability. For companies targeting pro trades, competing on battery-system compatibility and serviceability will be table stakes in 2026.
- Industrial and hazardous-environment specialists (e.g., Larson Electronics, Banner Engineering, Aurora Lighting) : These suppliers focus on application-engineered solutions — explosion-proof units, mounting systems for cranes and rigs, and long-life luminaires for continuous-process plants. As safety regulations and uptime expectations tighten, end-users are willing to pay for certified, high-reliability fixtures.
- Portable and personal lighting specialists (e.g., Ledlenser, Streamlight, Feit Electric) : These firms compete on beam control, runtime, ergonomics, and rechargeable chemistries. They are well placed to win service, security, and emergency response segments where portability and precision are priorities.
- Vehicle and off-road specialists (e.g., Baja Designs, Nilight) : These players target heavy-duty vehicle and fleet applications with high-output and robust mounting systems. Their go-to-market is often OEM-direct, or through specialized aftermarket channels.
Recent product activity underscores these competitive moves. For example, in late 2025 a major trade-focused brand expanded its offering with high-definition area lights that integrate USB charging and pivoting mounts — a signal that multi-function ergonomics and on-device charging are escalating seller differentiation. Separately, suppliers active in hazardous industries released explosion‑proof drop-lights with purpose-built protective features, highlighting continued investment in regulatory- and safety-driven product innovation.
What’s inside the full PW Consulting report (practical deliverables)
The full study is designed as an operational playbook for 2026 decision-making. Highlights include:
- Validated market-sizing and three-layer forecast (TAM/SAM/SOM) with scenario sensitivity for commodity shock, accelerated electrification, and regulatory tightening.
- Segmentation by product family, mounting type, and end-use application — with actionable buyer personas for procurement teams (note: detailed tables and split percentages are available in the full report).
- Competitive diagnostic: product-matrix, go-to-market archetypes, pricing benchmark, and patent/innovation heatmaps to inform feature prioritization.
- Supply-chain and BOM analysis: key component levers (LED chips, drivers, batteries, optics, thermal solutions) with supplier concentration and substitution risk assessments.
- Channel strategy playbooks: distribution economics, inventory ladders, and promotion calendar recommendations tailored to trade, industrial distributors, and e-commerce.
- M&A and partnership target shortlist with high-level valuation heuristics for tuck-ins that improve margin or fill capability gaps.
- Implementation-ready KPIs and a 12–18 month roadmap template to support commercial rollouts, product refreshes, and field trials.
Strategic recommendations for 2026
- Manufacturers (OEMs) : Prioritize platform compatibility (battery and mount systems) and modular design to shorten SKUs and reduce inventory complexity. Invest selectively in ruggedization and certification where industrial customers pay a premium.
- Distributors and retailers : Restructure assortments toward high-turn, higher-margin integrated solutions and offer bundled service/warranty programs for trade customers to improve stickiness.
- Component suppliers : Accelerate partnerships around thermal management and optics to enable higher-lumen-per-watt products that extend battery runtime without adding weight.
- Private equity / M&A actors : Target consolidation in niche, high-reliability segments where certification and domain expertise create defensible value and attractive margin expansion opportunities.
- End-users (construction, plant maintenance, fleet operators) : Treat lighting as an operational-expense lever — standardize on fewer platforms to reduce spare-parts complexity and negotiate lifecycle-based service agreements.
What we intentionally withhold here — and why
This preview intentionally demonstrates analytical depth while withholding granular subsegment tables, region-by-region splits, and precise price decks to preserve the utility of the full report for paid subscribers and clients. Those detailed breakdowns — including segment-by-segment forecasts, channel margins, and pricing elasticities — are the tactical inputs teams need to execute procurement, R&D prioritization, and M&A diligence in 2026. If your team requires those tables (or custom scenarios), the full report and our consultancy services provide them along with the supporting models.
How to use these insights in 90 days
- Week 1–2: Run a gap analysis against your current portfolio versus the platform-integrator and specialist archetypes described above.
- Week 3–6: Prioritize three design experiments (e.g., battery-agnostic mount, explosion-proof variant, integrated charging) and source BOM improvements from supplier partners identified in the report.
- Week 7–12: Pilot a channel test with simplified SKUs and bundled service offerings; measure conversion lift and return rates to inform scale decisions.
In a market characterized by steady baseline growth, accelerating technology substitution, and low headline concentration, the difference between incremental and breakout performance will be determined by platform choices, channel alignment, and speed of execution. Our 2026-focused study provides the market sizing, competitor intelligence, and tactical playbooks to convert those strategic choices into measurable commercial outcomes.
Next steps
To access the full dataset, segmented forecasts, and executable annexes referenced in this preview, please visit the PW Consulting report page or contact our strategy team for a tailored briefing and scenario-run that applies the model to your P&L and product roadmap.
For detailed analysis of this topic, please visit the official page: LED Work Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com