

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Occupational Medicine Market to reach USD 12.23B by 2032 at 4.1% CAGR

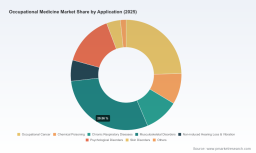
Occupational Medicine Market 2026: Strategic Preview for Decision-Makers
As organizations recalibrate workforce strategy in a post‑pandemic, regulation‑intensive environment, occupational medicine has moved from a compliance checkbox to a strategic risk and value lever. PW Consulting’s new market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—shows a steady market expansion from established pre‑pandemic levels to a projected global market of approximately USD 12.2 billion by 2032, driven by a mid‑single‑digit compound annual growth rate (CAGR) of 4.1% across the forecast period. For executives making 2026 investment, partnership, or M&A decisions, understanding the structural forces behind that growth is now table stakes.
Occupational Medicine Market
Why this study matters for 2026 strategic choices
-
Actionable foresight: The report synthesizes historical trends (2020–2025) and forward scenarios (2026–2032) so buyers can move beyond static benchmarking to anticipate where demand for services, surveillance, and digital care will accelerate.
Occupational Medicine Market -
Regulatory pressure as a growth driver: Recent shifts in occupational safety regulation and enforcement increase the economic imperative for employers to invest in occupational medicine services rather than absorb regulatory risk.
Occupational Medicine Market -
Market structure clarity: The market demonstrates moderate concentration—large national players coexist with many regional and specialist providers—creating differentiated pathways for scale (roll‑ups, national service networks) and differentiation (specialist centers, digital platforms).
Data‑driven context: the macro picture
PW Consulting’s analysis finds that the occupational medicine market recovered and expanded since 2020, reaching an estimated USD 9.1 billion in 2025. Under our base forecast, the market grows to roughly USD 12.2 billion by 2032 at a 4.1% CAGR. That trajectory reflects a combination of persistent demand for clinical injury management and surveillance, rising employer spend on preventive and mental health services, and increasing spend driven by compliance requirements and expanded biological monitoring programs.
Importantly, the growth is not uniform: pockets of above‑average expansion exist where regulation, industrial activity, and healthcare access converge, while mature service lines face pricing pressure and digital substitution. The report maps these differential growth corridors and provides scenario tools to stress‑test investment theses against regulatory, reimbursement, and labor‑market shocks in 2026.
Key dynamics shaping 2026 decisions
-
Regulatory tightening and enforcement: Updated recordkeeping rules and more stringent exposure standards (including for silica and beryllium) raise the frequency and complexity of monitoring programs. Employers in regulated industries face higher compliance costs and amplified incentives to outsource occupational health services.
-
Higher penalty regimes: Escalating fines and more aggressive enforcement mean the expected cost of non‑compliance is rising—prompting procurement teams to shift from lowest‑cost vendors toward partners that can provide integrated compliance, surveillance, and reporting capabilities.
-
Reimbursement and coding clarity: New or clarified billing pathways for impairment and occupational evaluations shift the revenue profile for clinic‑based providers and shape payer contracting behavior. Operationalizing correct coding and documentation is a near‑term profit lever.
-
Digital care and telehealth: Remote triage, tele‑injury care, and virtual surveillance reduce marginal delivery costs and change the network economics for on‑site clinics versus centralized telehealth hubs.
-
Fragmented competitive landscape: The market is characterized by several national chains and a long tail of regional providers and specialty clinics, creating opportunities for consolidation, strategic partnerships, and geographic expansion.
Competitive landscape—what the leading players signal
Active incumbents and new entrants are taking distinct strategic postures that inform 2026 moves:
-
Large clinic networks (e.g., national occupational health operators) are pursuing footprint expansion and capability integration. Recent openings and network consolidation indicate a playbook focused on scale, standardized clinical pathways, and enterprise contracting with large employers and payers.
-
Integrated healthcare systems and hospital networks are leveraging existing clinical infrastructure to offer occupational health as part of broader employee health and specialty services, positioning on clinical expertise and complex case management.
-
Specialist and boutique providers continue to thrive by focusing on high‑complexity services (medical surveillance, impairment evaluations, rehabilitation) and by offering employer‑specific programs in high‑risk industries.
-
Telehealth and digital platforms are rapidly becoming essential partners for triage, follow‑up, and mental health services, enabling hybrid care models and supporting more efficient use of in‑person resources.
Notable recent activity underscores these patterns: leading operators have expanded their local footprints through new clinic openings and partnership models, while universities and hospital systems continue to position occupational medicine within broader clinical services. These moves both raise the bar for clinical quality and create acquisition targets for strategic buyers. PW Consulting’s company profiles and competitive matrices dissect positioning, capabilities, and likely next steps for the core suppliers operating in this market.
What PW Consulting’s report delivers to support 2026 planning
This study is built to be operational for corporate strategy, investor due diligence, and procurement optimization. Key deliverables include:
-
Forward‑looking market model—annualized projections (2026–2032) with sensitivity scenarios tied to regulatory intensity, labor cost inflation, and telehealth adoption rates.
-
Service and application roadmaps—segmentation by service type, clinical pathway, and application area (presented as demand vectors rather than raw shares) to help prioritize capability investments.
-
Competitive landscaping—detailed profiles of incumbent operators, capability heatmaps, recent development timelines, and likely M&A targets grounded in strategic fit and financial logic.
-
Commercial playbooks—go‑to‑market strategies for employers, provider networks, and new entrants, including contracting templates, KPI dashboards, and pricing levers tied to reimbursement pathways.
-
Regulatory and reimbursement impact analysis—actionable guidance on how recent OSHA changes and billing code clarifications affect revenue capture, required documentation, and program design.
-
Operational tools—implementation guides for hybrid telemedicine models, surveillance program templates, and ROI calculators for clinic openings vs. telehealth hubs.
Strategic choices for 2026 and near‑term execution checklist
-
Pursue capability adjacency or consolidation: If you are a regional provider, evaluate bolt‑on acquisitions that add surveillance analytics, tele‑triage, or specialty rehab to transition from episodic care to subscription‑style employer contracts.
-
Invest in compliance automation: Build or partner for automated OSHA reporting and biological monitoring workflows to reduce employer liability and capture higher‑value contracts.
-
Design hybrid delivery: Shift low‑complexity touchpoints to telehealth while protecting in‑person capacity for diagnostics and high‑complexity care. Track utilization and cost per case to justify hybrid capex decisions.
-
Target verticals with disproportionate regulatory exposure: Focus commercial efforts on industries facing recent exposure standard changes—these buyers have elevated demand and willingness to pay for turnkey solutions.
-
Standardize clinical outcomes measurement: Implement outcome and return‑to‑work metrics to move from transactional billing to value‑based contracts with large employers and payers.
Risk factors and mitigation
-
Regulatory uncertainty: While tightening standards create opportunity, they also raise compliance costs. Build flexible program designs and scenario plans that can absorb new monitoring demands.
-
Reimbursement shifts: Coding clarifications can reprice key services. Maintain active payer engagement and invest in documentation quality to protect margins.
-
Workforce constraints: Clinical staffing remains a bottleneck. Invest in clinician productivity tools and apprenticeship/partnership programs with academic centers to secure pipeline access.
How investors and corporate buyers should use this preview
Consider this article a strategic trailer: it synthesizes the forces, players, and decision levers that will matter in 2026—but it intentionally stops short of publishing the proprietary segmentation matrices, regional and service‑line shares, or company revenue splits that underpin transaction models. PW Consulting’s full study delivers those granular datasets, plus valuation multiples, M&A target scores, and downloadable financial models that allow you to test specific acquisition, greenfield, or partnership scenarios.
For market participants preparing 2026 budgets and strategic plans, the central takeaway is straightforward: occupational medicine is evolving from a compliance expense to a managed, measurable service line that can generate clinical, operational, and financial value if delivered at scale and with robust digital, regulatory, and outcome capabilities. The winners will be those that combine clinical credibility with platform economics and regulatory fluency.
Next steps
-
Download the full PW Consulting Occupational Medicine Market study to access the complete market model, segmentation breakdowns, competitor benchmarks, and implementation toolkits.
-
Engage our advisory team for a tailored 90‑day readiness assessment—covering market entry strategy, M&A diligence support, or provider network optimization aligned to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Occupational Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com