

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Consumer Computer Security Market Poised for 5.4% CAGR to 2032

Computer Security for the Consumer Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Chief Industry Analyst and Senior Strategy Consultant, I present a focused preview of our new market research — Computer Security for the Consumer Market — designed to shape executive decisions in 2026. This short brief highlights the research’s strategic value, synthesizes the macro dynamics that will determine winners and laggards, and outlines the practical actions executives should be considering now. Think of this as the trailer: it demonstrates the analytical depth and foresight embedded in the full study while preserving the granular segment tables, proprietary revenue models and scenario matrices that you’ll find in the complete report.
Computer Security For Consumer Market
Why this study matters for 2026
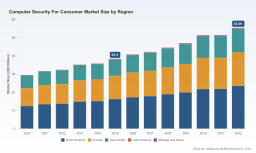
Consumer security is no longer a niche segment; it is a foundational layer of the consumer digital experience. Our baseline macro view shows a resilient and growing global market that has expanded through 2020–2025 and is projected to grow through 2032 at a mid-single-digit compound annual growth rate (CAGR). This trajectory reflects persistent consumer demand for malware protection, backup and recovery, identity protection, and new defensive capabilities tailored to the rise of connected devices and hybrid consumer work patterns.
Computer Security For Consumer Market
For corporate strategy teams — product leaders, corporate development, sales and channel executives, and regulatory compliance officers — the practical implications are immediate: product roadmaps, go-to-market plays, and M&A pipelines must be retooled to account for a market in which compliance, platform integration, and differentiated value propositions (beyond basic signature-based AV) will determine market share shifts.
Computer Security For Consumer Market
Headline macro indicators (what the full report quantifies)
- Historic expansion through 2020–2025 and a projected continuation of growth through 2032 at a CAGR of 5.4%.
- An aggregate market that has material scale at the total-market level and meaningful year-on-year expansion as consumer spending on security and related services matures.
- Concentration dynamics that indicate an established leadership tier, with the top competitors controlling a significant portion of the market — a structural fact that shapes pricing power, channel dynamics, and M&A rationale.
We deliberately withhold detailed breakdowns of regional, application or product subsegment revenues in this preview — those slices and the underlying unit economics are in the full report, where our proprietary models quantify addressable serviceable markets for each go-to-market strategy.
Regulatory and standards inflection points
- Regulatory timelines are now a central strategic variable. The Cyber Resilience Act has transitioned from policy to operative steps, with staged obligations that will materially affect product design, documentation and reporting requirements for consumer-facing software and hardware with digital elements. Several of the Act’s milestones are already in force or approaching application dates, which makes compliance readiness a 2026 board-level priority.
- Standards and guidance are converging around baseline requirements for consumer IoT and embedded software. U.S. standards bodies have published practical baselines to help manufacturers and vendors align engineering practices to attested security expectations, reducing ambiguity for product teams but raising the bar for legacy products.
- These twin forces — regulatory mandates and standards maturation — compress product development cycles, increase the cost of non-compliance, and create new product-adjacent services (e.g., compliance-as-a-service, certification, post-market monitoring) that incumbents and challengers can monetize.
Competitive landscape: what to watch
The competitive set is dominated by a mixture of established consumer security brands and software incumbents that have extended into adjacent services. Notable players covered in our study include long-tenured antivirus and consumer protection brands, modernized vendors bundling backup and recovery with cybersecurity, and several firms that are intent on converting legacy installed bases into subscription services.
- Acronis — repositioning as a combined backup and consumer cybersecurity provider with proactive patch management and identity protection embedded into its flagship consumer suite. Their 2026 product release signals a clear strategy: converge data protection and threat prevention to raise switching costs and extend lifetime customer value.
- Bitdefender — a product-centric competitor with continuous investment in detection efficacy and lightweight footprints for consumer devices. Their strengths continue to be technical depth and brand reputation, especially among privacy-conscious segments.
- Gen Digital portfolio (Norton, McAfee, Avast, AVG) — a multi-brand owner that optimizes channel and global coverage by leveraging distinct brand equities. Their strategy centers on subscription bundles, cross-sell across brands, and ecosystem partnerships with device OEMs and ISPs.
Our analysis maps each competitor across product architecture, monetization approach (transactional vs. subscription vs. platform), channel dependency, technology roadmap and regulatory readiness. The full report contains comparative scorecards and a decision matrix to help executives prioritize defensive investments and identify acquisition targets that offer the fastest path to differentiated capabilities.
Key market dynamics that will shape outcomes in 2026
- Integration of services: Bundling backup, patch management, identity protection and endpoint security will become table stakes for companies seeking growth beyond pure detection. Vendors who can credibly deliver integrated value without creating usability friction will capture higher retention.
- Regulation as a demand driver: Compliance obligations will not only raise costs; they will create demand for certified, documented solutions. Expect new product tiers and managed services to be designed specifically to meet regulatory auditability and reporting requirements.
- Channel shifts: OEM preloads, ISP bundles, and retail partnerships will remain important, but platforms that simplify enrollment, licensing and cross-device management (including mobile and household IoT) will be decisive in consumer acquisition and retention economics.
- Consolidation pressure: Given the established concentration among leading incumbents, expect opportunistic M&A where platform gaps exist — particularly for capabilities around backup integration, identity management, and post-market monitoring.
What the report contains (practical, actionable deliverables)
- Market-sizing and trend analysis with year-by-year modeling from 2020 through 2032 at the total-market level and across product archetypes.
- Scenario-based revenue forecasts and sensitivity tests that help quantify the impact of regulatory timelines, accelerated adoption in specific consumer cohorts, and alternative pricing models.
- Competitor benchmarking: feature and capability scorecards, go-to-market stress-tests, and a curated list of strategic targets for acquisition or partnership, prioritized by integration complexity and near-term revenue synergies.
- Regulatory playbook: a compliance-risk matrix that maps major regulatory milestones to product and operational changes required by 2026 and beyond, including a checklist for product teams and a vendor validation framework for procurement.
- Commercial strategies: recommended pricing experiments, OEM/ISP channel negotiation tactics, retention levers tied to integrated services, and a sales-play library for enterprise-facing teams seeking to upsell consumer security as a differentiator for B2B2C channels.
The full report intentionally contains the detailed tables, segmented revenue figures, unit economics and named-supplier scorecards that senior leaders use to justify investment and M&A decisions. This preview purposefully omits those granular line items to protect our modeling IP and to preserve the strategic leverage clients gain from the full deliverable.
Strategic imperatives for 2026 — recommended executive actions
- Embed regulatory readiness into product roadmaps now. Map engineering sprints to regulatory milestones, and budget for documentation, vulnerability disclosure processes and post-market surveillance tools.
- Prioritize integration plays that bundle data protection with proactive cybersecurity. Monetization studies in our report show that convergence increases average revenue per user and reduces churn for mature brands.
- Accelerate channel diversification. Negotiate OEM and ISP pilots that move beyond single-device antivirus toward household-level subscriptions and multi-device management platforms.
- Scan M&A targets for three capabilities: backup/restore at scale, identity protection primitives, and lightweight telemetry that enables effective post-market monitoring compliant with regulatory reporting.
- Invest in trust and privacy signals. A clear consumer privacy and transparency posture — backed by independent attestations — will be a competitive differentiator as regulation raises consumer expectations.
Illustrative scenarios we model in the full study
- Conservative scenario: steady subscription growth with compliance costs absorbing margin pressure but offset by higher renewal rates stemming from integrated services.
- Accelerated adoption scenario: regulatory enforcement and a series of high-impact consumer incidents drive faster subscription conversion and premium feature uptake.
- Disruption scenario: a new entrant or OEM-native security stack captures household-level distribution, forcing incumbents to pivot to white-label or managed services.
Each scenario is backed by transparent assumptions and sensitivity tables in the full report to help quantify risk-adjusted outcomes for investment committees.
Final note — why PW Consulting’s study is practical for 2026
This research is engineered for impact: it moves beyond descriptive analysis toward prescriptive, executable strategy. Whether you are refining a product roadmap, sizing an acquisition, negotiating channel partnerships, or preparing boards for regulatory risk, the study supplies the forecast models, competitor playbooks and compliance checklists required to make confident decisions in 2026.
To access the detailed segment models, competitor scorecards, and downloadable scenario workbooks, consult the full report. The trailer you’ve just read surfaces the strategic logic and urgency — the complete report supplies the tables, numbers and executable plans your leadership team will need to act.
Next steps
- Contact PW Consulting to schedule a strategy briefing that aligns the report’s insights to your portfolio and operating plan.
- Commission a tailored model if you need a customized market view (e.g., by channel, country grouping, or product bundle).
- Begin a compliance readiness audit mapped to the regulatory milestones detailed in the full study; early audits materially reduce remediation costs and time-to-compliance.
For detailed analysis of this topic, please visit the official page: Computer Security For Consumer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com