

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dual-Fuel Engine Market to Hit USD 4.62 Billion by 2032 at 10.2% CAGR

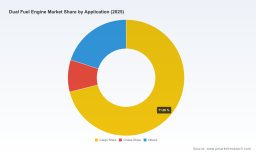
Dual Fuel Engine Market: Strategic Outlook for 2026 Decision-Making
Executive preview
As organizations recalibrate fleet strategies, power-generation assets, and supply-chain exposure to carbon pricing, dual fuel engines have moved from niche decarbonization play to core technology option for maritime and stationary power applications. Our PW Consulting market study—rooted in a 2025 base year and covering the 2020–2025 historical window with forecasts to 2032—shows a market expanding at a compound annual growth rate of 10.2%. The global market value rose from roughly USD 1.45 Billion in 2020 to about USD 2.35 Billion in 2025, and under our central forecast reaches approximately USD 4.62 Billion by 2032.
Dual Fuel Engine Market
This introduction frames why the study matters for strategic choices you will make in 2026: procurement cadence, retrofit vs newbuild decisions, OEM partnerships, financing structures, and regulatory compliance pathways. Below we summarize the strategic takeaways and the practical, action-oriented content contained in the full report—while reserving detailed segment-level allocations and sensitive modeling outputs for the full report download.
Dual Fuel Engine Market
Market snapshot: what the macros tell us
The headline picture is clear: strong mid-teens growth per market vintage is giving way to a sustained double-digit expansion driven by three structural forces—fuel diversification needs in maritime transport, decarbonisation mandates and carbon-cost risk management, and technology maturation that broadens fuel compatibility (LNG, methanol, ammonia, hydrogen blends and pilot-ignition modes). The market’s trajectory from USD ~1.45B in 2020 to USD ~2.35B in 2025, and our projection to almost USD 4.62B in 2032, underpins an investment case where scale and first-mover learning advantages compound rapidly.
Dual Fuel Engine Market
Supplier concentration is material: the top-tier manufacturers capture the majority share of OEM revenues, creating a market with few large incumbents and high barriers for pure-play newcomers. This concentration creates both risks (supply bottlenecks, limited bargaining leverage) and opportunities (OEM collaboration, aftermarket services, spare-part ecosystems) depending on your strategic posture.
Why this matters for 2026 corporate strategy
- Procurement timing: Lead times for certified dual-fuel systems and retrofit kits are lengthening as demand accelerates and OEMs allocate capacity. Companies confirming orders or retrofit frameworks in 2026 secure advantaged delivery windows and price certainty.
- CapEx vs OpEx trade-offs: Comparative economics between retrofitting existing engines and new dual-fuel builds shift materially with fuel price spreads, carbon pricing exposure, and financing rates. Our report supplies scenario-tested models that let you stress-test these trade-offs under multiple fuel and carbon trajectories.
- Regulatory hedging: Emerging certification pathways—such as ClassNK approvals for hydrogen pilot-ignition engines—and regional emissions regimes (including Tier 4-style rules) change the required engineering and operational parameters for compliance. Anticipatory investment in demonstrator projects can unlock subsidy streams and early adopter advantages.
- Service & Aftermarket economics: With a concentrated OEM base and complex fuel systems, long-term revenue pools shift to maintenance contracts, fuel-flexibility upgrades, and systems integration. Securing service partnerships in 2026 will be as strategic as hardware procurement.
What the PW Consulting report delivers (practical modules)
The full study combines market sizing and forecasting with pragmatic, executable tools designed for dealmakers, technical leads, and strategy teams. Key deliverables include:
- Time-series market model (2020–2032) with baseline, upside, and downside scenarios and sensitivity to fuel pricing and carbon cost inputs.
- Regulatory matrix mapping certification requirements, emissions thresholds, and subsidy programs across major jurisdictions—designed for compliance planning and grant capture.
- Capital and operating cost templates for newbuild vs retrofit decisions, including standardized CapEx schedules, fuel-mix O&M drivers, and payback calculators.
- Competitive landscaping and supplier benchmarking with capability matrices (product portfolios, fuel compatibility, service networks, and R&D pipelines).
- Deal flow and M&A heatmaps identifying strategic targets, partnership archetypes, and valuation comparators for 2026 transactions.
- Ten granular case studies—covering cargo shipping retrofits, powership deployments, coastal vessel pilot projects, and merchant fleet newbuilds—each with build-to-operate financials and risk checklists.
- An interactive decision-support playbook that translates market outputs into prioritized action lists tailored to OEMs, shipowners, utilities, and investors.
Competitive landscape: who matters and why
The market is anchored by established engine builders and a few specialized two-stroke manufacturers. Leading OEMs included in our analysis bring distinct strategic positions:
- Caterpillar Inc. – strong in power-generation and marine segments with demonstrator programs for methanol-capable marine engines and proven dual-fuel lineups for stationary power.
- Cummins Inc. – leverages broad aftermarket reach and Tier 4-capable products that target oil & gas and industrial power customers, focusing on fuel savings and lifecycle support.
- Wärtsilä Corporation – balanced marine and energy portfolio with mature DF platforms that are field-proven on LNG and liquid fuels and a sizable EPC/integration capability.
- WinGD – specialist in two-stroke marine engines with multi-fuel X-DF platforms designed for lower-carbon fuels including ammonia, methanol and ethanol, and a clear focus on retrofits and large commercial vessels.
- MAN Energy Solutions / Everllence – traditional strengths in both propulsion and power-generation with recent deliveries to powership operators and an emphasis on modular fuel flexibility.
- Yanmar Holdings – innovating on pilot-ignition hydrogen solutions and advancing certification pathways for coastal and small-vessel markets.
Recent events in 2025–2026 underscore that momentum: MAN delivered multiple large DF engines for powership operations in early 2025; Yanmar secured ClassNK approvals for hydrogen pilot-ignition 4-stroke engines (certification granted December 2025); and Caterpillar announced a field demonstrator for methanol-capable marine engines planned for deployment in 2026. These developments illustrate how certification, demonstrator projects, and large project deliveries are reshaping competitive advantage.
Technology and regulatory dynamics shaping near-term decisions
Several technology and policy signals should be central to any 2026 strategy:
- Certification constraints and operational design: EPA Tier 4 Final guidance continues to influence engine configurations—requirements such as minimum pilot diesel fractions for stable compression ignition impose engineering trade-offs that affect fuel cost savings and emissions outcomes.
- Fuel diversification path-dependency: The industry is not converging on a single substitute fuel. LNG, methanol, ammonia, and hydrogen each present different supply-chain, handling, and certification implications—creating optionality value for engines that can tolerate multiple fuels or be upgraded with limited downtime.
- Carbon pricing and retrofits: Emerging carbon taxes and emissions trading schemes materially change the operating-cost calculus and have already driven contractual interest in LNG-capable retrofits and fuel-switching frame agreements in 2025.
- Subsidies and demonstration funding: Public funding programs—such as projects supported by foundations or national low-carbon initiatives—are accelerating technology validation and reducing first-mover risk for shipowners and coastal operators.
How to use this research in 2026: recommended actions
- Short-term (0–12 months): Initiate capacity reservation conversations with targeted OEMs, secure retrofit framework agreements, and run the report’s CapEx/Opex templates against your asset list to prioritize candidates for 2026 upgrades.
- Medium-term (12–36 months): Deploy demonstrator projects where possible to capture learning credits, negotiate long-term service and fuel-supply contracts, and embed fuel-flexibility clauses into newbuild specifications.
- Investor/board level: Integrate scenario outputs into capital allocation processes—test leverage, IRR, and covenant impacts under high-carbon-price scenarios and prepare investor communications on transition resilience.
- Policy engagement: Use the regulatory matrix to identify early opportunities for grant capture and to inform trade association advocacy on certification harmonization to reduce cross-jurisdictional compliance costs.
What we withhold here and why
This article intentionally previews the analytical depth and practical utility of the full PW Consulting study while withholding detailed segment-level allocations, the full downloadable datasets, and proprietary model outputs that underpin our forecasts and deal models. Those items are core IP of the report and are available for licensed access on the source webpage—where subscribers can download interactive workbooks, vendor scorecards, and executable procurement templates.
Final thought
2026 will be a pivotal year: the combination of accelerating demand, concentrated supplier dynamics, evolving certification pathways, and the growing incidence of carbon-cost risk means decisions made in the next 12 months will determine who captures value as the dual fuel engine market scales. The PW Consulting study is designed to move you from high-level conviction to executable plans—covering what to buy, when to retrofit, how to structure service deals, and which partnerships to prioritize to de-risk transition pathways. For the full segmented datasets, scenario models, and downloadable execution tools, please consult the full report page.
For detailed analysis of this topic, please visit the official page: Dual Fuel Engine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com