

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Diatomite Market to Reach USD 2,018.5M by 2032 at 5.5% CAGR

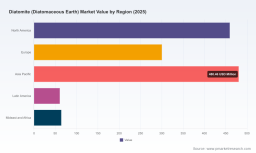
Diatomite (Diatomaceous Earth) Market — Strategic Outlook and Decision Framework for 2026
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present an executive, decision-focused primer on the global diatomite market designed specifically to inform corporate choices in 2026. This briefing synthesizes our market model, competitive mapping, regulatory and logistics realities, and tactical actions senior executives should prioritize. It intentionally demonstrates analytical depth while preserving the proprietary segment-level detail that drives commercial advantage — for full tables, model outputs and granular splits, please refer to the full report.
Diatomite (Diatomaceous Earth) Market
Snapshot: market scale and trajectory
Using 2025 as the base year, the installed market for diatomite (measured in USD, revenue basis) sits in the low billions and is forecast to expand at a mid-single-digit compound annual growth rate (CAGR) through 2032. Our modeling shows steady recovery and structural growth beginning 2026, with market expansion driven by both end‑use recovery and quality-driven substitution into higher-value applications. This growth profile highlights both an incrementally larger addressable market and rising complexity in product and channel strategies that will determine winners and laggards over the coming investment cycle.
Diatomite (Diatomaceous Earth) Market
Why this study matters to 2026 decision-makers
- Capital allocation: our demand and price scenarios quantify the payback sensitivity for capacity investments and calcination/upgrading projects.
- Procurement and sourcing: we map logistics break‑points and the maximum economic shipping radius for different material grades, enabling smarter supplier-network design.
- Commercial strategy: the report shows where premiumization and formulation-led differentiation can protect margins against commoditization.
- Regulatory & operational risk: we translate silica-related compliance dynamics into actionable capex and OPEX scenarios for production and processing facilities.
- M&A and portfolio moves: concentration metrics and company profiles expose acquisition targets and defensive moves to secure feedstocks and distribution channels.
What the PW Consulting report delivers (practical, executable content)
- Top-down market sizing and bottom-up demand modeling (2020–2025 historical, 2026–2032 forecast) with scenario stress‑tests for price, logistics, and regulatory shocks.
- Supply-side analysis including mining footprints, processing routes (natural, calcined, flux-calcined), cost curves and break-even shipping distances.
- Commercial playbooks for upstream and downstream players: pricing strategies, product portfolio optimization, channel and distributor incentives.
- Regulatory and ESG impact module: compliance cost modeling tied to crystalline silica limits, permitting timelines and depletion allowance treatment.
- Competitive benchmark and M&A scorecard: company profiles, strategic priorities, and integration risk assessments.
- Implementation tools: decision matrices, investment calculators, and a library of primary interview excerpts with industry buyers and technical leads.
Market dynamics shaping 2026 strategy
- Demand composition and premiumization: while traditional uses such as filtration remain a foundational demand driver, higher‑purity and processed grades are growing faster where formulation benefits or regulatory constraints justify price differentials. Commercial strategies must therefore differentiate not only by price but by grade, particle engineering and compliance assurances.
- Logistics is a strategic constraint: transportation economics continue to define the practical catchment for mines and production sites; long haul shipping erodes competitiveness versus substitutes. Our routing and cost model identifies which product grades can sustain premium transport and which must be locally sourced or produced.
- Regulation and health risk: crystalline silica content creates a regulatory overlay that affects product formulation, worker safety programs, and market access. Companies should assume elevated compliance cost and capital expenditure requirements in the planning horizon.
- Taxation and resource allowances: fiscal treatments such as depletion allowances materially affect after‑tax returns on mining projects and should be embedded into NPV assessments when evaluating new or replacement capacity.
- Consolidation and concentration: the sector shows moderate concentration among a small group of global players. That concentration creates price signaling and strategic levers for incumbents, but also leaves room for regional specialists and nimble niche suppliers.
Competitive landscape — profiles and strategic takeaways
- Imerys (France): a global leader with a diversified minerals portfolio and capacity to supply multiple grades for filtration, coatings and personal care. Strategic strength: integrated mineral platforms and global customer relationships that support premiumization and technology-driven differentiation.
- Dicalite Management Group (United States): a long-established domestic producer with deep mining experience. Strategic posture: strong regional position and commercial agility — evidenced by recent price actions that underline willingness to manage margins through market cycles.
- EP Minerals (United States): focused on filter aids, absorbents and functional additives across food & beverage, pools/spas, agriculture and industrial uses. Strategic implication: distribution expansion and partnership moves can rapidly change regional supply dynamics.
- U.S. Silica Holdings Inc. (United States): commercial focus on filtration and industrial abrasives under an established brand. Strategic strength lies in industrial customer breadth and scale economics in certain product streams.
- Showa Chemicals (Japan): regional specialist with manufacturing and product depth for industrial and filtration grades. Strategic value: high‑quality product focus serving demanding technical segments.
- 20 Microns Ltd. and Caltron Clays & Chemicals (India): suppliers of higher-purity and food-grade products, respectively; they represent lower‑cost regional platforms and verticalized product strategies for formulation-sensitive markets.
- Matex YG (Shanghai): producer-distributor model focused on industrial and quality grades for regional markets; strategic advantage is fast-to-market distribution coupled with localized technical service.
Recent commercial moves reinforce shifting margins and footprint strategies: for example, late‑2025 price actions from a large US domestic miner and territory expansion by an established filter‑aid supplier show how short-term supply-side recalibration can alter regional competitiveness. Our models quantify the margin and volume impact of these types of tactical changes.
Diatomite (Diatomaceous Earth) Market
Regulatory and structural headwinds
- Health and safety: crystalline silica exposure is a material liability; compliance and monitoring costs are now a standard line item in new plant economics.
- Fiscal/tax environment: resource allowances and depletion treatments materially influence after-tax returns and should be included in capital planning.
- Trade and classification: customs classification and codes remain important operational controls for cross-border sourcing, affecting duty, documentation and lead times.
- Transportation constraints: distance-to-market economics will continue to dictate which grades can be profitably traded and which require local production or regional partnerships.
Action agenda for corporate leaders in 2026
- Immediate (0–12 months): conduct a supplier risk audit, renegotiate contracts to incorporate indexation and force‑majeure hygiene, and initiate silica compliance audits across production and handling.
- Near-term (12–24 months): implement a multi-scenario procurement strategy (local + regional + spot), invest selectively in calcination or beneficiation capability where margin uplift is validated, and pilot logistics hubs where transport economics permit.
- Medium-term (24–36 months): pursue targeted bolt-on M&A to secure feedstock or technical capability in prioritized corridors; develop premium product lines with documented safety and performance credentials to reduce commoditization risk.
- Governance & risk: embed ESG and health metrics into commercial scorecards and require any proposed capacity build to pass an integrated regulatory, logistics and market-price stress test.
Why PW Consulting’s intelligence is the right input for 2026
Our diatomite study combines a fully documented top‑down market model with a bottom‑up supply mapping, primary interviews across the value chain, and a scenario engine that stress‑tests price, logistics and regulatory paths. The output is a set of executable recommendations and financial templates that corporate teams can translate directly into board-level investment decisions.
As a final note: while this overview presents the strategic frame and the macro market trajectory, it omits the discrete regional and application split tables and the full company-level share matrices — those are preserved in the full report to protect the commercial value of granular segmentation. For access to detailed segment tables, interactive models, and the full M&A scorecard, contact PW Consulting or visit the report page for licensing and single‑user access.
Key market concentration metric
To orient strategic thinking: the market exhibits moderate concentration, with the top three suppliers commanding a significant share of global revenues and the top five increasing that concentration further. This structure creates both strategic leverage for incumbents and acquisition opportunities for companies seeking to rapidly scale presence in targeted corridors.
For detailed analysis of this topic, please visit the official page: Diatomite (Diatomaceous Earth) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com