

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PVC Paste Resin Market to Reach USD 12.19 Billion by 2032 at 4.8% CAGR

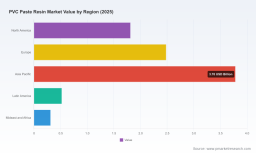
PVC Paste Resin Market — Strategic Brief for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision-focused orientation to our full PVC Paste Resin Market study. This brief surfaces the signal insights you need to calibrate 2026 strategy — while reserving the proprietary, segment-level data and model mechanics for the full report. Consider this a trailer: we reveal the market architecture, near-term pressure points, and pragmatic playbooks that will determine competitive advantage in the coming 12–36 months.
PVC Paste Resin Market
Where the market stands (quick snapshot)
The PVC paste resin market enters 2026 from a position of steady recovery and structural growth. Our base-year calibration (2025) places global market revenue at USD 8.9 Billion, following a recovery from the 2020–2023 period. Under our central scenario the market grows at a 4.8% CAGR through the 2026–2032 forecast window, arriving at roughly USD 12.2 Billion by 2032. The path to 2032 is not linear — expect episodic soft patches and surges tied to feedstock volatility, construction and automotive demand cycles, and regulatory events. Those dynamics make 2026 an inflection year for strategy: firms that act now will lock in pricing frameworks, procurement structures, and capacity options that materially affect returns across the next planning cycle.
PVC Paste Resin Market
Dynamics shaping 2026 choices
-
Raw-material shocks and pass-through mechanics: Vinyl Chloride Monomer (VCM) is the dominant cost driver. Recent data show meaningful upward movement — for example, VCM prices in China rose by around 250 RMB/ton in January 2026 and were reported at approximately FOB USD 817/MT in China and USD 904/MT in the United States by April 2026. These shifts have translated rapidly into seller-led price adjustments in regional markets; several producers implemented steep hikes in Q1–Q2 2026. The linkage between VCM, calcium carbide and paste-resin pricing is tighter than many buyers appreciate — creating a persistent risk of margin squeeze if commercial contracts lack robust indexation.
PVC Paste Resin Market -
Price signaling from producers: In March 2026, a major Indian paste-resin producer executed multiple price increases (several increments across the month, with hikes running into the thousands of local currency per tonne). These actions are not isolated — they signal a willingness among regional champions to transmit upstream cost moves quickly, and to defend margins through market pricing rather than volume tolerance.
-
Structural supply posture: The market remains fragmented. A small group of global and regional players compete alongside specialty and integrated producers. That fragmentation produces frequent regional imbalances and spot windows that sophisticated traders and exporters can exploit, but it also raises the bar for scale-driven investment economics.
-
Regulatory and contractual resets: Industry players are actively reshaping manufacturing arrangements and commercial commitments. Notable examples in the past 18 months include the termination/reshaping of production consignment agreements as firms rearrange in-house capabilities and control points. For executives, this means contract renegotiation windows and partnership agreements are fertile ground for rebalancing risk.
-
Demand composition and product mix: Growth is supported by end markets such as construction, automotive and select industrial applications. Yet the value accrues unevenly across paste grades and processing routes. Customers seeking glove-grade, medical, or high-performance paste resins are willing to pay a spread for specification reliability — an opportunity for premiumization.
Competitive landscape — who matters and why
The competitive set blends Europe’s specialty champions, large Asian integrated producers, and regional leaders with focused capacity. Key players include:
-
Kem One (Levallois-Perret, France) — unique European capability across Mass & Suspension routes; competes on technical service and specialty dispersion grades for coatings, adhesives and sealants.
-
Westlake Vinnolit (Ismaning, Germany) — niche leadership in Vinnolit paste grades used in floor coverings, leatherette and specialty coatings; strong technical relationships in European end-markets.
-
Chemplast Sanmar (Chennai, India) — the country’s largest specialty paste producer with large domestic capacity; an early mover on 2026 price adjustments that demonstrates local market pricing power and downstream influence.
-
SCG Chemicals (Bangkok, Thailand) , CIRES (Estarreja, Portugal) , Formosa Plastics , LG Chem , Tosoh , Kaneka and Hanwha Solutions — represent a mix of integrated and specialty strategies, each with distinct distribution networks and product depth.
Strategically, players differentiate on three axes: feedstock integration, specialty-grade know-how, and route-to-market execution. That creates a set of repeatable plays for incumbents and newcomers alike — from capacity co-location to tolling agreements, from specification-driven premiumization to market arbitrage via exports.
What the PW Consulting report delivers (practical, actionable outputs)
-
Robust market sizing and a flexible forecast model (2020–2032) with scenario toggles for demand shock, feedstock stress, and policy interventions.
-
Price-formation engine that models paste-resin spot and contract pricing as a function of VCM, calcium carbide, energy, freight and regional spreads (buyer and seller pass-through sensitivities included).
-
Granular supplier heatmaps, capacity utilisation analytics, and integrated plant-by-plant profiles to support site-level investment decisions and tolling debates.
-
Competitor dossiers and a prioritized M&A/partnership target list informed by strategic fit, technology gaps, and balance-sheet thresholds.
-
Commercial playbooks: indexation clause templates, short-term spot procurement rubric, and channel-specific pricing tactics for construction, automotive and medical segments.
-
Operational stress-tests and a 12-month operational playbook that highlights tactical moves to protect margin during supply shocks — including inventory buffers, hedging thresholds and tolling activation triggers.
-
Investor-ready slides and an executive one-page dashboard with the top 10 early-warning indicators to watch in 2026.
How to use these insights in 2026 decisions — recommended priority actions
-
Pricing & commercial: Immediately audit customer contracts for indexation language. Where indexation is weak, implement phased repricing windows and blended hedges to limit margin erosion during VCM spikes.
-
Procurement & feedstock: Establish dynamic hedging playbooks for VCM and calcium carbide exposure. Evaluate partial vertical integration or long-term offtake agreements only where IRR tests show resilience at stress-case VCM levels.
-
Capacity strategy: Favor flexible brownfield debottlenecking and tolling partnerships over large greenfield commitments in the near term; preserve optionality until feedstock-price regimes stabilize.
-
Product strategy: Accelerate development and go-to-market for higher-margin paste grades and regulated segments (medical/glove-grade), where specification switching costs and safety/regulatory compliance create defensibility.
-
M&A & partnerships: Use the current environment to secure capacity-light partnerships and technology licences. Prioritize targets that close specification gaps or add market access rather than pure-volume plays.
-
Risk monitoring: Track a short list of KPIs weekly — VCM spot and contract spreads, regional freight spreads, domestic inventory days, plant utilisation and tender re-pricing windows. Define trigger thresholds for contingency actions.
Why this report is strategically valuable now
2026 is a critical decision point because raw-material volatility and producer pricing behavior have raised the cost of delay. The market’s medium-term fundamentals remain constructive — driven by end-market recovery and product premiumization — but execution matters. Firms that recalibrate commercial contracts, secure strategic feedstock positions, and selectively invest in high-return capacity or capability will materially outpace peers in margin and revenue growth through 2032.
Our report bundles not only market forecasts and competitor intelligence, but also the tactical instruments — templates, models, and playbooks — that practitioners need to act within the current, fast-moving environment.
Next step
To access the granular segmentation, regional and application-level demand tables, and the full financial model (including stress-case assumptions and supplier scorecards), request the full PW Consulting PVC Paste Resin Market report. The core segmentation figures, model inputs and the per-company performance dashboards are reserved for report subscribers — designed to convert market insight into decisive action.
PW Consulting remains available to brief your executive team on the scenarios most relevant to your portfolio and to co-design the 12–24 month playbook that aligns with your risk appetite.
For detailed analysis of this topic, please visit the official page: PVC Paste Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com