

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Human Vaccine Market Poised for 6.8% CAGR Through 2032

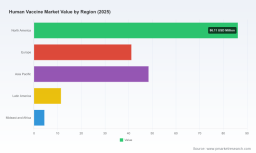
Human Vaccine Market 2026: Strategic Imperatives from PW Consulting
As public health priorities, platform technologies, and payer environments realign, vaccine strategy has moved from episodic crisis response to long-term commercial planning. PW Consulting’s latest Human Vaccine Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) provides the decision-grade intelligence executives need to make confident choices in 2026. The market is on a steady upward trajectory — our modelling shows a mid-single-digit compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast — and total market value is projected to expand meaningfully through 2032. At the same time, concentration metrics indicate a market dominated by a small cohort of incumbents (top three and top five firms command the majority of value), creating both barriers and targeted opportunity windows for challengers.
Human Vaccine Market
Why this research matters for 2026 decisions
-
Operational readiness: Manufacturers and suppliers must convert strategic intent into supply-chain, manufacturing, and regulatory plans that are executable under tighter timelines and higher scrutiny.
Human Vaccine Market -
Portfolio prioritization: With platform technologies (e.g., mRNA, protein subunits, viral vectors) maturing in parallel, commercial bets should be sized not only by clinical potential but by manufacturing and reimbursement feasibility through 2028–2032.
Human Vaccine Market -
Go-to-market timing: Seasonal strain selection and regulatory cycles (now more predictable for some respiratory vaccines) create calendar-driven windows for launches and label updates.
-
M&A and partnership targeting: The market’s moderate-to-high concentration amplifies the value of bolt-on capabilities that shore up fill-finish capacity, regional access, or novel antigen platforms.
Macro trajectory and strategic implications
Our top-line modelling anchors around the 2025 market baseline and projects through 2032. That trajectory — underpinned by a 6.8% CAGR — reflects a combination of continued demand for respiratory vaccines (including COVID-19 and RSV), routine immunization programs, lifecycle updates of established vaccines, and incremental uptake in adult and special-population immunization. For leadership teams this means planning assumptions should blend steady organic growth with episodic spikes tied to strain updates, emergency authorisations, or targeted booster campaigns.
Two structural considerations should guide 2026 planning. First, platform diversification matters: firms with multi-platform arsenals and flexible manufacturing can capture asymmetric upside while hedging platform-specific regulatory and safety risk. Second, concentration levels imply that while incumbents will continue to capture a disproportionate share of revenue, there are exploitable niches—especially in age-targeted vaccines, new antigen designs, and specialized regional supply agreements—where focused entrants can achieve outsized commercial returns.
Dynamics shaping near-term risk and opportunity
-
Supply chain and raw materials: The industry’s experience during the pandemic is a clear warning. WHO and industry analyses report that scale-up delays and raw material shortages remain salient risk vectors. In practice, this translates to premium on-time-to-market metrics for firms that secure multi-year supplier contracts, maintain second-source agreements, and invest in inventory buffers for critical reagents and vials.
-
Regulatory posture and safety surveillance: Regulators are augmenting post-authorization requirements for novel platforms. For example, mandatory long-term cardiac safety studies for mRNA COVID-19 vaccines underscore a broader trend: approvals increasingly come with lifecycle obligations that impact development timelines and post-market economics. Firms should incorporate the cost and time of extended surveillance into launch ROI models.
-
Reimbursement and access dynamics: Policy changes are altering payer landscapes. New rules eliminating cost-sharing for certain federally recommended vaccines in some jurisdictions exemplify how subnational policy can accelerate uptake and shift commercial models. Companies need granular payer playbooks that adapt to both national immunization program tenders and evolving local reimbursement rules.
-
Seasonal strain selection and label updates: Recent regulatory recommendations for updated COVID-19 formulas and subsequent approvals for new formulations highlight the cadence of product refreshes. This creates commercial rhythms—planning for manufacturing slots, regulatory submissions, and communications campaigns around these cycles will be a competitive differentiator.
Competitive landscape — reading the field in 2026
The market’s leading firms combine platform depth, legacy vaccine portfolios, and distribution scale. Key players include major vaccine innovators and specialist biotechs that have transitioned pandemic-era advances into endemic-era products. Their strategic postures can be summarized as follows:
-
Large integrated innovators: Firms with broad portfolios and global reach continue to trade on scale, breadth, and long-term relationships with payers and immunization programs. Their advantages are manufacturing footprint, established regulatory channels, and diversified revenue streams across pediatric and adult immunizations.
-
mRNA-first challengers: Organizations that built mRNA capabilities during the pandemic are now translating platform agility into seasonal and specialty vaccines. Regulatory demands for extended safety surveillance are an important consideration for these players’ risk profiles.
-
Protein subunit and traditional vaccine specialists: Protein subunit entrants and established subunit vaccine producers remain important, particularly for populations where reactogenicity profiles and storage logistics favor non-mRNA approaches.
-
Niche and biodefense suppliers: Companies focused on smallpox/mpox and other specialized vaccines occupy defensible positions that are often less price-sensitive and more reliant on strategic government contracts.
Collectively, the top three and five firms control a material share of the market, which implies that mid-size players should prioritize asymmetric plays—capability-based partnerships, regional strongholds, and white-space indications—rather than broad global rollouts that invite direct competition with incumbents.
Recent signals that matter for 2026
-
Regulatory recommendations and approvals for updated COVID-19 vaccine formulas are establishing a seasonal cadence and clarifying evidentiary expectations for strain-adapted vaccines.
-
Selective approvals of protein subunit boosters for older adults and high-risk groups demonstrate a viable commercial path for non-mRNA vaccine technologies in defined population segments.
-
Heightened regulatory monitoring of supply chains and post-market safety obligations is increasing the non-clinical costs of vaccine programs; expect longer, more expensive lifecycles for novel products.
What’s included in the full PW Consulting report (practical assets)
Our full study is deliberately operational, designed for teams that must move from insight to action in 2026. Deliverables include:
-
Granular market-sizing models (historical series and forecast), with scenario toggles for demand shocks, strain-driven booster cycles, and differential uptake curves by population cohort.
-
Competitive intelligence dossiers: product-by-product win/loss analyses, launch readiness checklists, and regulatory filing timelines for named competitors.
-
Manufacturing and supply-chain heatmaps: supplier concentration indices, critical-material single points of failure, and recommended sourcing playbooks.
-
Regulatory and safety playbook: evidence-generation templates that align trial design, post-authorization commitments, and labeling strategies.
-
Commercial playbooks: segmented payer models, pricing elasticity simulations, tender-entry frameworks, and launch-sequencing optimizers.
-
M&A and partnership shortlist: capability gaps surfaced by the analysis mapped to potential targets and strategic rationale.
Note: in line with the “trailer” approach, the public executive summary highlights directional insights and strategic frameworks. Detailed segment-level tables, country dashboards, and company-specific revenue splits are available exclusively in the full report and downloadable data pack.
Five immediate strategic moves for 2026
-
Lock in critical inputs: Negotiate multi-year agreements and establish dual-sourcing for reagents, vials, and adjuvants. Supply confidence will unlock commercial flexibility.
-
Prioritize platform resilience over platform hype: Evaluate portfolio allocation not only by clinical efficacy but by manufacturing scalability and regulatory burden over a multi-year horizon.
-
Invest in flexible manufacturing: Modular, fill-finish, and contract manufacturing capacity provide optionality for strain updates and new product launches.
-
Align payer strategies with local policy trends: Incorporate emerging reimbursement rules into pricing models and prepare segmented access plans for jurisdictions with no cost-sharing and strong public procurement.
-
Use M&A to close capability gaps: Targeted acquisitions of niche protein subunit capabilities, regional manufacturing, or specialized cold-chain logistics can be faster and less risky than greenfield builds.
Conclusion — positioning for sustained growth
2026 will be a year of consolidation of lessons learned: platform technologies will mature alongside more rigorous regulatory expectations, supply chains will remain a differentiator, and payer dynamics will increasingly determine realized value. PW Consulting’s Human Vaccine Market study converts these macro forces into executable options — from manufacturing playbooks to M&A roadmaps — so that leadership teams can make defensible, high-conviction choices in 2026.
If your team needs decision-ready models, competitor dossiers, or a bespoke briefing to align your 2026 strategic plan with the market trajectory, our full report and data pack provide the granular segmentation and company benchmarks required to act. This executive preview demonstrates our analytic depth while intentionally reserving the detailed segment and country-level figures for the full deliverable—where the operational work to win in this market gets done.
For detailed analysis of this topic, please visit the official page: Human Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com