

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Amino Acid Analyzers Market to grow at 5.52% CAGR (2026-2032)

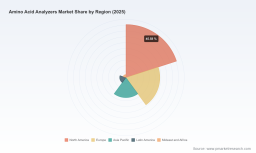
Amino Acid Analyzers Market — Strategic Imperatives for 2026
As organizations prepare capital allocations, product roadmaps, and M&A pipelines for 2026, a focused and defensible understanding of the amino acid analyzers market is no longer optional — it is a strategic prerequisite. PW Consulting’s latest industry study (base year 2025; historical 2020–2025; forecast 2026–2032) provides the high-confidence, decision-grade perspective executives need to translate macro momentum into executable plans. The big picture is straightforward: the market demonstrates steady recovery and expansion following recent volatility, with a compound annual growth rate (CAGR) of 5.52% driving recovery from a mid‑2020s base to a materially larger market by the early 2030s. Our public summary here emphasizes the capital and strategic implications while intentionally reserving the granular segment-level detail for the full report.
Amino Acid Analyzers Market
Why this market matters for 2026 planning
-
Capital planning and procurement: Amino acid analyzers are a capital‑intensive instrument class used across pharma, food testing, clinical diagnostics and feed laboratories. With forecasted market expansion in 2026 and beyond, buyers will face a sharply bifurcated landscape of high‑automation platforms versus lower‑cost manual systems. Organizations that align procurement cadence to the forecast window will avoid overinvestment in legacy configurations and capture better total cost of ownership (TCO) through timing and vendor leverage.
Amino Acid Analyzers Market -
R&D and product roadmap prioritization: Instrument vendors and component suppliers must decide where to focus incremental R&D budgets — improving throughput and automation, enhancing compatibility with existing LIMS and legacy sample workflows, or developing lower-cost options for emerging-market customers. The report’s scenario analysis quantifies how each strategic choice reverberates across revenues and installed‑base economics under different adoption curves.
Amino Acid Analyzers Market -
M&A and partnership screening: The market is moderately concentrated among a few leaders, but there remains whitespace for specialized players with niche chemistry expertise or service models. The study’s vendor scorecards and deal‑screening framework identify targets that offer near-term synergies versus those requiring longer integration horizons.
-
Regulatory and quality assurance alignment: Evolving food safety standards and the ongoing emphasis on biomarker validation in clinical research increase demand for traceable, validated assays. For 2026, companies should prioritize analyzer platforms offering validated workflows and strong service footprints to meet regulatory timelines without costly requalification.
Market trajectory and what it implies
Between 2020 and 2025 the market demonstrated resilience: a recovery from pandemic-era disruptions to a stronger 2025 base. PW Consulting’s modeled market size shows a clear upward trend into 2026, supported by stable demand from pharmaceutical analysis and renewed investment in food and clinical testing infrastructure. By applying a 5.52% CAGR across the forecast window (2026–2032), the market evolves in a way that creates tangible runway for incumbents and strategic entrants alike.
For executives, the implication is twofold. First, growth is steady rather than explosive — meaning investments should emphasize sustainable advantage (service, validation, integration) over one‑off capacity expansion. Second, the predictable expansion provides a timebound opportunity to reconfigure channel strategies and accelerate upgrades of installed bases where service margins and consumable revenues are attractive.
Key trends shaping technology and demand
-
Automation and throughput optimization: Automated, HPLC‑based and fully integrated systems are driving adoption among high‑volume laboratory settings. Buyers prioritize platforms that reduce hands‑on time while offering validated methods for regulatory environments.
-
Legacy compatibility and serviceability: Many laboratories operate a mix of legacy analyzers and newer instruments. Products and aftermarket services that provide smooth migration paths — including software compatibility and validated transfer methods — win disproportionate share with constrained labs.
-
Application-driven differentiation: Pharmaceutical peptide and biologics analysis, clinical amino acid profiling, and food/feed hydrolysate testing are three application vectors that determine instrument configuration and service needs. Vendors that tailor product bundles and consumable ecosystems to these verticals capture higher lifetime value.
-
Concentration and competitive dynamics: The market exhibits moderate concentration among the top three to five vendors, reflecting established brand reputation, installed bases, and support networks. This structure favors suppliers that can combine platform reliability with rapid service response.
What PW Consulting’s full report delivers — practical, executable content
The goal of this research is to turn data into direct business action. The full report is built around modules that stakeholders will use in boardroom and procurement settings, including:
-
Market sizing and forward-looking scenarios — three rigorously modeled demand paths (base, upside, downside) with sensitivity analysis to key assumptions such as regulatory tightening, reagent pricing, and capital intensity shifts.
-
Revenue forecasting model (2026–2032) — downloadable, dynamic spreadsheets that permit “what‑if” alterations to pricing, replacement cycles, and regional rollout schedules to test acquisition and pricing strategies in real time.
-
Vendor scorecards and procurement playbooks — standardized evaluation templates mapping technology attributes (automation, throughput, validation), service footprint, consumables margin, and end-user references to help construct RFPs and shortlist suppliers.
-
Go‑to‑market playbooks — tailored recommendations for vendors entering new regions or verticals, including channel structures, service‑partner models, and consumable monetization tactics.
-
Operating model and CapEx/Opex templates — tools for lab operators to model upgrade versus replacement decisions, TCO comparisons, and depreciation schedules aligned to 2026 planning cycles.
-
Regulatory and validation checklist — stepwise guidance for assay transfer and revalidation tailored to pharmaceutical and clinical end‑users to shorten qualification timelines.
-
Case studies and buyer personas — five anonymized use cases that demonstrate how different buyer archetypes (large pharma, contract testing labs, academic hospitals, food testing houses) configure procurement and service priorities.
Competitive landscape — core players and strategic positioning
PWC’s deep competitive scan (summarized here) highlights a mix of legacy instrument specialists and systems vendors. The full report contains in‑depth profiles; below we synthesize strategic takeaways for four representative vendors.
-
Biochrom (division of Harvard Bioscience) — Cambridge, UK : Known for robust benchtop analyzers tailored to physiological fluids and food/feed hydrolysates. Strengths include an established reputation in biochemistry labs, straightforward maintenance, and a loyal installed base. Strategic imperative: leverage service contracts and consumable packages to defend margins as automated HPLC offerings encroach.
-
Hitachi High‑Tech Corporation — Tokyo, Japan : Positions high‑speed automated analyzers compatible with legacy workflows, appealing to labs seeking throughput without disruptive revalidation. Strengths include engineering depth and system reliability. Strategic imperative: accelerate software integration and local service partnerships in key markets to convert legacy-centric buyers.
-
Sykam — Germering, Germany : A specialist maker of classical cation‑exchange systems with established chemistry and detection methods. Strengths lie in niche chemistry expertise and flexible system configurations. Strategic imperative: expand consumables and service offerings to monetize installed bases and expand into adjacent application segments.
-
Agilent Technologies — Santa Clara, CA, USA : Offers a fully automated, HPLC‑centric platform targeting high‑throughput and validated workflows. Strengths include global service network, integration with broader LC ecosystems, and strong adoption in pharma. Strategic imperative: maintain channel exclusivity for higher margin service packages while simplifying procurement and deployment for mid‑tier labs.
Collectively, the vendor landscape rewards differentiated service models, validated workflows, and clear migration paths for legacy customers. The report’s vendor benchmarking quantifies these advantages and ranks suppliers on commercial and technical axes to aid sourcing decisions.
How to use this research in 2026: recommended actions by role
-
CEOs & strategy leads: Use the scenario modeling to set investment priorities and M&A screens for 2026. Pursue targets that add service capacity or consumable revenue rather than one‑off hardware sales.
-
Heads of procurement: Implement the RFP templates and vendor scorecards to shorten selection cycles and capture margin opportunities through longer service contracts.
-
R&D & product teams: Rebalance roadmaps toward automation and simplified validation toolsets; prioritize features that reduce laboratory hands‑on time and friction with LIMS.
-
Business development and partnerships: Target collaborations that accelerate regional service coverage and consumable distribution to convert installed base potential into recurring revenues.
Why PW Consulting’s approach creates value
Our methodology couples bottom‑up installed‑base analysis with top‑down market drivers, delivering a transparent forecast that leaders can interrogate and adapt to their assumptions. We anchor projections in observable procurement cycles and reagent economics, then stress‑test models with scenario analysis. Importantly, we refrain from presenting high‑confidence directional insights (e.g., where to invest in automation vs. legacy support) without the underlying segment detail — those are included in the full report’s downloadable models that clients use directly in budgeting and commercial planning.
Next steps — where to get the granular intelligence
This briefing is designed as a strategic preview: it highlights the analytic framework, commercial implications, and vendor dynamics that should shape 2026 decisions. For the complete, transaction‑grade intelligence — including the full regional and application splits, downloadable forecasting models, vendor scorecards with quantitative rankings, and procurement templates — please access the PW Consulting market dossier available on our report page. The detailed segment data and interactive models are intentionally reserved to ensure clients can act on defensible, proprietary inputs when planning for 2026 and beyond.
Contact PW Consulting to schedule a tailored briefing where we will walk your leadership through scenario customization, supplier shortlists, and our recommended playbook to capture share as this measured-growth market evolves.
For detailed analysis of this topic, please visit the official page: Amino Acid Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com