

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicon Powder Market to reach USD 12.08 Billion by 2032 at 6.4% CAGR

Silicon Powder Market — Strategic Outlook and Playbook for 2026 Decision-Making
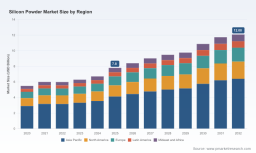
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise but substantive preview of our new Silicon Powder Market research — a pragmatic intelligence package designed to inform the critical decisions companies will make in 2026. Built on a base year of 2025 and a historical lens covering 2020–2025, our market model projects the silicon powder market forward through 2032. The market, which grew steadily from the early 2020s and reached an estimated USD 7.8 Billion in 2025, is forecast to continue expanding through the 2026–2032 horizon at a compound annual growth rate of 6.4%, reaching an estimated USD 12.08 Billion by 2032. These headline figures frame a window of strategic opportunity — but translating that opportunity into advantage requires more than aggregate numbers. This preview outlines the high-impact themes, the competitive dynamics you must monitor, and the operational playbook embedded in the full report.
Silicon Powder Market
Why this report matters for 2026 choices
Senior leaders in purchasing, manufacturing, product development, corporate strategy and M&A face converging forces in 2026: shifting end-market demand (from metallurgy to advanced electronics and solar), volatile feedstock pricing, energy and emissions constraints, and a tightening regulatory and trade environment. Our research turns market-scale projections into decision-grade inputs — scenario-calibrated supply maps, cost and energy-sensitivity models, supplier scorecards, and a regulatory risk matrix that collectively support four types of 2026 decisions: (1) where and how much to invest in capacity or purification; (2) how to structure procurement and long-term offtake contracts; (3) which partnerships or buyouts will move the needle on margin and security of supply; and (4) how to hedge or pass through price risk in an environment of tariff actions and intermittent oversupply.
Silicon Powder Market
- Timing: The 2026 planning cycle is decisive for capex and long-term contracts — our model shows when demand inflection and pricing sensitivity will most affect project returns.
- Risk calibration: From electricity-cost exposure to trade investigations and tariffs, the report quantifies downside scenarios and mitigation pathways.
- Value creation: We prioritize near-term levers (procurement, power agreements, grade conversion) that improve cashflow and strategic positioning within 12–36 months.
Key market themes and dynamic drivers
The market’s trajectory to 2032 is shaped by several interacting themes:
Silicon Powder Market
- Demand re-composition: While metallurgical uses remain a core baseline, incremental demand in higher-purity grades for electronics and solar applications is creating a structural shift in value capture. Producers that can economically supply upgraded grades have access to faster-growing, higher-margin end markets.
- Supply economics and energy intensity: Electricity costs continue to be a dominant determinant of production economics. Recent strategic moves by producers to secure long-term power contracts — exemplified by major agreements executed in 2026 — are early indicators that energy sourcing will be a competitive moat.
- Price cycles and inventory dynamics: The US market experienced downward pressure on silicon metal prices in 2025 due to oversupply and weak demand in some downstream sectors. That volatility underscores the need for flexible commercial strategies that blend spot exposure with fixed-price commitments.
- Trade and regulatory shocks: Investigations and tariff adjustments in 2025–2026 have meaningfully reshaped cross-border flows and risk profiles for buyers and sellers. Export controls, tariffs, and anti-dumping inquiries now factor into sourcing decisions as determinative inputs, not peripheral noise.
- Fragmentation vs. concentration: The market exhibits a moderate concentration structure; the top producers account for a meaningful share of global supply, yet a broad pool of regional and specialty suppliers remains active. This combination creates both competitive pressure and niche arbitrage opportunities for acquirers and off-takers.
Competitive landscape — companies to watch and strategic moves
The sector combines established global players, regional producers, and specialty suppliers. Understanding each player’s strategic posture is essential for competitive benchmarking, partnership screening, and M&A prioritization.
- Elkem ASA (Norway) — A leading producer with capacity and product-expansion programs oriented to solar-grade and high-purity applications. Recent long-term power procurement actions signal a strategy to lock-in energy cost advantages and secure feedstock competitiveness.
- Ferroglobe (UK/Spain) — A major supplier that is scaling production of silicon powder tailored for battery and advanced-technology segments; their announcements in 2026 indicate a pivot toward higher-purity, value-added grades.
- H.C. Starck and Wacker Chemie AG (Germany) — Suppliers of high-purity materials and feedstocks for specialty chemicals and silicones; price adjustments and strategic sales moves by chemical-grade suppliers in 2025–2026 have ripple effects across feedstock markets.
- Regional and specialty suppliers — A large number of Asia-based producers and a roster of North American and European specialty firms provide a spectrum of metallurgical, chemical, and ultra-pure powders. These suppliers are often the targets for upgrading investments or bolt-on acquisitions by integrated players seeking feedstock security or margin expansion.
We map each of these firms across three axes in the full report: product-grade capability (metallurgical → solar/electronics), integration and access to low-cost energy, and commercial strategy (spot vs. contract-focused sales). That view exposes where margins are likely to compress or expand over the next 18–36 months.
Recent developments that should alter 2026 plans
- Major producers are locking long-duration power agreements to de-risk energy exposure and preserve competitiveness in higher-purity segments.
- Some top chemical-grade suppliers enacted price adjustments in early 2026, which affects downstream silicone and feedstock cost bases.
- Announcements of targeted output for advanced-technology powders reflect supplier attempts to capture growing demand from batteries and semiconductor-related applications.
- Trade authorities and investigative processes initiated in 2025–2026 have increased the cost and complexity of cross-border sourcing; tariffs and investigation outcomes are now material variables in supplier selection.
What the PW Consulting report delivers — practical modules
Our full study is structured as a toolkit for action, not an academic exercise. Key deliverables include:
- An interactive market model with historical 2020–2025 series and a base-case plus alternative scenarios for 2026–2032 (using a 6.4% base CAGR), enabling sensitivity testing of price, demand, and cost inputs.
- Price and cost curves that isolate electricity, raw silica, and processing as the primary drivers of unit costs and margins.
- A global supply map and supplier scorecards that rate producers on grade capability, energy exposure, regulatory compliance, and commercial posture.
- A regulatory and tariff risk matrix that incorporates recent trade investigations and tariff policies to quantify sourcing risk by corridor and supplier.
- Procurement playbooks and sample contract language to balance spot, indexed, and fixed-price commitments for 12- to 60-month horizons.
- Capex decision frameworks with discounted cash flow templates and break-even analyses calibrated to the full range of grade-conversion options.
- Target lists and diligence checklists for M&A and strategic partnerships, including financial and operational metrics to de-risk transactions.
Each module is supported by primary interview insights, customs and trade-flow analytics, company disclosures, and verified secondary sources to ensure the output is decision-grade.
How to use this intelligence in 2026
Below are practical recommendations that flow directly from our findings and scenario analysis — they are actionable within 6–18 months and intended for executive teams preparing budgets, capital plans, or sourcing strategies this year.
- Procurement hedging: Prioritize multi-year contracts with energy-cost pass-through clauses and index-linked pricing where appropriate. Short-term spot exposure remains useful, but a balanced approach reduces margin volatility.
- Invest in grade conversion selectively: Evaluate upgrading capacity only where purity premiums and volume commitments materially improve IRR; partnering with downstream customers via offtake or co-investment can accelerate payback.
- Secure energy supply: Long-term power agreements or direct investment in captive renewable generation are effective ways to reduce production cost volatility — as already evidenced by recent large-scale power contracts.
- Reassess trade exposure: Run a corridor-level risk audit to measure the impact of ongoing investigations and tariffs on your sourcing and to identify alternative suppliers that can be on‑shored or diversified into your supply base.
- Acquisition playbook: Target specialty suppliers with high-purity capabilities, or regional producers with favorable energy economics, to accelerate entry into higher-margin segments. Use our diligence checklists to streamline integration risks.
- Commercial tactics: For sellers, augment spot sales with long-term supply solutions and technical support packages; for buyers, negotiate quality-linked price bands to control total cost of ownership.
Final note — what you will find in the full report
This preview is a curated view of the full intelligence suite. The complete report contains the granular segmentation, full regional and application breakdowns, supplier-specific scorecards and downloadable spreadsheets that underlie our scenarios. We deliberately withhold the detailed subsegment tables here to encourage decision-makers to engage with the full dataset: those granular breakouts are where procurement optimizations, capex returns, and acquisition targets become numerically precise.
For teams planning budgets and strategic moves in 2026, this study provides the market context, scenario machinery, and tactical playbooks to convert projected growth into sustainable advantage. Visit the PW Consulting report page to access the complete dataset, interactive models, and tailored advisory options that will align your 2026 decisions with the market’s most likely pathways.
For detailed analysis of this topic, please visit the official page: Silicon Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com