

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Server Chassis Market to hit USD 434 Million by 2032 at 3.5% CAGR

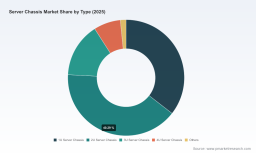
Server Chassis Market 2026: Strategic Imperatives for Procurement, Design and Global Supply Chains
As organizations accelerate compute deployments for AI, analytics and hybrid-cloud workloads, the server chassis market has shifted from a component-buying exercise to a strategic lever that shapes total cost of ownership, regulatory compliance, and long-term infrastructure flexibility. PW Consulting’s new Server Chassis Market study (base year 2025; forecast 2026–2032) synthesizes five years of historical trends and seven years of forward-looking scenarios to equip executives with the situational intelligence they need to make high-stakes decisions in 2026.
Server Chassis Market
Why this study matters for 2026 decision-makers
-
Macro clarity in an uncertain horizon: The market has expanded materially from 2020 to 2025 — moving from a smaller niche into a more established, multi-hundred‑million USD market (2025: USD 342.0 Million). Our forecast projects steady expansion through 2032 under a 3.5% CAGR for the 2026–2032 horizon, culminating in a materially larger market by 2032. These topline trends inform capital planning, inventory strategies, and product roadmaps.
Server Chassis Market -
Design choices drive compliance and operating cost: New regulatory dynamics in 2026 — notably EU-level energy-efficiency specifications that constrain allowable power draw per square meter — mean chassis footprint, cooling architecture and material selection are now variables in compliance, not just performance. Organizations that align chassis selection to these constraints can avoid expensive retrofits and depreciation write‑downs.
Server Chassis Market -
Supply chain and localization are strategic vectors: Raw material volatility (steel, aluminum), logistics bottlenecks, and national localization directives for compute hubs (with high domestic-sourcing thresholds) are forcing OEMs, hyperscalers and system integrators to rethink procurement. Sourcing strategies that previously prioritized lowest-cost suppliers now need to account for onshore availability, certification timelines and dual-sourcing for mission-critical builds.
Market shape and competitive dynamics
The Server Chassis market sits in a moderately concentrated competitive landscape. The three largest suppliers control a majority share of the market, with the top five accounting for roughly two thirds of industry revenue — a structure that supports scale advantages in manufacturing, supply agreements and engineering certification programs. That concentration creates both opportunities and risks for buyers and smaller vendors:
-
For buyers: scale suppliers offer rapid qualification paths and integrated product ecosystems (boards, storage, power), reducing integration risk for large rack deployments. However, dependence on a few suppliers can raise negotiation friction on lead-times and customization costs.
-
For challengers: specialization (short-depth edge chassis, GPU-dense enclosures, or heavy-duty industrial designs) is an effective route to carve durable niches. OEM/ODM partners that combine thermal expertise with bespoke manufacturing remain attractive to hyperscalers and regional cloud builders, particularly where localization rules apply.
Profiles and strategic moves to watch
-
Supermicro (San Jose) — Broad-form-factor portfolio and modular designs; recent product launches include a direct-to-chip liquid cooling chassis that signals intensified competition around cooling IP for GPU-dense AI workloads. Expect them to push liquid- and hybrid-cooling modules as a way to reduce operational costs in constrained data-center footprints.
-
Chenbro (New Taipei City) — Strength in short-depth and edge-optimized chassis; public demonstrations of integrated rack-level AI chassis at major industry shows underline their strategy to move from component supplier to system-level partner for AI deployments in constrained spaces.
-
OneChassis (Shenzhen) — OEM/ODM specialization with strong ventilation and GPU server case expertise; positioned to capture customized requirements from industrial and regional hyperscale builders, particularly where domestic sourcing policies reshape supplier lists.
-
ASUS (Taipei) — Integrated chassis solutions optimized for latest Xeon class processors and high-density AI/HPC nodes; they target customers that want board-to-chassis co-engineering and rapid validation cycles.
-
iStarUSA & Rosewill (United States) — iStarUSA’s industrial, high‑reliability focus and Rosewill’s AI/HPC-optimized 4U platforms address two fast-growing segments: rugged 24/7 edge compute and multi-GPU inference/training racks respectively. These players demonstrate divergent strategic responses to the same demand for density and thermal control.
-
Dell Technologies & Intel — Dell continues to leverage integrated PowerEdge ecosystems to sell chassis as part of broader, serviceable compute stacks; Intel’s purpose-built server chassis align with its platform strategy. Expect both incumbents to emphasize validated reference designs, supply assurance, and enterprise support as differentiators.
Recent product and ecosystem developments
-
Leading vendors are rapidly introducing chassis purpose-built for GPU workloads and alternative cooling: recent launches include liquid-cooling enabled chassis and 4U air-cooled designs tuned for modern inference GPUs. These product moves reflect an industry pivot: thermal architecture is now as decisive as rack density when evaluating chassis for AI workloads.
-
Trade-show reveals and live demos (e.g., integrated rack-level AI chassis showcased at major expos) are being used as go-to-market accelerants to demonstrate system-level performance and certification readiness.
Operational and strategic implications for 2026 planning
-
Procurement strategy: Move beyond price-per-chassis to a multi-metric evaluation that includes thermal efficiency, compliance footprint, validation cadence, and supplier localization capacity. Total cost of ownership modeling should incorporate energy constraints (driven by regional energy-efficiency rules) and potential tariff/local-content timelines.
-
Design and product roadmaps: For OEMs and ODMs, prioritize modular cooling platforms that can be reconfigured for either air or liquid cooling, and invest in validation suites for multi-GPU stacks. For enterprises, preferring standardized chassis families reduces integration cycles but ensure those families have upgrade paths for future compute accelerators.
-
Supply chain resilience: Implement dual-sourcing strategies for critical subcomponents, evaluate regional manufacturing partnerships to meet localization directives, and build material-cost sensitivity into procurement contracts to accommodate steel and aluminum price volatility.
-
M&A and partnerships: Given moderate market concentration, there is room for bolt-on acquisitions that add thermal IP, localized production footprint, or specialized chassis lines for industrial/edge use. Strategic partnerships between platform OEMs and cooling specialists will accelerate time-to-market for certified AI racks.
What the PW Consulting report delivers (operational, tactical and strategic tools)
-
Topline and scenario forecasts (2020–2032) with sensitivity analyses that reflect energy-regulation adoption, material-cost shocks, and abrupt demand swings from AI cycles.
-
Vendor scorecards covering engineering capabilities, manufacturing footprint, certification speed, and aftermarket support — designed to be used directly in RFP evaluation matrices.
-
Thermal & footprint decision frameworks that translate energy-efficiency limits into chassis selection criteria (air vs. liquid vs. hybrid) for specific deployment types (rack, edge, storage-dense nodes).
-
Procurement playbooks and contract clauses for localization and supply disruption mitigation — including recommended lead-time cushions and indexed price mechanisms tied to primary commodity indices.
-
Scenario-based TCO and depreciation templates that allow CIOs and procurement teams to quantify the impact of regulatory constraints and cooling architecture on both CAPEX and ongoing OPEX.
-
Executive-level strategic roadmaps: actionable 12–36 month plans tailored for OEMs, hyperscalers, and system integrators — highlighting where to invest in engineering, where to consolidate suppliers, and where to pursue joint‑development agreements.
Actionable next steps for leaders
-
Immediate (90 days): Audit chassis portfolios against regulatory footprint and cooling readiness; initiate RFIs for backup sourcing on long‑lead items such as large-panel steel and specialized backplanes.
-
Medium term (6–12 months): Run thermal-validation pilots for a liquid/hybrid-cooled chassis family; negotiate locality-compliant supply agreements if deploying into jurisdictional compute hubs subject to domestic-sourcing rules.
-
Strategic (12–36 months): Embed chassis selection into platform-level product strategies, including co-engineering paths with board and cooling suppliers; consider M&A or JVs to secure critical manufacturing capacity in key regions.
Where to go for the full intelligence
This introduction outlines the strategic contours PW Consulting sees shaping the Server Chassis market in 2026. The full report contains proprietary segmentation, region- and application-level forecasts, supplier financial profiles, split-by-type demand modeling, and downloadable procurement tools. To access the comprehensive datasets and vendor-level tables that operationalize the recommendations summarized here, visit the PW Consulting Server Chassis Market page — the detailed numbers and segmentation breakdowns are available in the full study.
For custom briefings, scenario simulations tailored to your fleet, or confidential supplier benchmarking, PW Consulting’s advisory team is available to translate the market intelligence into executable plans indexed to your deployment timelines and regulatory exposures.
For detailed analysis of this topic, please visit the official page: Server Chassis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com