

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hybrid Excavators Market to Hit USD 3.19B by 2032, Growing at 9.4% CAGR — PW Consulting

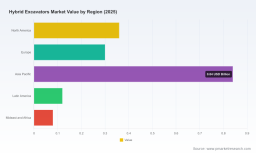
Hybrid Excavators Market—Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As construction fleets and infrastructure owners accelerate emissions and efficiency programs, hybrid excavators have moved from niche technology to strategic asset class. Our market model—anchored on a 2025 base year—shows global market value expanding from approximately USD 1.7 Billion in 2025 to an expected USD 3.19 Billion by 2032, at a compound annual growth rate (CAGR) of 9.4% across the 2026–2032 forecast window. This briefing explains why that trajectory matters for capital allocation, product strategy, supply-chain decisions and regulatory compliance in 2026, and what pragmatic workstreams senior executives should prioritize this year.
Hybrid Excavators Market
Why PW Consulting’s Hybrid Excavators study is decision-relevant in 2026
-
Actionable forecasting: Our base-case pathway and two alternate scenarios quantify the pace and shape of adoption that will affect fleet replacement cycles, residual value curves and TCO (total cost of ownership) modeling—inputs that determine near‑term procurement and financing decisions.
Hybrid Excavators Market -
Regulatory alignment: The report integrates 2026 regulatory inflection points—both regional and supranational—so product teams and compliance functions can reconcile design roadmaps with evolving warranty, durability and recycling mandates.
Hybrid Excavators Market -
Supply-chain levers: We map critical material constraints and supplier concentration that will influence pricing, lead times and risk buffers for hybrid systems—from hydraulic hybrid subsystems to battery/electrical integration.
-
Competitive intelligence: The study provides an up-to-date competitive matrix and playbook for market entry, partnerships and aftermarket service differentiation—translating public product moves into strategic posture recommendations.
Market trajectory and underlying dynamics
The hybrid excavator market has recorded steady growth through the early 2020s, and our analysis identifies 2026 as a transition year where technology, policy and cost vectors converge. After growing from roughly USD 1.22 Billion in 2020 to USD 1.7 Billion in 2025, the market is forecast to accelerate, reaching USD 1.87 Billion in 2026 and progressing to USD 3.19 Billion by 2032. The 9.4% CAGR is supported by three structural dynamics:
-
Policy-driven demand: Urban zero-emission construction mandates and stricter emissions durability requirements introduced in 2026 increase the economic attractiveness of hybrid systems in regulated sites and city projects.
-
Operational economics: For many users, hybrids provide measurable fuel savings and duty-cycle advantages—advantages that compound when combined with smarter fleet-management and energy-recapture features.
-
Technology maturation: Improvements in battery energy density, power electronics and hydraulic hybrid controls are reducing weight, complexity and service overhead while enabling new machine architectures.
Regulation and material constraints that will shape 2026 decisions
Two regulatory and materials developments deserve immediate attention:
-
Battery recovery and recycling: New material-recovery thresholds for lithium-ion batteries require high collection and processing rates starting in 2025 with elevated targets through 2030. These mandates influence supplier selection, end-of-life planning and warranty reserves for OEMs and fleet operators (source: The International Council on Clean Transportation, Feb 2026).
-
Durability and labeling requirements: Emissions and battery labeling requirements effective in 2026 introduce minimum state-of-health thresholds and warranty disclosure obligations that affect product specifications and risk provisioning (source: California Air Resources Board, Feb 2026). These rules already shape procurement criteria for public and private construction projects in regulated jurisdictions.
Supply-side patterns and competitive posture
The hybrid excavator market displays moderate fragmentation with room for consolidation. Our market concentration metrics show that the top three firms collectively account for a material but not dominant share of the market (CR3 circa 28%), while the top five rise to a larger portion (CR5 circa 42%). The practical implication is that well-timed product differentiation, warranty and service models can yield meaningful share gains without confronting a locked oligopoly.
Key OEMs are executing visible hybrid programs:
-
Komatsu (Tokyo) has commercialized models including the HB365LC-3 and intelligent PC220LCi-12 series; the OEM has begun deliveries to contractors and is focusing on integration into rental fleets and larger project applications.
-
Kobelco (Kobe) maintains a steady hybrid line with models such as the SK210 Hybrid, reinforcing its reputation in mid-size segments.
-
Volvo Construction Equipment (Gothenburg) launched a generation of hybrid machines in early 2025 and showcased larger crawler hybrids at ConExpo 2026—moves that underline a push into both commercial and large-scale contractor accounts.
-
Caterpillar (Irving) continues to iterate on its XE/ H lines (e.g., Cat 336F L XE Hybrid), targeting traditional Cat customers with improved fuel economy and serviceability.
-
Hitachi, Takeuchi and Liebherr are each pursuing targeted hybrid offerings, with demonstrations and product showcases in 2025–2026 reinforcing their channel strategies.
Recent milestones (product launches, trade-show reveals and first deliveries) demonstrate that manufacturers are moving from pilots and demonstrations to commercial deployments—an inflection that changes procurement, leasing and aftermarket service dynamics.
What the report contains—practical outputs for executives
Our Hybrid Excavators Market report is structured to be immediately operational for strategy teams. Highlights include:
-
Proprietary demand model (2020–2032) with scenario toggles, sensitivity tables and an executive dashboard for quick “what-if” toggles.
-
CapEx and TCO frameworks that tie machine pricing, fuel savings, maintenance intervals and residual-value assumptions into actionable procurement guidance.
-
Supplier and raw-material matrix that flags single-source exposures, lead-time risk and expected price volatility for battery packs, power electronics and hydraulic components.
-
Regulatory impact assessment—mapping new rules to product, labeling and service obligations across key jurisdictions and outlining compliance timelines.
-
Competitive landscape chapter with position maps, product-matching matrices and a ranked list of near-term strategic plays for OEMs, rental companies and large contractors.
-
Go-to-market playbooks—rental channel penetrations, OEM-retailer agreements, aftermarket service bundles and financing structures to accelerate adoption.
-
Risk matrix and mitigation checklist covering supply interruptions, battery recovery compliance, warranty exposures and secondary-market dynamics.
Note: this briefing intentionally omits the granular regional, type and application splits that sit in the full report—those segment-level tables are core to our premium analysis and are accessible through the report portal.
Strategic implications and recommended 2026 workstreams
Based on our synthesis, three near-term priorities should shape executive agendas this year:
-
Embed regulatory-forward design and warranties: Product and legal teams must align battery warranty terms, labeling and state-of-health measurement protocols with 2026 requirements. This will reduce bid rejection risk on public projects and limit latent liability.
-
Lock supply resilience for critical subsystems: Procurement and supply-chain teams should secure multi-sourced battery and electronics capacity and construct inventory buffers for key hydraulic hybrid components—particularly for firms targeting fleet-scale rollouts in 2026–2027.
-
Commercialize service and financing packages: Leasing and rental operators that pair hybrid machines with tailored service contracts and uptime guarantees will unlock adoption among cost-sensitive contractors. Offerings that monetize fuel and emissions savings via shared-payback or outcome-based contracts will be particularly attractive.
Medium-term moves (12–36 months)
-
Refine product segmentation and option bundles using our scenario outputs—prioritize platforms that are modular for both battery and hydraulic upgrades to protect against technology obsolescence.
-
Pursue strategic partnerships for battery lifecycle management, including collection, remanufacture and certified recycling arrangements to comply with tightening recovery mandates.
-
Invest in digital telematics and fleet-management features that demonstrate measurable lifecycle benefits and support differentiated residual-value claims.
How to use the full report in 2026 planning cycles
Senior teams should integrate three deliverables from the full report into 2026 planning:
-
Scenario-aligned procurement plan for 2026–2028 capital budgets that incorporates policy-driven demand shifts and TCO sensitivity to fuel and energy prices.
-
Supplier risk dashboard to inform supplier selection, contracting terms and inventory strategy for battery and hydraulic subsystems.
-
Commercialization roadmap for hybrid product variants, with pricing benchmarks and aftermarket revenue models derived from our detailed model.
Closing—what to do next
The technical and policy inflections of 2026 make this year a pivotal planning window. Our analysis confirms a market that is large enough to reward scale and focused enough to be influenced through targeted product, supply-chain and commercial moves. For teams evaluating procurement, M&A, or product roadmaps, the investment of time in our full dataset and segment-level analysis will uncover immediate cost-savings, risk mitigations and revenue opportunities that cannot be inferred from public statements alone.
To access the complete datasets, regional and application splits, pricing curves and supplier matrices that underpin the above synthesis, request the full Hybrid Excavators Market report from PW Consulting. The full deliverable contains the segment tables, model inputs and supplier-level intelligence required to operationalize the strategies outlined here.
For detailed analysis of this topic, please visit the official page: Hybrid Excavators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com