

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
HVAC Systems Market to Reach USD 462.03 Billion by 2032 at 6.4% CAGR — PW Consulting

HVAC Systems Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As organizations navigate the intensifying crossroads of decarbonization, electrification, and digital transformation, HVAC systems have moved from a utility-line item to a strategic lever for costs, emissions, and occupant experience. PW Consulting’s latest market study—anchored on a 2025 base year, with a historical window of 2020–2025 and a forecast horizon spanning 2026–2032—translates market dynamics into decision-ready insights. The global HVAC market, which expanded materially through the first half of the decade, is projected to sustain a mid-single-digit compound annual growth rate (6.4% CAGR) through 2032. In revenue terms, the market grew substantially from the early-2020s and is expected to approach the mid-hundreds of billions of USD by the end of the forecast period—underscoring both scale and strategic opportunity for equipment manufacturers, contractors, real-estate owners, and technology vendors.
HVAC Systems Market
Why this report matters for 2026 decisions
-
Timing and scale: 2026 is a pivot year. Macro drivers—new refrigerant regulations, shifts in fiscal incentives, and supply-chain cost pressures—are converging, and our report quantifies their near-term and medium-term impacts. Strategy teams need a grounded view of growth trajectories and stress-test scenarios to prioritize capex, product roadmaps, and channel investments.
HVAC Systems Market -
Regulatory inflection points: The transition to lower-GWP refrigerants (A2L-class transitions and similar mandates) and updated operation standards (e.g., ASHRAE Guideline updates) create both compliance risk and product upgrade opportunities. Manufacturers that integrate refrigerant-transition roadmaps into product development will avoid obsolescence and capture retrofit demand.
HVAC Systems Market -
Investment precision: With the market expanding at a 6.4% CAGR through 2032, the question is not whether to invest but where. Our analysis distinguishes durable growth pockets from cyclical retrofit markets, and differentiates value pools that favor high-efficiency hardware, digital controls, and services-led revenue models.
What’s inside the PW Consulting study (practical, executable components)
-
Market sizing and validated forecasts. We provide an end-to-end revenue model—historical validation through 2025 and scenario-based forecasts to 2032—so executives can quantify implications for manufacturing, distribution, and services.
-
Technology roadmaps and product implications. Comparative assessments of heat-pump adoption, inverter technologies, centrifugal compressors, and A2L refrigerant engineering requirements, paired with recommended development timelines and testing priorities.
-
Go-to-market and channel strategies. Segmented playbooks for residential, commercial, and industrial channels that balance direct sales, dealer networks, and digital platforms—each with operational metrics and suggested incentive structures.
-
Supply-chain stress testing. Component concentration analyses, tariff exposure matrices, and mitigation levers such as dual sourcing, nearshoring, and inventory hedging strategies.
-
Service and retrofit economics. A modular framework for pricing long-term service contracts, electrification retrofits, and controls upgrades—helping OEMs and service providers convert installed-base penetration into recurring revenue.
-
M&A and partnership playbooks. Transaction screens, synergy checklists, and integration risk flags—useful for corporates seeking inorganic growth or capability fills.
-
Investment case templates. Ready-to-use models that translate market scenarios into ROI and NPV outcomes for specific product launches or manufacturing expansions.
Competitive landscape — how to read the field in 2026
The HVAC landscape remains characterized by a mix of global OEMs, specialist suppliers, and emerging technology entrants. The market concentration metrics indicate modest concentration: the leading firms collectively hold a meaningful share but do not create a tight oligopoly (CR3 and CR5 metrics are aligned, reflecting a competitive field with room for regional champions and niche specialists). For leaders and challengers alike, there are three themes to watch.
-
Scale plus systems thinking: Firms that combine large-scale manufacturing with systems and services capabilities will sustain margin advantages. Trane Technologies, Carrier, and Daikin exemplify this approach—each pursues scale in commercial systems while advancing higher-efficiency platforms and integrated building solutions.
-
Controls and digitalization as tie-breakers: Honeywell and similar building-automation players are converting control architectures into defensible recurring-revenue streams. For OEMs, integrating advanced controls and analytics into product lines is a non-negotiable to defend installed-base economics.
-
Segment-focused differentiation: Companies that double down on a core segment—residential simplicity versus high-efficiency commercial chillers or ductless systems—can outcompete on product-market fit and service models. Mitsubishi Electric and Lennox illustrate distinct plays focused on ductless/light-commercial and residential markets, respectively.
Recent strategic moves worth benchmarking
-
Technology collaborations. Early-2026 partnerships to develop oil-free centrifugal compressors signal a technology race to reduce lifecycle operating costs and maintenance—initiatives that can materially alter total cost of ownership in large commercial projects.
-
Product-led simplification. New product launches aimed at simplifying installation and retrofit highlight a practical growth lever: reduce required labor skill and install time to unlock retrofit opportunities in aging building stock.
-
Portfolio reshaping. Recent divestitures and business sales underscore the importance of portfolio clarity—corporates are rationalizing overlapping product sets to fund innovation and sharpen go-to-market execution.
-
Flagship projects. Multi-year campus modernization programs continue to act as living labs for integrated solutions, offering pipeline visibility and marketing proof points for advanced HVAC architectures.
Industry dynamics and headwinds
-
Regulatory transitions. New refrigerant GWP caps and updated operational guidelines are forcing product reengineering and compliance roadmaps. Firms that lock in certification and demonstration projects early will shorten sales cycles for public and institutional customers.
-
Incentive timing. Several federal tax incentives and rebates that accelerated adoption in prior years have sunsetted or shifted—creating a near-term pullback in some retrofit projects but also a window for policy-aligned urgency if incentives are renewed.
-
Cost pressures. Tariffs and component-price volatility are compressing margins for manufacturers with concentrated supplier exposure. Procurement plays—nearshoring, strategic stock levels, and vertical integration—are essential mitigations.
-
Standards and performance expectations. New ASHRAE sequences of operation and similar standards are raising the baseline for energy performance, benefiting vendors who can demonstrate compliance and optimized sequences in commissioning.
Practical strategic moves for executives in 2026
-
Prioritize retrofit-ready product lines. With large installed bases approaching mid-life, products engineered for low-friction retrofits will capture disproportionate demand.
-
Accelerate refrigerant transition plans. Align R&D, testing, and certification timelines to regulatory deadlines to avoid market access delays and retrofit churn.
-
Embed controls and services. Re-balance GTM models toward integrated hardware + software + service bundles to increase lifetime customer value and resiliency against commoditization.
-
Stress-test supply chains. Run scenario plans that model tariff shocks, lead-time extensions, and single-supplier failures; determine acceptable inventory and dual-source thresholds.
-
Use M&A tactically. Target acquisitions that add digital capabilities, service footprints, or regional manufacturing to accelerate time-to-market and margin expansion.
How PW Consulting’s dataset supports execution (and what’s intentionally withheld here)
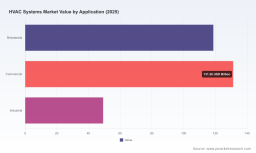
Our full study contains granular segmentation by region, application, and equipment type, unit economics, supplier mapping, and a downloadable model that allows you to run custom scenarios for investment planning and product prioritization. In this executive summary we deliberately present the macro trajectory—the verified market expansion to 2025 and the 6.4% CAGR through 2032—to demonstrate direction and scale. To protect the commercial integrity of the granulated intelligence, we do not disclose the detailed regional or application revenue splits in this public introduction. For market entrants and incumbents who require the full taxonomy, downloadable datasets, and the scenario-enabled financial model, access to the full report is available through our client portal.
Final note — positioning for 2026 and beyond
The HVAC market’s growth and transformation are no longer optional background factors; they are primary business drivers for manufacturers, developers, fleet operators, and public-sector buyers. The combination of sizeable market scale, regulatory inflection, and technology migration creates a narrow window in 2026 for firms to reallocate R&D budgets, lock in supply-chain resilience, and convert installed-base exposure into recurring-service platforms. PW Consulting’s report is designed to move leaders from awareness to action: calibrated forecasts, executable playbooks, and transaction-ready advice to turn market momentum into defensible advantage.
To obtain the full dataset, segment-level breakdowns, and scenario model that underpin these conclusions, please visit our report access page or contact the PW Consulting market insights team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: HVAC Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com