

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive PVC & PU Leather Market to grow at 6.5% CAGR — PW Consulting

Automotive PVC & PU Leather Market — Strategic Briefing for 2026 Decision-Makers
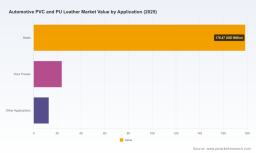
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision-focused introduction to our Automotive PVC and PU Leather Market study (base year 2025; forecast period 2026–2032). The global market for synthetic automotive interior leather has returned to a durable growth path following pandemic-era volatility: the market expanded from roughly USD 163 million in 2020 to USD 215 million in 2025, and is projected to reach approximately USD 345 million by 2032 at a compound annual growth rate (CAGR) of 6.5%. This briefing highlights the study’s strategic value for 2026 decision-making while intentionally withholding granular subsegment tables and region/application splits to preserve the full report’s commercial intelligence value.
Automotive PVC and PU Leather Market
Why this study is mission-critical in 2026
-
Interior differentiation has moved to the top of OEM agendas. Electrification and new mobility formats increase the importance of tactile quality, perceived sustainability, and modular interior architectures—drivers that directly affect material specification and supplier selection.
Automotive PVC and PU Leather Market -
Sustainability is no longer a compliance checkbox. OEMs are implementing aggressive Scope 1/2/3 targets and requiring suppliers to demonstrate lower carbon intensity, circularity credentials, and verified bio-based or recycled feedstocks.
Automotive PVC and PU Leather Market -
Procurement volatility: raw-material price swings and geopolitically driven supply constraints require proactive sourcing strategies, dual-sourcing, and inventory hedging that are tailored by product family and quality tier.
-
Competitive dynamics are shifting: established specialty players, regional champions, and high-capacity manufacturers are each pursuing distinct value plays—creating M&A and partnership opportunities for OEMs, Tier-1s, and investors.
What the PW Consulting study delivers — practical outputs
-
Comprehensive market model: bottom-up market sizing (historical 2020–2025, base 2025) and scenario-based forecasts through 2032, with sensitivity levers for raw-material price, EV penetration, and circularity uptake.
-
Supplier landscape and scorecards: validated supplier profiles, capability matrices, capacity mapping, preferred-OEM footprints, and a procurement readiness index to accelerate supplier selection and qualification.
-
Commercial playbooks: price build-ups, contract templates, indexation clauses, and negotiation frameworks aligned to material types and finish levels.
-
Technical and sustainability roadmaps: technology adoption timelines for bio-based PU, recycled-content PVC, low-VOC coatings, and scalable recycling processes; carbon-impact accounting templates for supplier audits.
-
Regulatory and compliance compendium: jurisdictional requirements, anticipated regulatory levers (chemical restrictions, product-labeling), and impact heatmaps for product development and sourcing.
-
Strategic M&A and partnership playbook: target-screening criteria, valuation benchmarks, integration risks, and post-merger operating models for capacity, technology, or sustainability assets.
Market trajectory and what the numbers imply for 2026
The empirical arc captured in our model shows a market that weathered near-term disruption, rebounded into 2024–2025, and is positioned for steady expansion under multiple plausible scenarios. From the 2025 base, the forecast path to 2032 reflects a blend of steady OEM demand for premium and mid-tier interiors, increasing adoption of engineered synthetic leathers for EVs and shared-mobility platforms, and incremental price inflation tied to raw-material and energy costs.
For 2026 specifically, the market is forecast to grow further from its 2025 base. This near-term uptick will be driven by production ramps from major OEM platforms and the progressive replacement of older materials in mid-cycle refreshes—making 2026 a pivotal year for firms to lock in supplier capacity, secure sustainable feedstocks, and align product roadmaps with OEM sustainability timelines.
Competitive landscape — fragmentation, capabilities and recent moves
The market remains fragmented: concentration metrics indicate modest clustering at the top (CR3 roughly 24.6%; CR5 roughly 26.2%), which signals that no single group of suppliers yet dominates the industry. That fragmentation creates both risk (inconsistent standards, uneven supplier maturity) and opportunity (niche consolidation, vertical integration, and selective buyouts).
-
Benecke‑Kaliko AG (Germany) — recognized for PVC foam laminates and expanded PVC leather products; long-standing preferred-supplier relationships with major OEMs underscore their relevance in high-spec interior programs.
-
Kyowa Leather Cloth Co., Ltd. (Japan) — strong global position in synthetic seating and cockpit materials with depth in high-reliability applications.
-
Mayur Uniquoters Limited (India) — competitive producer of PVC vinyl and PU leather, focused on seat upholstery and door-trim markets in high-volume geographies.
-
Vulcaflex S.p.A. (Italy) — an innovation-led player that recently launched an eco-leather product (Nextethic) and announced ambitious Scope 1 decarbonization targets and increased OEM supply commitments.
-
Fujian Polyrech Technology (China) — prominent in production lines for PU/PVC synthetic leather and active in global industry showcases, signaling expansion of market reach.
-
Other notable regional players include high-capacity manufacturers across Asia and specialty engineered-fabric firms in North America and Europe—each occupying differentiated roles in price, quality and sustainability vectors.
Recent corporate moves are instructive: product launches focusing on circular and bio-based materials, public commitments to near-term Scope 1 reduction, and OEM supply agreements announced in late 2025–early 2026 all demonstrate that sustainability-linked commercial demand is accelerating. These developments shift supplier selection criteria from purely technical performance to a combined performance–sustainability score.
Practical strategic implications for 2026 decisions
-
Procurement & supplier strategy: Move from transactional sourcing to supplier ecosystem management. Prioritize dual-sourcing for high-risk feedstocks, audit supplier sustainability claims, and secure long-lead agreements with indexation to raw-material baskets.
-
Product portfolio & R&D: Invest selectively in bio-based PU and recyclable PVC formulations that meet OEM circularity requirements without sacrificing durability. Short-term: prioritize finish systems that reduce VOCs and enable easier separability for end‑of‑life recovery.
-
Manufacturing footprint: Favor flexible, modular production assets that can reconfigure between PVC and PU lines to respond to demand swings. Nearshoring or regional hubs may reduce logistic risk and carbon exposure.
-
Commercial models: Institutionalize total-cost-of-ownership (TCO) pricing models that internalize carbon costs and end‑of‑life disposal fees; OEMs and Tier‑1s should incentivize suppliers through sustainability-linked payment terms.
-
M&A and partnerships: Target bolt-on acquisitions in niche bio-based chemistries, recycling tech, or capacity-rich regional producers. Strategic joint ventures with polymer specialists can fast-track technology transfer and capacity expansion.
-
Regulatory & compliance readiness: Implement product stewardship programs, chemical compliance tracking, and certification roadmaps aligned to major OEMs and regional regulators to de‑risk launch cycles and avoid costly redesigns.
How to use the PW Consulting report in your 2026 planning cycle
Our study is designed as an operational toolkit for procurement, R&D, corporate strategy, and corporate development teams. Key ways clients leverage the report include:
-
Embedding the forecast model into annual budgeting and capital‑allocation exercises to quantify revenue and margin impacts under different EV and sustainability uptake scenarios.
-
Using supplier scorecards and the procurement readiness index to re-rank approved vendors and prioritize qualification resources.
-
Adopting the sustainability roadmaps and carbon-accounting templates to fast-track supplier audits and to negotiate sustainability-linked commercial terms.
-
Executing targeted M&A diligence using our target-screening criteria and integration-risk checklists to accelerate deals in 2026.
What we intentionally withhold here — and why
In keeping with the “trailer” principle, this briefing demonstrates our analytical framing and the specific strategic levers available to market participants while withholding the granular regional and application split tables, supplier-level volumes, and price‑curve spreadsheets that comprise the report’s most actionable competitive intelligence. These detailed data assets are the core value proposition of the full report and are accessible via the PW Consulting distribution channel for licensed subscribers and advisory clients.
For leadership teams planning capital allocation, supplier negotiations, or strategic M&A in 2026, the full dataset—paired with a short advisory engagement—will convert these high-level implications into executable plans with quantified ROI, scenario-stress testing, and a prioritized implementation roadmap.
To discuss how PW Consulting can embed this study into your 2026 planning processes, or to obtain the full report and supporting models, contact our advisory team for a tailored briefing and data access.
For detailed analysis of this topic, please visit the official page: Automotive PVC and PU Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com