

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plastic Medical Packaging to reach USD 84.92M by 2032, 3.7% CAGR

Plastic Medical Packaging Market: Strategic Briefing for 2026 Decision‑Makers (PW Consulting)
Executive summary
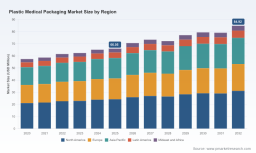
As the healthcare value chain accelerates its adoption of single‑use devices, biologics and point‑of‑care therapies, plastic medical packaging remains a small but strategically critical market. Our proprietary model—anchored on a 2025 base year and spanning historical performance from 2020–2025 with forecasts through 2032—shows the market growing at a steady compound annual growth rate (CAGR) of 3.7% over the forecast interval. That steady growth trajectory reflects a combination of stable core demand for sterile barrier and device protection solutions, punctuated by episodic volatility from regulation, raw material cycles and sustainability innovation.
Plastic Medical Packaging Market
For executives planning product roadmaps, site investments or M&A in 2026, the value of this research is twofold: it translates macro momentum into actionable commercial and operational levers, and it isolates where regulatory and technological inflection points will create winners and losers. This briefing highlights the report’s strategic relevance while preserving the detailed segmentation and firm‑level financials that we reserve for the full report.
Plastic Medical Packaging Market
Why this matters for 2026 decision cycles
- Capital allocation and site strategy: With compliance obligations and inspection regimens evolving, decisions on new cleanroom capacity, near‑shoring, or consolidation must be stress‑tested against scenario forecasts that include regulatory shocks and resin price swings.
- Product portfolio optimisation: Proprietary packaging formats (injection‑molded trays, thermoformed blisters, high‑barrier films) deliver differential margins under different regulatory and sustainability constraints; choices made in 2026 determine cost curves for the next decade.
- M&A and partnerships: A moderately concentrated market structure (our concentration metrics show the top three and top five suppliers controlling a material share of supply) creates a window for both platform acquisitions and tuck‑ins—if acquirers can accurately value certification asset bases, IP around barrier coatings, and validated supply chains.
- Regulatory compliance as competitive advantage: New inspection frameworks and recycled content policies mean compliance is no longer a cost center—it's a go‑to‑market differentiator for customers who must certify sterile barrier packaging and traceability.
Market dynamics shaping strategy in 2026
- Steady baseline growth with episodic inflections: Underlying demand is predictable and insurance‑driven, but regulation and sustainability initiatives periodically accelerate adoption of new materials or formats. The market’s CAGR of 3.7% masks pockets of faster structural change that merit targeted investment.
- Regulatory tightening and certification burden: Two developments are especially consequential this year: the EU Packaging and Packaging Waste Regulation (PPWR) framework, with obligations coming into force during 2026, and the replacement of older FDA inspection methodologies with the Quality Management System Regulation (QMSR) in the U.S. These shifts raise the bar on traceability, records and design‑for‑recyclability documentation. Notably, the PPWR includes exemptions and phased approaches for pharmaceutical and medical device packaging, but the broader harmonised extended producer responsibility architecture will still affect supply‑chain reporting and cross‑border logistics.
- Standards and sterile barrier constraints: ISO 11607 pathways and related sterile barrier requirements continue to restrict the use of mechanically recycled content in many certification routes. This introduces a tension between sustainability goals and validation timelines—manufacturers seeking recycled content must navigate alternative compliance pathways or invest in validated specialty resins.
- Material and manufacturing realities: Medical‑grade HDPE, PP and PET feedstocks remain dominant due to biocompatibility and production maturity. Injection molding and thermoforming in controlled cleanroom environments under ISO 13485 remain the backbone of supply. The report maps the technical tradeoffs—sealing strength, breathability, sterilisation compatibility—that drive format selection.
- Innovation in sustainability and barrier technologies: The market is responding with differentiated technical solutions rather than one‑size‑fits‑all recycled content claims. Recent industry developments illustrate the direction: next‑generation heat‑seal coatings that improve seal strength and breathability, medical‑grade films incorporating post‑consumer recycled content, and packaging redesigns aimed at material reduction and lean sterile tray architecture. These are commercially significant because they change qualification time and procurement criteria.
- Supply‑base concentration and competitive posture: Market concentration metrics indicate meaningful scale benefits for incumbent suppliers, but also room for specialised players with cleanroom-certified capabilities. Scale advantages manifest in validated production sites, multi‑market regulatory dossiers and captive logistics for temperature‑sensitive pharma supply chains.
What the PW Consulting report delivers (practical, operational outputs)
- Proprietary time‑series demand model (2020–2032) with scenario overlays to stress test regulatory, raw material and sustainability outcomes.
- Step‑by‑step regulatory playbook for compliance readiness in the EU and U.S., including timelines, documentation templates and audit checklists aligned to QMSR and ISO 11607 considerations.
- Practical go‑to‑market frameworks for selling into pharma, device OEMs and contract packagers: buyer personas, procurement KPIs, and a pricing architecture that accounts for validation overheads.
- Supply‑chain risk matrix with mitigation playbooks—near‑shoring triggers, dual sourcing blueprints and design strategies to reduce single‑sourced technical dependencies.
- Competitive landscape with verified supplier capability maps (cleanroom classes, ISO certifications, core format expertise), plus a curated M&A heat map highlighting accretive targets and valuation levers.
- Technology and material briefings: performance tradeoffs for injection molding vs thermoforming vs flexible films; barrier innovations; and practical guidance on integrating recycled content without compromising certification timelines.
- Board‑ready executive summary and an investor‑grade annex for use in due diligence and transaction planning.
Competitive landscape: who matters and why
The report profiles established global specialists, precision molders, and regional cleanroom providers. A non‑exhaustive set of players we examine in detail includes full‑service system providers and niche specialists—firms that contribute diversified value propositions from primary closures and seals to thermoformed trays and protective films.
Plastic Medical Packaging Market
- Full‑service and systems providers: Companies with broad portfolios—including closures, seals and primary containers—benefit from bundled qualification opportunities and stronger leverage with large pharma customers. Their commercial playbook is to convert single‑product wins into platform relationships.
- Precision dispensing and closure specialists: Precision molding and complex closure systems require tight tolerances and validation expertise. These suppliers win when product performance and error rates are mission‑critical (e.g., parenteral applications).
- Thermoforming and custom rigid packaging specialists: Cleanroom capabilities and ISO 13485 certification are differentiators for firms that serve device OEMs. Speed to validation and cleanroom scalability are the decisive selection criteria for procurement teams.
- Protective film and secondary packaging suppliers: As supply chains require better protection during transit and storage, film solutions that combine barrier performance and sustainable content are gaining traction.
Recent industry moves—new heat‑seal coatings that improve breathability, award‑winning films with significant recycled content, and conference presentations on press‑fit seals—underscore the split between incremental product improvement and platform‑level innovations that shorten qualification or materially reduce material use. Our competitive profiles identify where each vendor’s strategic advantage lies (e.g., IP in sealing chemistry, depth of in‑house validation, or scale in cleanroom manufacturing) and how that advantage translates into commercial outcomes.
Strategic implications and recommended 2026 actions
- Prioritise compliance investments that double as commercial differentiators: Invest in traceability systems and QMS upgrades now—buyers increasingly use supplier compliance as a selection filter.
- Design for validation: Where possible, select materials and formats that shorten customer qualification cycles (e.g., coatings that maintain or improve barrier performance without triggering revalidation).
- De‑risk supply chains: Implement dual‑sourcing for critical resins and plan staged near‑shoring of validated capacity to reduce lead‑time exposure and tariff risk.
- Targeted sustainability bets: Pursue recycled content or alternative feedstocks only where certification pathways are cleared; otherwise, focus on material reduction, recyclable‑by‑design and reclaim schemes that improve life‑cycle metrics without compromising ISO 11607 timelines.
- Measured M&A: Use bolt‑on acquisitions to acquire certifications, validated production lines or distribution access rather than volume alone. Our valuation templates show how certification assets and validated customer contracts can command premium multiples.
- Commercial sophistication: Move from price‑only negotiations to value‑based contracting that monetises reduced qualification cost, logistical simplification and regulatory risk transfer.
How to use this research in board and deal rooms
- Embed our scenario model into capital planning to quantify the payback on cleanroom investments under conservative and aggressive regulatory paths.
- Use the regulatory playbook as a gap analysis tool before committing to new material mixes or recycled content claims.
- Leverage supplier capability maps and our M&A heat map during vendor selection and diligence to avoid overpaying for capacity that lacks validated dossiers.
- Adopt the go‑to‑market frameworks to reprice contracts with large OEMs and to realign sales incentives towards platform adoption and long‑term supply agreements.
Next steps
This briefing is a strategic “trailer” intended to illuminate the high‑value conclusions of our Plastic Medical Packaging Market study. The full report contains the detailed segmentation, supplier share analytics, and downloadable time‑series datasets that underpin the models summarised here. Access the complete research package for the granular datasets, validation checklists and company financials required to execute on the recommendations above.
PW Consulting’s senior advisory team is available to run a tailored workshop for your leadership or a focused diligence sprint for planned transactions. For access to the full report, scenario files and data extract, please visit our research portal or contact your engagement lead.
For detailed analysis of this topic, please visit the official page: Plastic Medical Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com